Asian Naphtha Crackers Face Margin Pressures as Global Oversupply Reshapes Feedstock Strategy
Asian naphtha crackers are facing a difficult operating environment as new petrochemical capacity continues to outpace regional demand. Asian naphtha crackers have seen operating rates fall to multi-year lows, increasing pressure on producers to protect margins while managing feedstock costs.
The imbalance is changing how crackers approach feedstock selection. Producers are increasingly shifting toward lighter feedstocks where economics allow, creating new implications for naphtha demand, regional trade flows and procurement strategies.
For chemical traders and buyers, the development matters beyond cracker utilisation. Changes in feedstock preferences can influence naphtha buying patterns and the broader availability and pricing dynamics of petrochemical intermediates across Asia.
Why Asian Naphtha Crackers Are Cutting Operating Rates
Cracker economics depend heavily on the relationship between feedstock costs and the value of products such as ethylene, propylene and other olefins. When product markets weaken while feedstock expenses remain elevated, producers face tighter margins.
The current Asian market combines several pressures. New capacity has expanded regional supply while demand has not increased quickly enough to absorb the additional output.
Lower operating rates provide producers with a way to manage excess supply and reduce exposure to unfavourable economics. However, sustained reductions can also affect regional feedstock demand and the purchasing patterns of large petrochemical companies.
The pressure is particularly significant for crackers that rely heavily on naphtha. These facilities must continually evaluate whether their existing feedstock slate remains economically competitive against alternative lighter feedstocks.
Global Oversupply Is Changing the Cracker Economics
The central issue is the widening gap between available petrochemical production capacity and regional consumption. When new plants enter the market faster than demand expands, producers compete for a smaller share of available downstream demand.
This can weaken product prices and compress cracker margins. Producers then have several options, including reducing operating rates, adjusting feedstock selection or focusing on products and markets with stronger economics.
For procurement teams, oversupply creates a market where purchasing decisions require more than simply monitoring naphtha prices. Buyers must also consider:
Cracker utilisation: Lower operating rates can reduce immediate feedstock requirements and change regional buying patterns.
Feedstock flexibility: Facilities capable of processing different feedstocks can respond more quickly when relative economics change.
Product demand: Weak demand for key olefins can limit the economic incentive to maintain high cracker utilisation.
Regional competition: Additional capacity can intensify competition between producers across major Asian petrochemical hubs.
These factors can reinforce one another. Lower margins encourage production cuts, while reduced production changes feedstock demand and regional trade flows.
Lighter Feedstocks Gain Attention as Margins Tighten
The shift toward lighter feedstocks represents one of the most important responses to the current margin environment. Crackers can use different feedstock strategies depending on their technology, configuration and local economics.
Lighter feedstocks can offer advantages in certain operating conditions because they can provide attractive yields of valuable olefins. Their relative economics therefore become increasingly important when naphtha-based cracking margins deteriorate.
For producers, feedstock flexibility can become a competitive tool. A cracker that can adjust its feedstock mix has more options when market conditions change.
For traders, the shift creates a corresponding change in demand signals. A reduction in naphtha consumption from crackers can affect cargo requirements and potentially alter trade opportunities between producing and consuming regions.
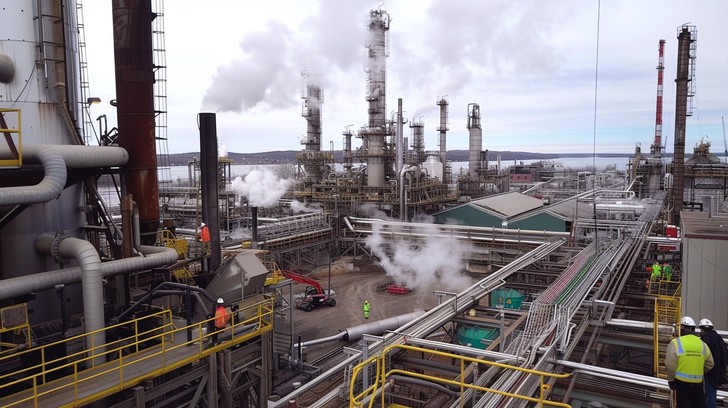
What Lower Cracker Rates Mean for Naphtha Buyers
Naphtha procurement teams need to monitor both physical availability and changes in cracker buying behaviour. A reduction in cracker operating rates can alter the timing, volume and specifications of feedstock purchases.
Buyers should pay close attention to how individual producers adjust their operating strategies rather than assuming that the entire Asian market will respond uniformly.
Several procurement considerations become more important in this environment:
Feedstock flexibility: Buyers should understand whether alternative feedstocks can economically replace part of their naphtha requirements.
Cargo timing: Changes in cracker utilisation can influence when producers enter the spot market for additional cargoes.
Regional balances: Local supply conditions can differ significantly from broader Asian market trends.
Contract exposure: Long-term purchasing commitments require careful assessment when operating rates remain volatile.
Quality requirements: Feedstock substitution does not eliminate the need to match specifications with individual cracker configurations.
These considerations can help procurement teams respond to changing market conditions without relying on a single price indicator.
Asian Petrochemical Capacity Expansion Keeps Pressure High
Capacity expansion remains a major factor behind the current oversupply environment. New petrochemical facilities can add substantial production capability, but downstream demand may take longer to develop.
This creates a period where producers compete aggressively for available customers. The resulting pressure can spread across multiple products and feedstocks rather than remaining limited to one part of the value chain.
For naphtha traders, this means monitoring capacity additions is increasingly important. A new cracker does not simply represent additional production. It can also introduce a new source of feedstock demand and alter regional trade balances.
At the same time, when existing crackers reduce operating rates, some of that additional demand can be offset. The net effect depends on how quickly new capacity ramps up and how strongly downstream consumption develops.
How Traders Can Read the Changing Naphtha Market
The relationship between cracker utilisation and naphtha demand gives traders an important signal for assessing market conditions. Falling operating rates can indicate that producers are becoming more selective about feedstock purchases.
However, operating rates should be considered alongside other market factors. Freight economics, refinery production, regional inventories and alternative feedstock pricing can all influence the attractiveness of naphtha cargoes.
A practical monitoring framework should include:
New Asian cracker capacity and commissioning schedules
Announced or observed changes in cracker operating rates
Relative economics between naphtha and lighter feedstocks
Refinery output and naphtha availability
Olefin demand across major downstream industries
Regional import and export requirements
This broader view can provide a clearer picture than tracking any single market variable.
Supply Chain Strategies for a Volatile Feedstock Market
Procurement teams operating in a pressured market need flexibility without compromising supply security. The current environment makes it important to balance cost management with reliable access to suitable feedstock.
Contract structures can play an important role. Buyers may review delivery schedules, pricing mechanisms and volume commitments to ensure purchasing arrangements remain aligned with changing operating requirements.
Supplier diversification can also reduce exposure to individual supply disruptions. Maintaining relationships across different trading routes can provide additional options when regional availability changes.
Feedstock flexibility is particularly valuable when margins remain compressed. Producers with more sourcing options can respond faster when the relative economics of naphtha and alternative feedstocks shift.
What the Margin Pressure Means for 2027
The direction of the Asian naphtha cracker market will depend heavily on the balance between capacity growth and downstream demand. If additional production continues to arrive faster than consumption expands, margin pressure can remain a major issue for producers.
A stronger recovery in petrochemical demand could improve utilisation and support renewed feedstock purchasing. Conversely, continued oversupply could encourage further production discipline and greater reliance on lighter feedstocks.
For traders, the key issue is not simply whether naphtha demand rises or falls. The more important question is how quickly cracker economics change relative to alternative feedstock options.
This makes operating rates, capacity additions and downstream demand important indicators to monitor through the next market cycle.
What Buyers Should Do Now
Chemical procurement teams should treat the current Asian cracker environment as a signal to strengthen market monitoring and sourcing flexibility. Lower operating rates can create changing purchase requirements while global oversupply continues to influence producer economics.
Buyers can focus on several practical actions:
Monitor cracker operating rates alongside naphtha pricing rather than evaluating feedstock prices in isolation.
Track new capacity additions to identify potential changes in regional supply and demand.
Compare naphtha economics with available lighter feedstock alternatives.
Maintain multiple qualified supplier relationships where possible.
Review contract volumes and delivery schedules against expected production requirements.
Follow downstream olefin demand because stronger consumption can change cracker economics quickly.
For chemical traders, the changing feedstock strategy also creates opportunities to identify new trade flows. Understanding which producers are reducing naphtha consumption and which facilities retain strong feedstock demand can help inform sourcing discussions.
The Asian cracker market is therefore becoming increasingly dependent on flexibility. Producers are adjusting operations as oversupply weighs on margins, while procurement teams must adapt to changing feedstock requirements and regional trade patterns.
The next phase of the market will depend on the interaction between new capacity, downstream demand and relative feedstock economics.
Methanol
Found this useful?