Chemical Price Volatility: The Impact of Energy Costs and Raw Material Shortages
Chemical Price Volatility: The Impact of Energy Costs and Raw Material Shortages
The Current Volatility Landscape
Globally, raw material prices are facing greater uncertainty after seeing period of relative stability following supply chain constraints, shortages, and inflation pressures in 2021 and 2022. For 2024 and 2025, dominant theme has been trend of moderating inflation and continued growth. While extreme price spikes of previous years have largely subsided for input costs, overall cost basis for adhesive and sealant formulators remains elevated compared to pre-pandemic levels. Energy prices, a key cost driver, remain structural.
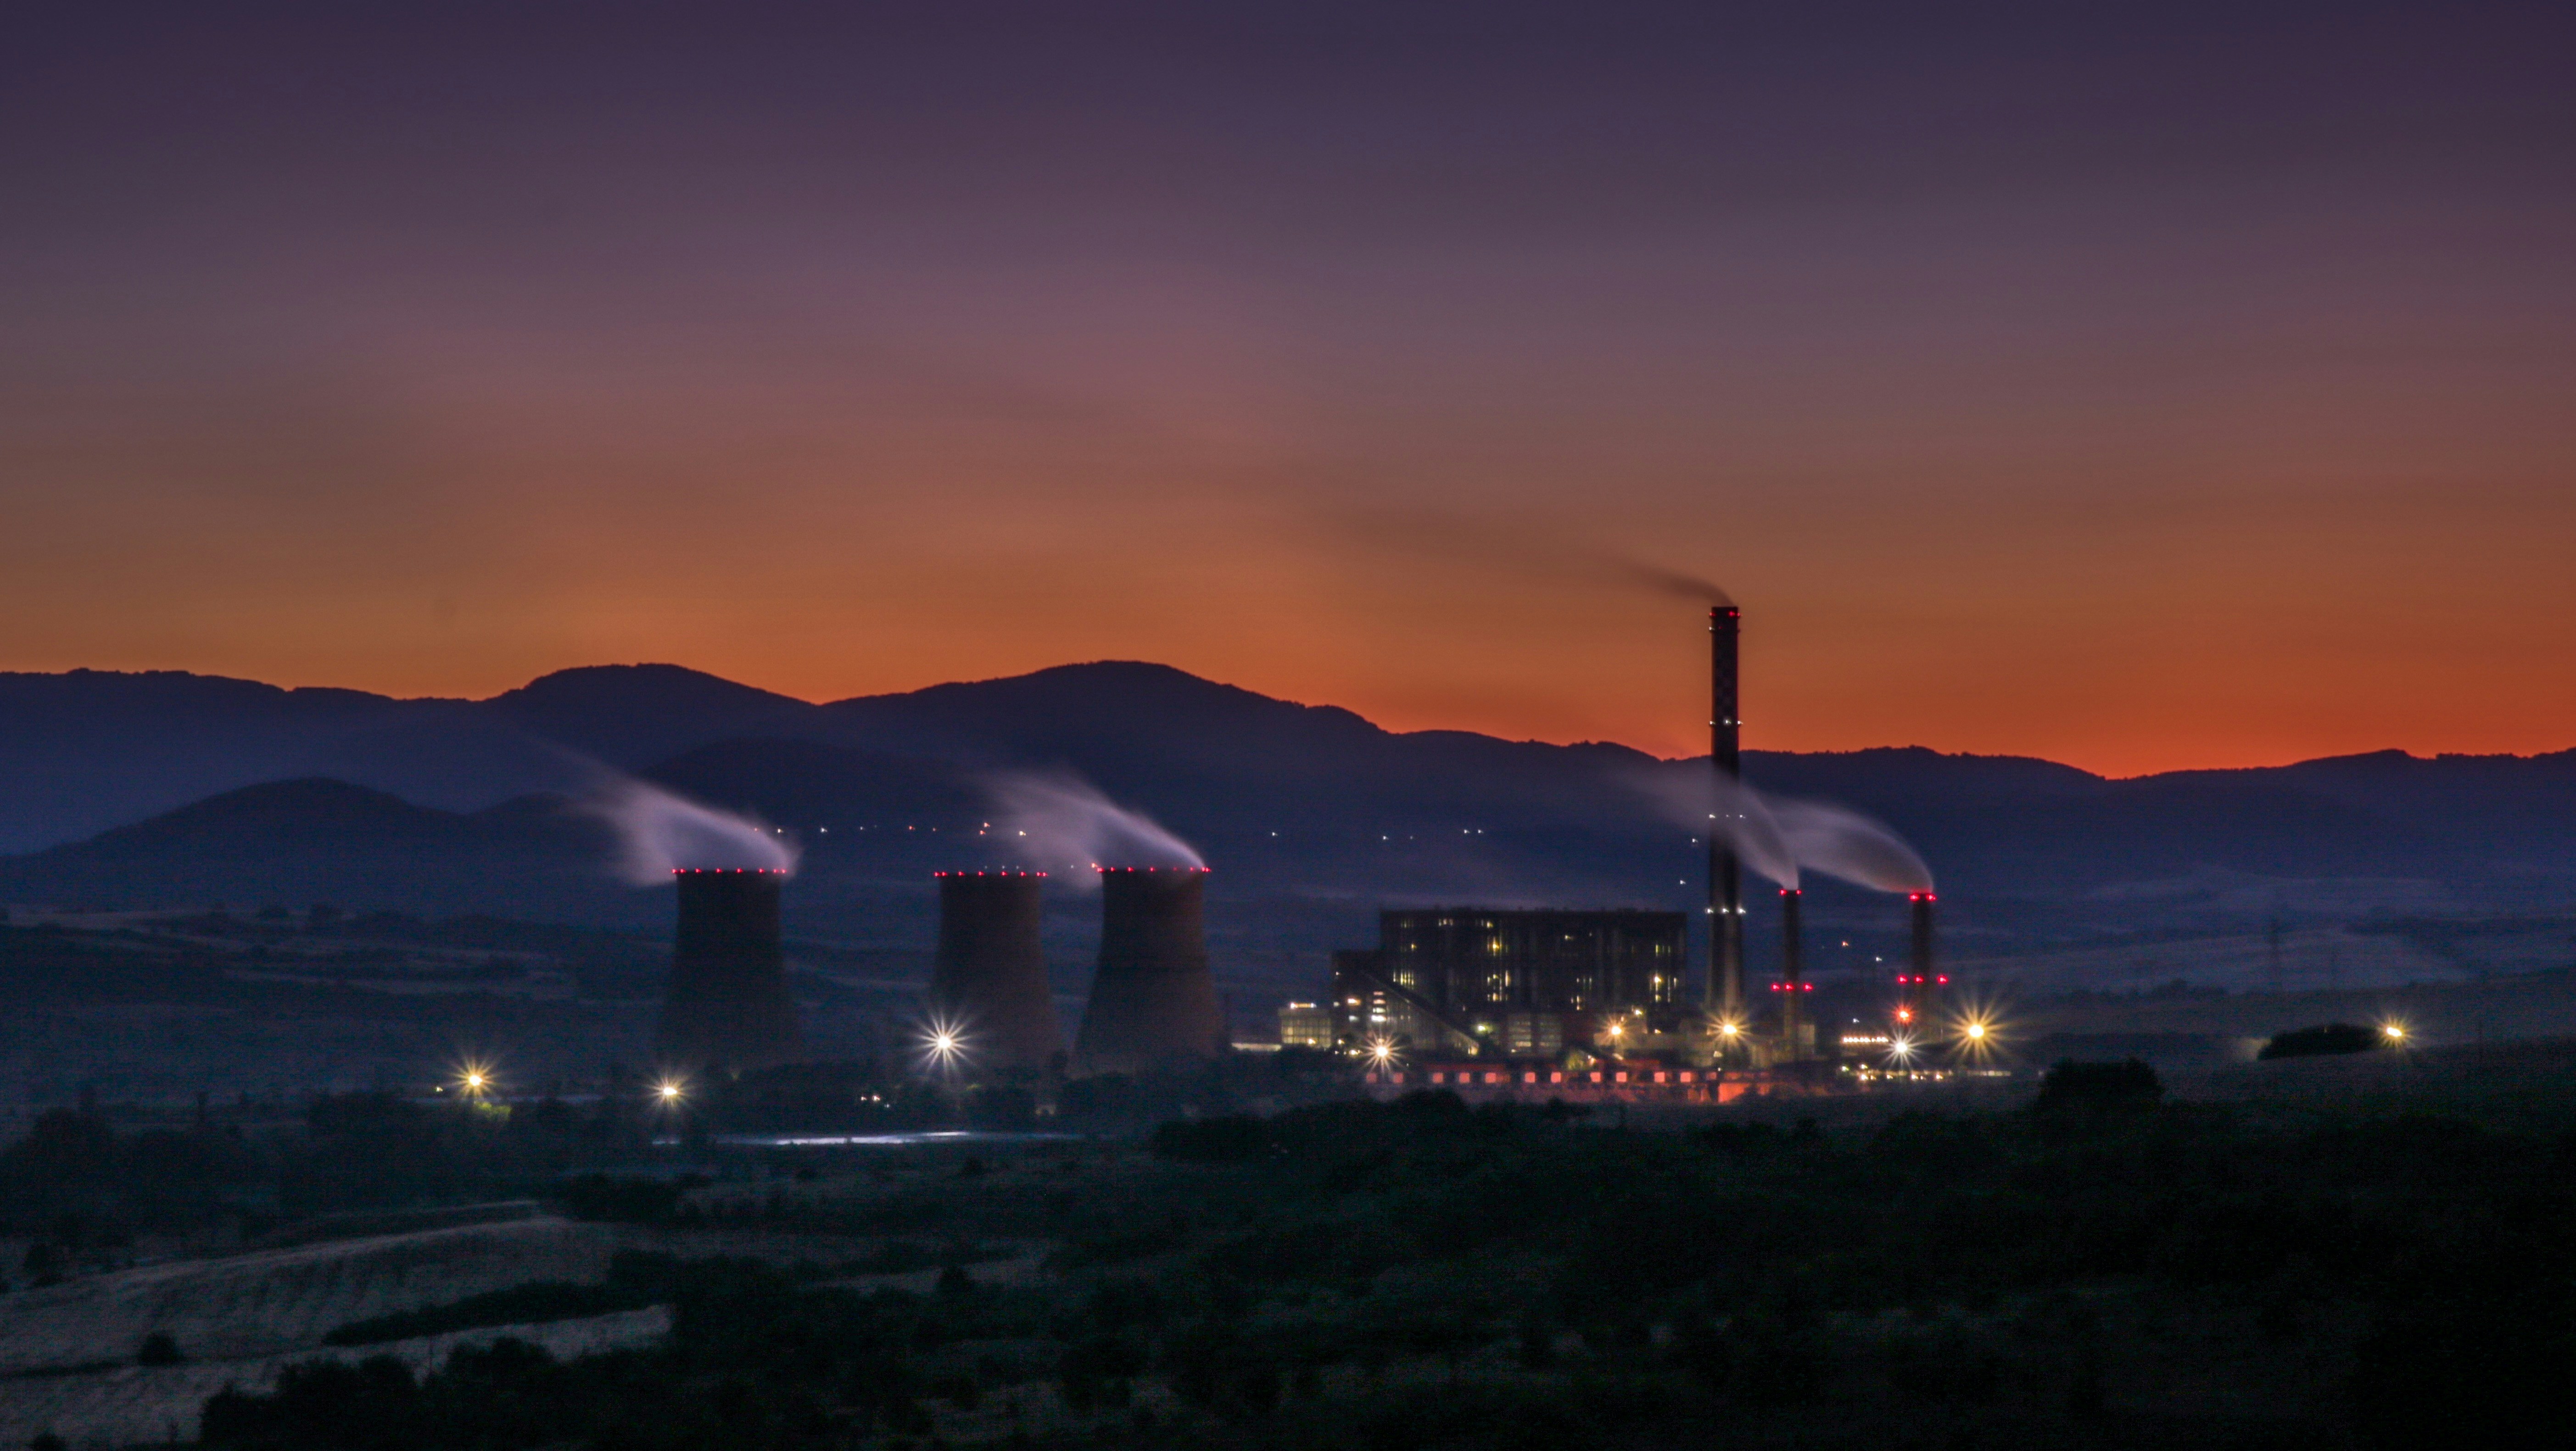
Energy price volatility shot up 82% since late 2021 because of Ukraine conflict, forcing total rethink of risk for any energy-intensive sector. Supply chain chaos, especially for critical minerals and food from Black Sea, has pushed raw material costs for European manufacturers up by average 25%.
Following period of high price volatility driven by increased supply chain disruption and volatility in energy prices, among other factors, materials revenues slightly contracted in 2024 to about $6.7 trillion. Decline primarily result of price adjustments in thermal coal, steel, and battery materials.
For chemical buyers, this means volatility drivers have decoupled – In 2024, 68% of price spikes exceeding 15% over 30 days were triggered by non-market events: unexpected refinery maintenance (often unannounced due to labor shortages), carbon levy recalculations mid-contract, or sudden export restrictions tied to national energy security policies – not inventory drawdowns or OPEC decisions. As result, leading procurement teams shifting from price protection to exposure containment.
How Energy Costs Impact Chemical Pricing
Energy as Structural Cost Layer
Many specialty chemical processes are heat-intensive, batch-dependent, or require controlled temperature and purity conditions. Even where feedstock prices normalize, energy inflation can keep conversion costs elevated, especially in plants with high steam, drying, distillation, or cleanroom requirements. Finance-focused Chemical Forecast should therefore separate raw material trend from conversion trend. Category that appears stable at upstream level can still carry 3% to 8% cost pressure from utilities, wastewater treatment, or low-capacity utilization.
Direct impact: Purchased feedstock and energy costs account for substantial portion of company's total production costs and operating expenses – availability of purchased feedstock and energy, and volatility of these costs, impact operating costs and add variability to earnings – Dow Chemical 10-K disclosure
Manufacturing expenses increased substantially: Companies report raw material costs rose by average 8.3% compared to Q4 2024 – Energy expenditures also increased by approximately 6.7%, with natural gas prices being particularly volatile – Regulatory compliance costs represent another significant expense, adding approximately $1.2 billion in industry-wide costs during Q1 2025
Electricity, steam, gas: Drying of minerals (calcium carbonate, zinc sulfate), calcination, spray drying of vitamins, extrusion of fortified rice kernels – all energy intensive – energy and utilities impact window 1–3 quarters – Raises baseline manufacturing cost even when raw materials soften
Logistics energy: Brent crude surged to $116 per barrel driven by escalating geopolitical threats in Middle East, immediately driving up raw material costs and energy-intensive production expenses across value chains in chemical sector – freight surcharges affect landed cost
Regional Disparities
Europe: Natural gas price volatility highest – coal exporters forced to look for new markets, which could lead to oversupply and downward pressure on raw material prices – For European consumers, this could mean temporary price advantages, but longer term, volatility in coal market could result in higher energy costs, especially in countries that still rely on burning it for power generation and heavy industry
Asia: Coal and LNG price linkages affect Chinese food-grade mineral producers – electricity rationing in provinces can shut plants
US: Shale gas advantage moderates but regulatory compliance costs rising
How Raw Material Shortages Impact Chemical Pricing
Feedstock Volatility – Short Cycle Disruption
Feedstock volatility 2–8 weeks – Requires faster price review cycles and updated margin sensitivity analysis – Not all specialty chemical categories react at same speed – Solvent-based formulations may reprice within 30 to 60 days, while additives, resins, performance coatings, or electronic chemicals may carry delayed adjustments due to inventory buffers or annual agreements – For finance decision-makers, key issue is pass-through timing – If suppliers update pricing monthly but customer contracts reset quarterly, temporary mismatch can compress gross margin by 2 to 4 points.
Mineral feedstocks: Zinc sulfate depends on zinc oxide + sulfuric acid – sulfuric acid price tied to smelter output and energy – Ferrous fumarate depends on ferrous sulfate (steel pickling byproduct) and fumaric acid – steel production cuts reduce ferrous sulfate availability
Vitamin feedstocks: Vitamin D3 from cholesterol/lanolin – cholesterol supply from wool grease affected by textile demand – Vitamin B12 fermentation needs sugar, cobalt – sugar price volatility
Folic acid, niacinamide: Petrochemical derived – pyridine, phenol price swings
Supply-side pressures driving market expansion, with global specialty chemical production capacity rising 5.2% in 2025, optimizing costs and product availability – Petrochemical feedstock price volatility, up ∼8% in early 2026, has prompted cost-pass-through strategies
Non-Market Triggers
Why raw material cost fluctuations are becoming harder to predict – Energy price volatility raises smelting, curing, molding, and logistics costs across metals, rubber, and polymers.
Export restrictions: China export controls on certain minerals, India restrictions on rice bran (source of ferrous sulfate)
Refinery maintenance: Unexpected – 68% spikes triggered by non-market events – often unannounced due to labor shortages
Carbon levies: Carbon levy recalculations mid-contract – EU CBAM adding cost to imported chemicals
Climate events: Drought affects corn (source of citric acid, starch), floods affect mining of calcium carbonate
Consequences for Fortified Food and Mineral Premix Supply Chain
Cost pressure: For finance teams approving contracts, specialty chemicals no longer line item that can be reviewed only on unit price – In many categories, 5% to 12% movement in input cost can materially alter finished-goods margins, working capital requirements, and inventory exposure within single quarter – 3% to 8% cost pressure from utilities even when feedstock stable
Lead-time extension: Has delivery shifted from 2–3 weeks to 5–7 weeks, forcing higher buffer inventory? – Supplier capacity discipline – Are suppliers limiting spot volume, increasing MOQ, or reducing flexibility on payment terms?
Compliance friction: Additional declarations, testing batches, import checks slowing execution – Environmental reporting, product stewardship, restricted-substance screening, export documentation now influence both administrative cost and lead time – supplier qualification may take 6 to 16 weeks, reducing buyer flexibility during sudden escalation
Quality risk: When raw materials scarce, suppliers may substitute lower-grade feedstock – need stricter incoming QC for heavy metals, assay
Strategies for Containment – Moving from Price Protection to Exposure Containment
Leading procurement teams shifting from price protection to exposure containment.
1. Separate Raw Material Trend from Conversion Trend
Track feedstock index (e.g., zinc LME, sulfur) separately from energy index (natural gas TTF, electricity) – If feedstock down but energy up, conversion cost still elevated – do not expect full price drop
Finance-focused Chemical Forecast should separate raw material trend from conversion trend
2. Tiered Budgeting Instead of One-Point Assumptions
For exposed categories, single annual price assumption often too fragile – Better method build three planning bands: base case, pressure case, disruption case – Even 3-band model can improve quarterly decision speed and reduce approval bottlenecks – Example specialty resin budget may allow 0% to 3% movement in base case, 4% to 8% in pressure case, above 8% only with executive review plus supply continuity justification.
Base: Current price + 3% energy escalation
Pressure: +8% raw material + energy
Disruption: +15% with lead time extension 2x
3. Align Contract Terms with Cost Reality
When market conditions unstable, annual fixed pricing may appear attractive but can fail if suppliers withdraw flexibility elsewhere – In some cases, indexed or semi-open pricing with 30-day review mechanism offers better predictability than rigid quote that later triggers emergency renegotiation.
Indexed pricing: Link zinc sulfate price to zinc LME + conversion fee – fair to both sides – avoids sudden withdrawal
Surcharges: Agree energy surcharge trigger (e.g., if natural gas >€40/MWh, +2% surcharge) – transparent
MOQ and lot size: Financial approvers should test terms such as MOQ, delivery lot size, surcharge triggers, payment days – 2% price concession may be outweighed by 40% increase in inventory holding if batch size requirements expand sharply
4. Focus on Four Decision Signals
Most practical model uses four signals: input trend, lead-time movement, supplier capacity discipline, and compliance friction – When three of four move same direction for 6 to 8 weeks, probability of sustained price pressure rises materially.
Input trend: Are upstream solvents, monomers, specialty intermediates rising faster than current contract assumptions?
Lead-time movement: Has delivery shifted forcing higher buffer?
Capacity discipline: Suppliers limiting spot volume, increasing MOQ?
Compliance friction: Additional declarations slowing execution?
Suppliers rarely communicate price risk in purely financial terms – Instead they may mention allocation, maintenance shutdowns, packaging shortages, revised surcharges, or slower confirmation windows – Each early Chemical Forecast signal – Example if supplier shortens quotation validity from 30 days to 7 days, indicates uncertainty
5. Sourcing Structure
Dual sourcing: Critical items with long qualification cycles, strict specifications, or high supply risk should be sourced with strong emphasis on continuity – Less critical items with broad supplier availability can be managed more aggressively for price competition – For food-grade fortificants, qualify 2 suppliers for each critical nutrient
Geographic diversification: Source from multiple regions to mitigate energy cost disparity – e.g., calcium carbonate from local GCC (low energy transport) vs imported PCC (high energy)
Safety stock linked to cash: Link safety-stock decisions to cash cost and customer service risk – For chemicals with 8-week-plus qualification cycles, pre-approve alternate suppliers
6. Practical Controls for Finance-Led Sourcing
Set category review frequency at every 30, 60, or 90 days based on volatility
Separate strategic chemicals from substitutable items in approval workflow
Require landed-cost comparison, not ex-works price only
Link safety-stock decisions to cash cost and customer service risk
Pre-approve alternate suppliers for categories with 8-week-plus qualification cycles
Bottom Line
Chemical price volatility driven by energy price volatility up 82% since late 2021 and raw material shortages triggered by non-market events 68% of spikes – Energy and utilities raises baseline manufacturing cost even when raw materials soften – Feedstock volatility requires faster price review cycles – Production costs continue to rise – raw material costs rose average 8.3%, energy 6.7% – Manufacturing expenses increased substantially – Companies that master seasonal sourcing, tiered budgeting, indexed contracting, and exposure containment ensure they thrive regardless of market conditions, transforming procurement from cost management function into value creation engine.
For buyers of food-grade minerals and vitamins, tracking energy separately from feedstock, building 3-band budgets, and securing qualified secondary sources is more effective than chasing lowest spot price.
Working Source Links:
2025 Raw Materials and Chemicals Overview – Globally raw material prices facing greater uncertainty – moderating inflation and continued growth – extreme price spikes largely subsided but overall cost basis remains elevated – Energy prices a – https://adhesivesmag.com / chemquest.com
Ukraine War: 82% Energy Price Volatility – Energy price volatility shot up 82% since late 2021 because of Ukraine conflict – Supply chain chaos for critical minerals pushed raw material costs up 25% – https://globalinsightwire.com
Chemical Forecast: Specialty Chemical Cost Pressure – Feedstock exposure no longer uniform – Energy and utilities remain structural cost layer – Many specialty chemical processes heat-intensive – Even where feedstock prices normalize energy inflation can keep conversion costs elevated – https://hgiron.com
Diethyl Sulfate
Found this useful?