US Gulf Coast Ethane Advantage Widens as Oil-Linked Feedstocks Rise
US Gulf Coast Ethane Advantage Widens as Oil-Linked Feedstocks Rise
The return of Brent crude above $100 a barrel has widened the feedstock cost gap between US Gulf Coast ethane-based steam crackers and naphtha-based competitors in Asia and Europe. Ethane prices are linked to natural-gas liquids fundamentals and domestic gas-processing economics, not to crude oil. When oil-linked naphtha costs rise sharply, the cash-cost advantage of ethane cracking expands, improving relative margins for Gulf Coast producers and strengthening their position in global ethylene and derivative markets. The effect is one of the clearest illustrations of how North American shale-driven NGL abundance continues to shape petrochemical competitiveness even in a high-oil-price environment.
US Gulf Coast crackers that run primarily on ethane, or that can maximise ethane in a flexible slate, therefore operate with a structural buffer that naphtha-dependent regions lack. The buffer does not eliminate all margin pressure—derivative prices, operating costs and logistics still matter—but it materially cushions the impact of an oil-driven feedstock spike.
Ethane versus Naphtha Cost Dynamics
Naphtha prices move with crude. A sustained move to $100 Brent lifts CFR Asia and European naphtha quotations, raising the variable cost of every tonne of ethylene produced from that feedstock. Ethane, by contrast, is priced in the US gas-liquids complex. Its absolute price can rise with stronger demand or tighter supply, yet the driver set is different and the correlation with Brent is far weaker. When oil jumps on geopolitical risk while US gas and NGL markets remain better supplied, the ethane–naphtha spread widens in favour of ethane.
Co-product credits differ as well. Naphtha cracking yields a richer slate of propylene, butadiene and aromatics; ethane cracking is ethylene-heavy. In periods of strong co-product values the naphtha disadvantage is partially offset. When co-product markets are soft, the pure ethylene cost advantage of ethane becomes even more pronounced.
Margin and Operating-Rate Implications
Higher relative margins support higher operating rates on the US Gulf Coast at the same time that Asian and European naphtha crackers may be cutting rates to protect cash margins. The divergence can tighten global ethylene balances less than a uniform global cost shock would, because advantaged capacity continues to run. It also influences trade flows: US ethylene derivatives become more competitive in export markets, while import demand into the United States for certain olefins or polymers may ease.
Flexible Gulf Coast crackers that can swing between ethane and heavier feeds optimise toward ethane when the oil-linked alternative becomes expensive. The ability to make that shift is itself a competitive asset that pure naphtha operators cannot replicate.
Downstream and Export Consequences
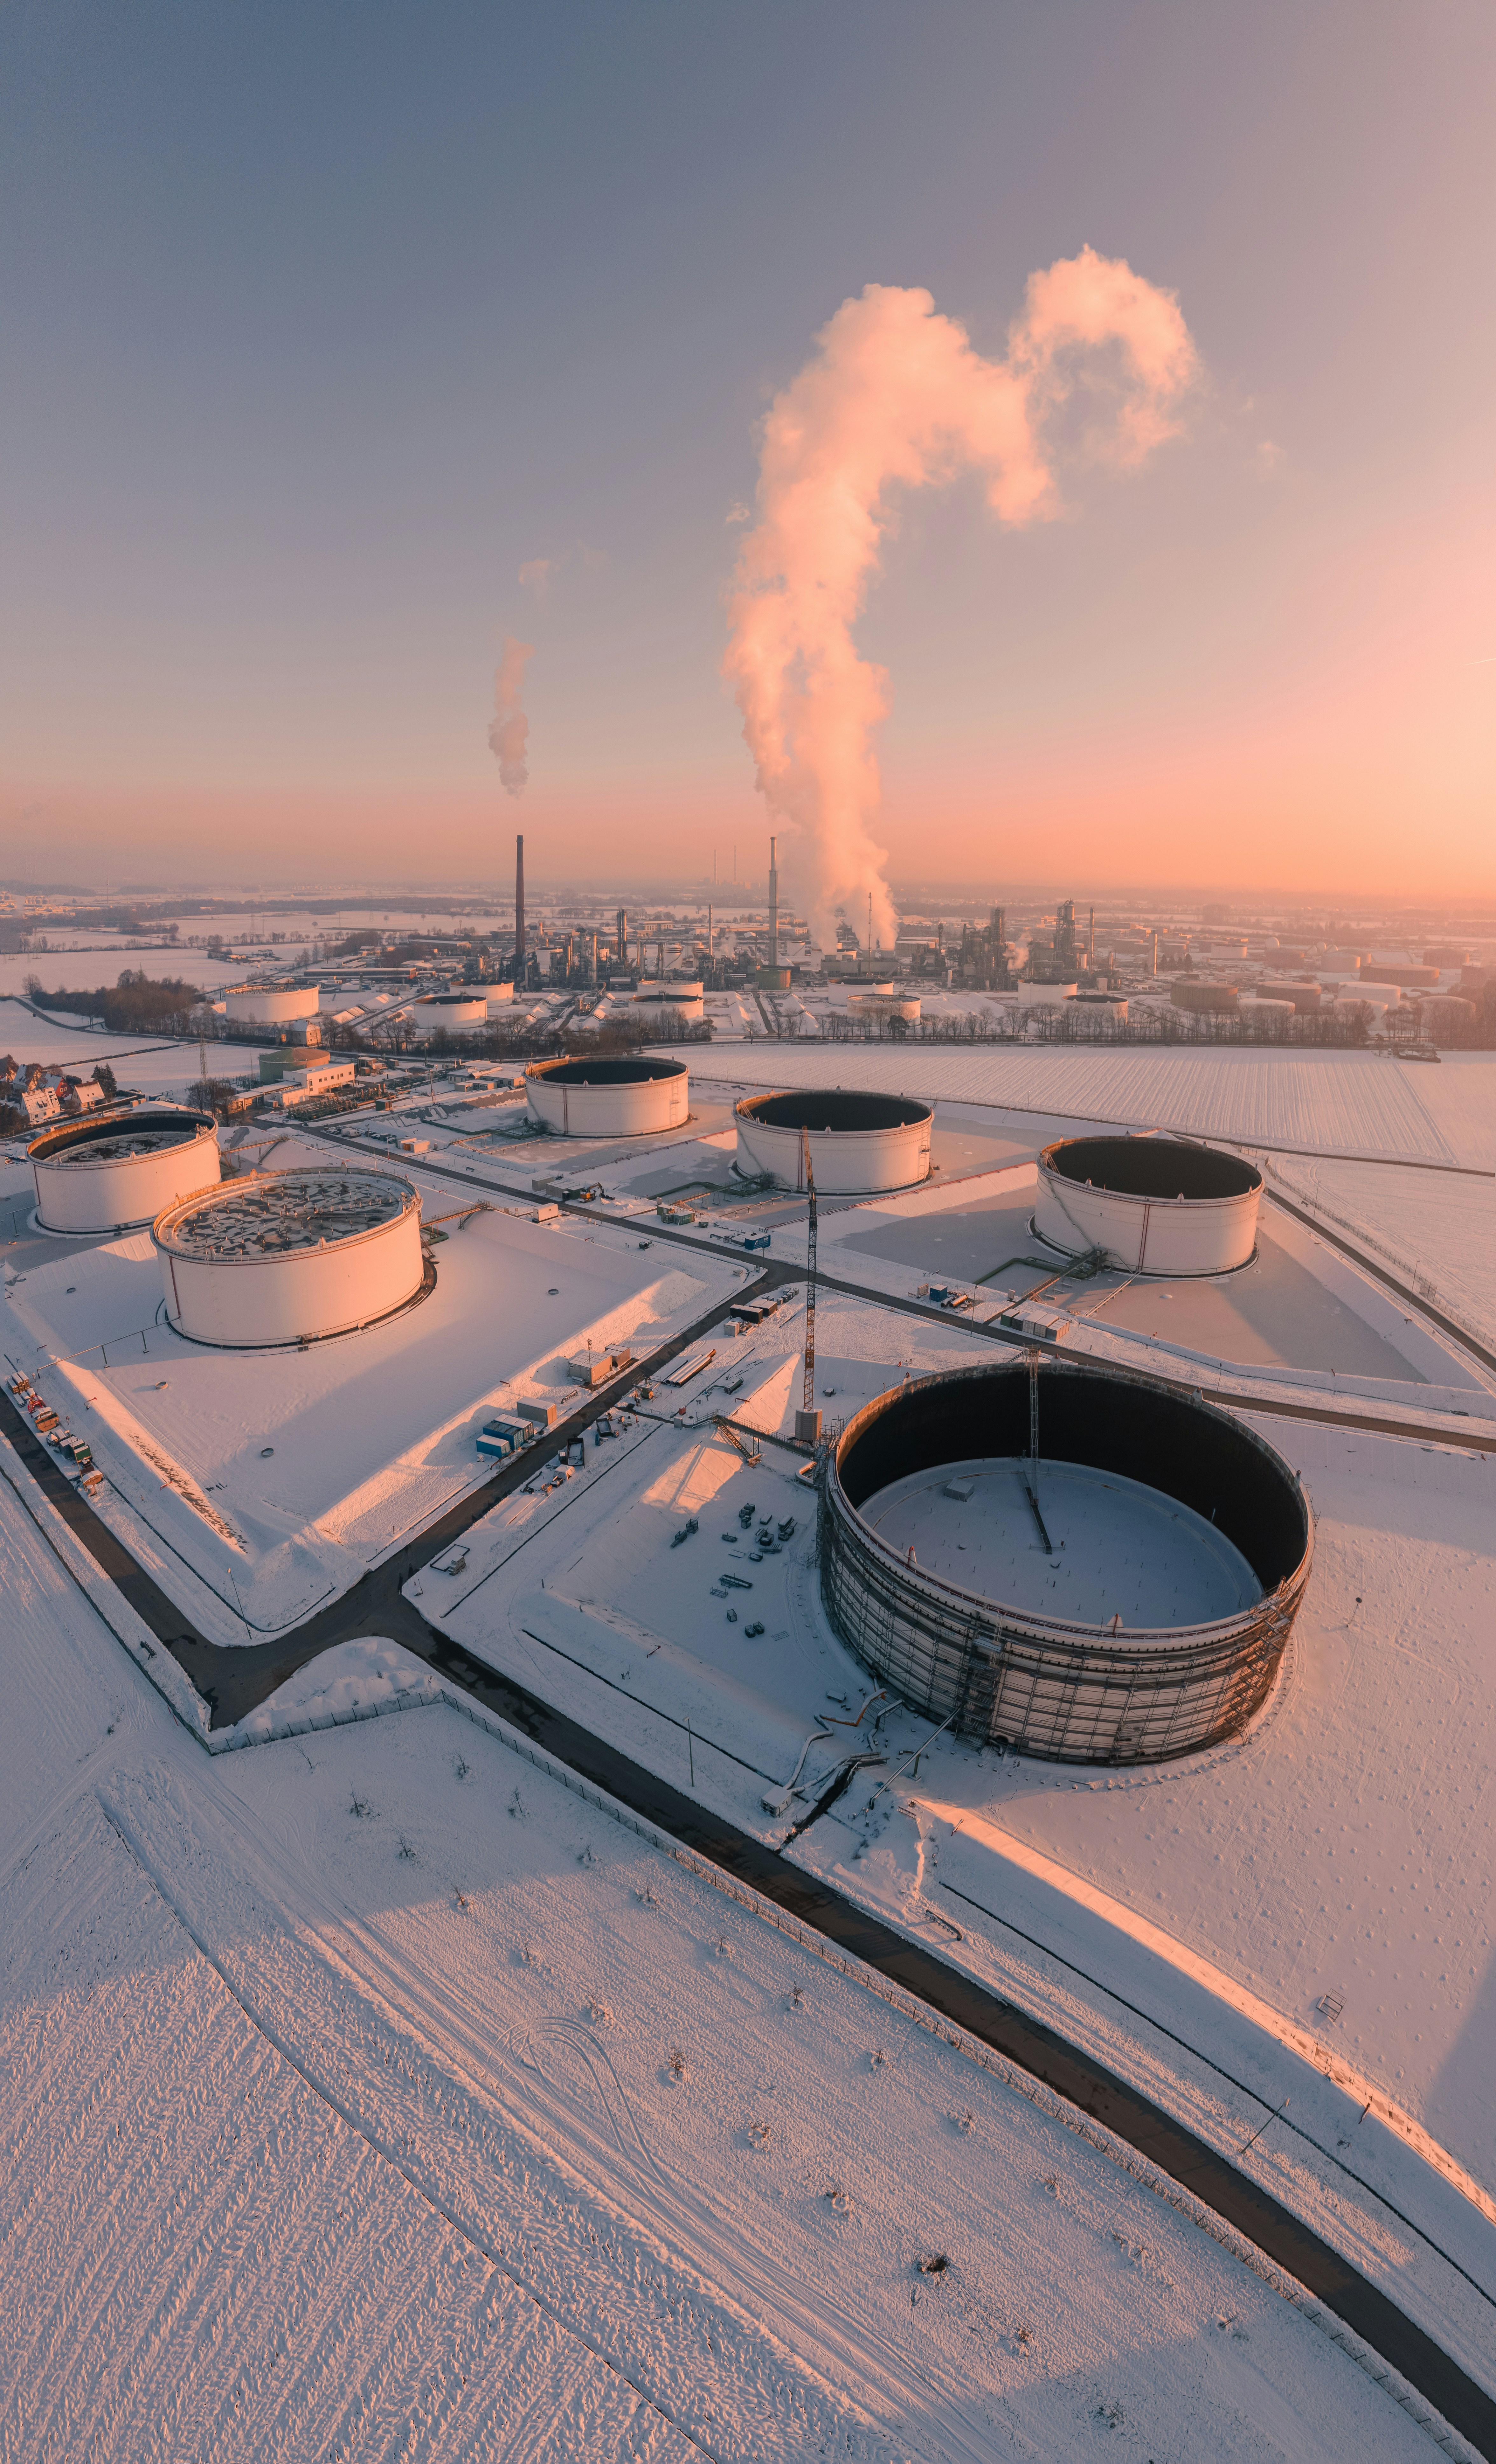
The widened ethane advantage feeds through into polyethylene, ethylene glycol, styrene and other derivatives. US producers gain room to compete on price in Atlantic and Pacific export markets or to protect margins while still moving volume. Asian and European derivative producers face the opposite pressure: higher feedstock costs and, potentially, greater competition from US-origin material. The net result is a redistribution of margin and market share toward regions with non-oil-linked feedstocks.
Ethane exports from the US Gulf Coast themselves remain part of the picture. Growing export capacity allows overseas crackers to access US ethane, partially transferring the advantage abroad. Even so, the logistics cost and the sunk investment in ethane-capable crackers mean that the largest and most immediate benefit remains on the Gulf Coast itself.
Structural Nature of the Advantage
The ethane edge is not a temporary artefact of one oil-price spike. It rests on the continued availability of NGLs from US shale production, the build-out of fractionation, storage and cracker capacity on the Gulf Coast, and the comparatively limited linkage between domestic gas-liquids pricing and global crude. As long as those conditions hold, episodes of high oil prices will repeatedly widen the gap in favour of ethane. Conversely, periods of very low oil prices or tight US NGL balances can narrow it. The long-term direction of travel, however, has been toward a persistent US feedstock advantage in ethylene.
Outlook
US Gulf Coast ethane-based petrochemical production has seen its cost advantage widen as oil-linked feedstocks rise with $100 Brent. Naphtha crackers in Asia and Europe absorb the full force of the oil move; ethane crackers do not. The resulting margin differential supports higher relative operating rates, stronger export competitiveness and a continued shift in global olefin market share toward advantaged US capacity. Until oil prices retreat or US ethane fundamentals tighten materially, the Gulf Coast’s structural edge remains reinforced by every upward move in the crude market.
Sources
Alkalized Reddish Brown Cocoa Powder
Found this useful?