Wood Mackenzie's Permanent Plant Closure Warning: Which Chemical Plants May Never Restart and What Buyers Should Do
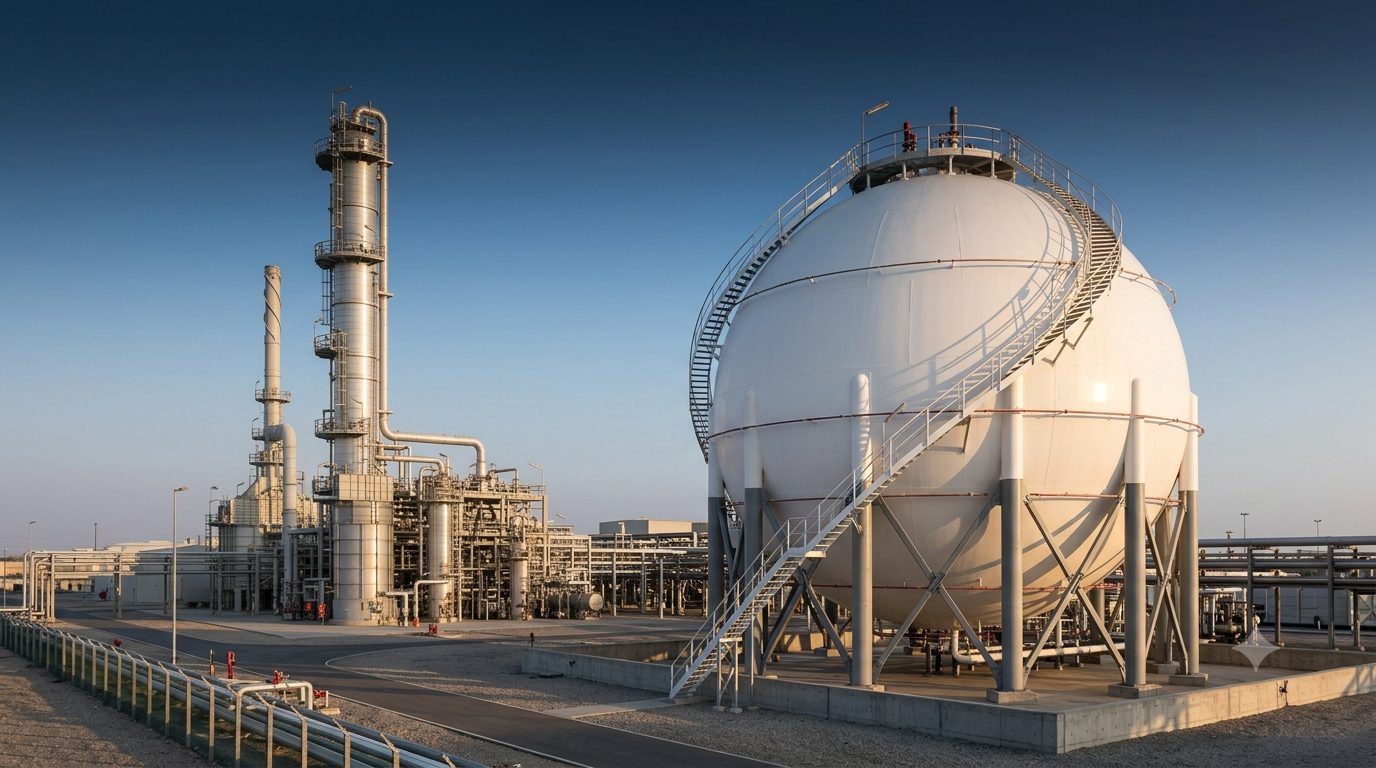
The latest warning from Wood Mackenzie has shifted attention away from short term supply disruption and toward a much larger structural issue. According to the firm's latest assessment, several chemical plants that stopped operating during the Hormuz crisis may never return to production. For procurement teams, this changes the discussion from temporary shortages to the possibility of a permanently smaller global manufacturing base.
The warning highlights that facilities already struggling with weak margins and poor cash flow since 2022 now face another major shock. Instead of investing capital to restart production, some operators may decide to shut their plants permanently. That decision could reshape supply chains throughout the second half of 2026 and beyond, making supplier diversification more important than ever.
Why Wood Mackenzie's Warning Matters Beyond the Hormuz Crisis
Temporary production outages are common in the chemical industry. Plants stop because of maintenance, weather events, feedstock shortages or logistics disruptions, then resume operations once conditions improve.
Wood Mackenzie's latest assessment suggests that this cycle may not apply to every facility affected by the Hormuz crisis. Plants that have struggled financially for several years could see the disruption as the final reason to exit the market instead of restarting production.
This distinction matters because buyers often assume lost production capacity will eventually return. If multiple producers permanently close facilities, global supply becomes structurally tighter even after shipping routes and feedstock availability improve.
Several market conditions have increased this risk.
High energy costs have reduced profitability for many producers, particularly in regions where manufacturing expenses remain significantly above global averages.
Weak operating margins since 2022 have limited investment in maintenance, efficiency upgrades and equipment modernization.
Continued market uncertainty has made it difficult for companies to justify restarting facilities that were already operating below economic levels.
Rather than representing an isolated event, the Hormuz disruption may accelerate decisions that many companies had already been considering.
Which Chemical Plants Face the Highest Permanent Closure Risk?
Not every idle facility faces permanent shutdown. Plants with competitive production costs, reliable feedstock access and strong customer demand will likely return once market conditions stabilize.
Facilities facing several challenges simultaneously carry a much greater risk.
Common characteristics include:
Older production assets that require significant capital investment before restarting operations.
Plants dependent on expensive imported feedstocks instead of locally available raw materials.
Facilities that have experienced repeated shutdowns or low operating rates over recent years.
Manufacturing sites with consistently weak profitability since 2022.
Producers competing against newer, larger and more efficient complexes in the Middle East and Asia.
Companies often evaluate these factors together. When restarting a plant requires substantial investment with uncertain returns, permanent closure becomes a financially attractive option.
For procurement professionals, this means supplier evaluation should extend beyond delivery schedules and current inventory levels. The financial strength and long term competitiveness of production assets deserve equal attention.
How Permanent Closures Could Reshape Global Chemical Supply
The chemical market regularly adjusts production levels in response to changing demand. Permanent closures create a different situation because manufacturing capacity disappears rather than temporarily pausing.
Wood Mackenzie suggests the current disruption could compress several years of supply rationalization into only a few months. If that occurs, buyers may enter a market with fewer production sites and less flexibility to respond when demand strengthens.
The consequences could include:
Reduced supplier competition across several commodity chemicals.
Longer lead times as remaining producers receive higher order volumes.
Less regional diversity, increasing dependence on a smaller number of manufacturing hubs.
Greater exposure to future geopolitical disruptions because fewer alternative production sites remain available.
Faster price increases when demand recovers and available inventories begin to decline.
These changes would not affect every chemical equally. Products with already concentrated production bases may experience stronger supply pressure than widely manufactured commodity materials.
The COVID-19 Comparison and What It Means for Procurement
Wood Mackenzie compares the current market situation with what occurred during the COVID-19 period. At that time, several refinery and chemical facilities in Europe and North America shut down during periods of exceptionally weak demand.
Many market participants initially viewed those shutdowns as temporary. Instead, a significant number never resumed production because operators concluded that future profitability no longer justified additional investment.
The current environment presents a similar pattern. External disruption has arrived at a time when many facilities already faced financial pressure.
For procurement teams, this comparison offers an important lesson. Waiting for every supplier to resume production may not be a realistic strategy if some assets permanently leave the market.
Supply Chain Risks That Could Extend Beyond 2026
A permanent reduction in production capacity creates challenges that extend well beyond the immediate disruption. Even if shipping lanes, feedstock availability and energy markets stabilize, fewer operating plants mean the industry has less flexibility to absorb unexpected demand or future supply interruptions.
Buyers should also remember that production capacity cannot be replaced overnight. Building a new petrochemical complex requires years of planning, regulatory approvals and significant capital investment. Once older facilities leave the market, replacing that output becomes a long term process rather than a quick solution.
Several risks deserve close attention over the coming months.
Greater supplier concentration. As weaker producers exit the market, purchasing options narrow and buyers become more dependent on a smaller group of global manufacturers.
Longer procurement cycles. Remaining plants may operate at higher utilization rates, increasing production schedules and extending delivery times during periods of strong demand.
Higher exposure to regional events. If production becomes concentrated in fewer countries, geopolitical tensions, natural disasters or infrastructure disruptions could have a much larger impact on global supply.
Reduced negotiating leverage. Buyers may find fewer competing offers available, making long term pricing discussions more challenging once inventories tighten.
These developments reinforce the importance of treating supply resilience as a strategic objective rather than simply a purchasing function.
How Buyers Should Evaluate Supplier Exposure
The current market environment requires procurement teams to look beyond contract prices. Understanding where suppliers manufacture products and how resilient those facilities are has become equally important.
A supplier operating several modern plants across different regions generally presents lower operational risk than one relying on a single aging production site. Geographic diversity can reduce the impact of regional disruptions and improve supply continuity.
Procurement managers should review several areas when assessing supplier exposure.
Identify every production site supporting critical chemical purchases rather than relying only on the supplier's headquarters location.
Determine whether those facilities have experienced prolonged shutdowns since 2022 or have been operating below normal capacity.
Assess whether production depends on imported feedstocks that remain vulnerable to logistics disruptions.
Review suppliers' financial strength and investment activity to understand whether facilities continue receiving capital for modernization.
Confirm the availability of backup manufacturing locations in case one production site permanently exits the market.
Building this visibility allows buyers to make informed sourcing decisions before market conditions become more restrictive.
Alternative Sourcing Strategies for a Tighter Market
Supplier diversification has always been a best practice, but current conditions increase its importance. Companies that rely heavily on one producer or one production region face greater operational risk if additional facilities close permanently.
Rather than replacing existing suppliers immediately, many organizations are expanding their approved supplier base to improve flexibility.
Effective sourcing strategies may include:
Qualifying secondary suppliers before urgent demand arises.
Expanding procurement across multiple geographic regions to reduce concentration risk.
Reviewing contract terms to secure dependable supply during periods of market volatility.
Increasing collaboration with suppliers that maintain integrated production and feedstock operations.
Monitoring inventory policies for critical raw materials where replacement options remain limited.
These actions can strengthen business continuity without requiring significant changes to existing procurement programs.
The Bottom Line for Procurement Teams
Wood Mackenzie's warning signals a potential shift from temporary disruption to long term structural change. If financially challenged chemical plants permanently leave the market, buyers may face a supply landscape with fewer producers, less flexibility and stronger pricing pressure once demand recovers.
Organizations that begin evaluating supplier resilience now will be better prepared for that environment. Mapping production assets, qualifying alternative suppliers and monitoring permanent closure risks can reduce future procurement uncertainty while supporting more resilient supply chains.
Ready to source chemical products from verified global suppliers? Explore competitive offers on our platform today.
Styrene Monomer
Found this useful?