Chemical Feedstock Price Trends: Crude Oil, Natural Gas, and Their Impact on Chemical Manufacturing Costs
Chemical Feedstock Price Trends: Crude Oil, Natural Gas, and Their Impact on Chemical Manufacturing Costs
How Crude Oil And Natural Gas Shape Chemical Costs
Chemicals price trends by region in 2026 show feedstock structure affects more than price. It can influence impurity profile, lot consistency, and production flexibility. The main takeaway is that feedstock advantage is real but not permanent.
Chemical manufacturing trends describe structural shifts that change how chemicals are produced, priced, qualified, and delivered. They include feedstock economics, catalyst efficiency, environmental controls. Crude oil, natural gas, and coal still influence many chemical chains. Yet in 2026, conversion efficiency, utility cost, and process yield often determine competitiveness more sharply than raw feedstock benchmarks alone.
Global chemical forecast becomes more specific when feedstock maps differ. Two products may share end markets but react differently because their feedstock maps are different. That also means substitution decisions need updated cost logic. A lower nominal price does not always equal lower total exposure if energy pass-through clauses are aggressive.
North America retains feedstock advantages in parts of petrochemical system, while Asia faces elevated costs.
Crude Oil – Naphtha Route Dominance In Europe And Asia
Naphtha, a primary liquid feedstock used extensively in Europe and Asia, is produced during refining of crude oil. Consequently, when crude oil prices surge due to geopolitical tensions in Middle East or production cuts by OPEC+, naphtha prices rise and push up ethylene and propylene costs.
Oil and petrochemicals monthly report shows naphtha 825 dollars, down 13.2% month on month but up 9.3% year on year, up 38.7% on longer comparison. Propylene-Asia 1060 up 7.1%. When crude oil prices are high relative to natural gas, U.S. petrochemical producers gain massive competitive advantage on global stage, as their feedstock costs remain low while global product prices, set by naphtha-based marginal producers, remain high.
Recent market reports highlight geopolitical risks and global chemical market trends in 2026. Energy prices and freight costs are two key drivers. Energy is fundamental cost component in many chemical production processes. Changes in crude oil, natural gas, and other feedstock prices can influence production economics, although degree of impact varies by product and manufacturing route. For petroleum-based chemicals and solvents, higher feedstock costs may put upward pressure on prices. However, rising costs do not automatically translate into higher selling prices.
Businesses are only able to pass on higher feedstock costs to customers to limited extent, as demand from downstream industries is relatively weak and competition from China is fierce. That limits margin recovery even when crude rises.
Food security risk analysis warns Brent crude oil forecast to average 91 dollars per barrel in 2026, up sharply from 69 dollars in 2025, before easing to 79 dollars in 2027. Crisis in West Asia has dealt massive blow to energy production, with global oil supply projected to fall by 5.2%, 5.5 million barrels per day in 2026, marking largest decline in over four decades outside of 2020 global recession. Liquefied petroleum gas, fuel that feeds plastics manufacturing, chemical production, heating systems, and agricultural operations, has seen shipments stall as Gulf exports collapse. Goldman Sachs identifies LPG as key shortage risk in Q2 2026. Naphtha vanishing from Asian markets, petrochemical plants across Asia shutting down because they cannot afford or obtain feedstock.
Natural Gas – The Differentiator For Competitive Advantage
Natural gas and electricity costs can reset floor price quickly. There natural gas serves as both fuel and feedstock. Natural gas liquids derived from gas production serve as key raw materials for ethylene and propylene production, building blocks of most plastics.
Global chemicals price trends assessment October 2026 published by Grand View Signal details how regional production economics and feedstock availability dictated pricing. In Asia, restricted import arrivals and elevated feedstock costs triggered significant price increases for primary industrial intermediates, while European producers continued to face severe operational pressures due to elevated natural gas expenditures.
EU gas and oil prices are surging, US gas price still low. Polyethylene, polypropylene prices rise with feedstock costs. Chemicals in 2026 prolonged downturn in commodities delays sector recovery, with rising feedstock costs pushing up chemical prices.
Feedstock route table shows how common pathways influence regional chemical pricing patterns in practical sourcing decisions. Ethane cracking in US and Middle East offers low-cost ethylene when natural gas liquids abundant. Naphtha cracking in Europe and Asia faces higher costs when crude is high. That divergence explains why propylene Q2 2026 prices hit 980 dollars MT Germany, 860 Saudi Arabia, 745 China and 590 US amid regional supply divergence.
Natural gas also provides feedstock optionality for chemical operations. Increased natural gas production provides additional feedstock optionality, as seen in Shell's upstream gas operations acquisition.
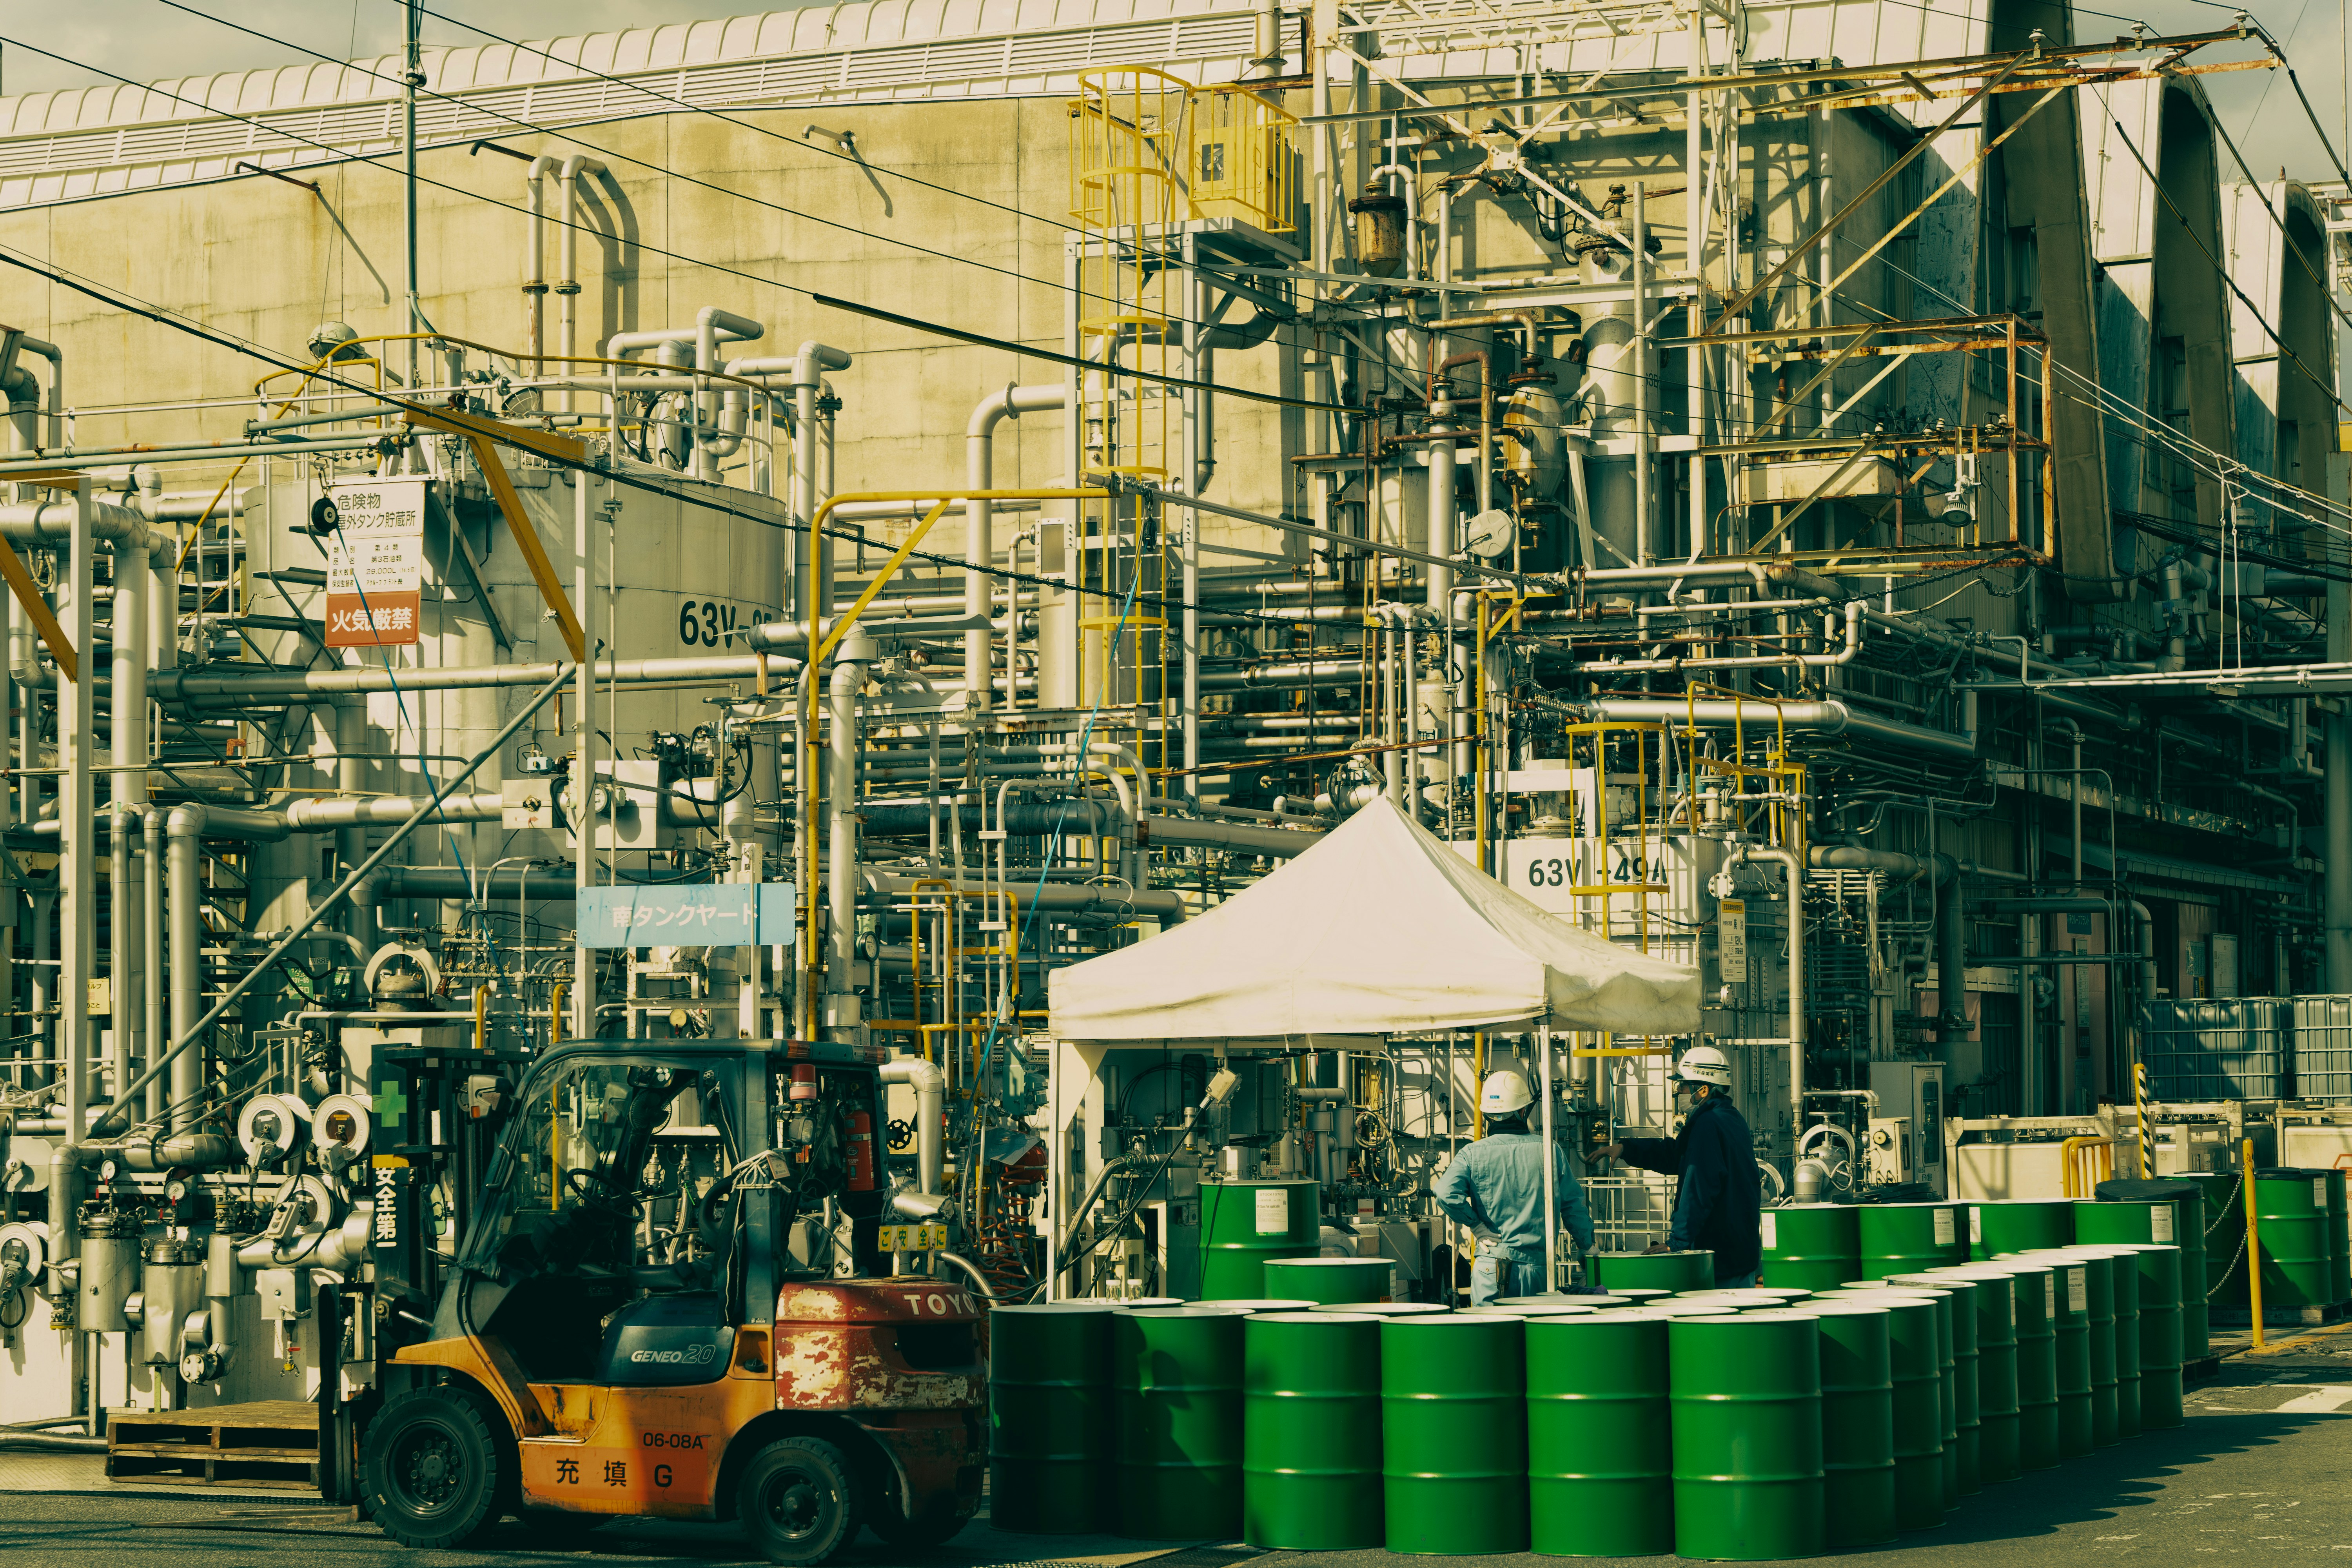
Impact On Chemical Manufacturing Costs
Cost structures are increasingly influenced by raw material prices and energy costs, with margins under pressure in commodity segments. Feedstock structure affects impurity profile, lot consistency, and production flexibility beyond just price.
Manufacturing costs expected to remain elevated through 2027 as supply disruptions, geopolitical conflict and trade barriers offset weaker aggregate demand. Materials price index forecast to decline modestly in 2027 but remain well above 2025 levels.
For food-grade minerals and vitamins, crude oil and natural gas impact is indirect but significant.
For minerals like calcium carbonate GCC, low-energy milling gives advantage over synthetic calcium citrate that requires more chemical processing. Lifecycle assessments show GCC emits 28 to 35% less CO2 per ton. Natural GCC accounts for 72.6% of calcium carbonate market, supported by abundant limestone and low-energy milling. When natural gas prices surge, synthetic grades requiring calcination and precipitation become disproportionately expensive.
For zinc sulfate and ferrous fumarate, sulfuric acid and fumaric acid production are energy intensive. Sulfuric acid from smelters depends on energy for smelting, and fumaric acid from petrochemical route tracks crude. Higher energy costs raise conversion costs by 3% to 8% even when raw material benchmarks soften.
For vitamins, petrochemical feedstock price volatility up around 8% in early 2026 prompted cost-pass-through strategies. Folic acid, niacinamide, riboflavin depend on pyridine and other petrochemical intermediates. When crude rises, vitamin prices follow with 2 to 8 weeks delay. Energy and utilities impact window 1 to 3 quarters raises baseline manufacturing cost.
Regional Production Economics In 2026-2027
Indonesia and Vietnam face similar feedstock exposure but benefit from relatively stronger domestic demand growth. Malaysia is comparatively more resilient due to gas-linked capacity, although downstream derivatives remain exposed to higher input costs. Overall chemicals producers across Southeast Asia face pressure to pass on costs with limited success.
Europe faces severe operational pressures due to elevated natural gas expenditures. High natural gas costs led directly to idling of three acetyls manufacturing units at Hull in UK, halting local acetic acid production. That illustrates Europe's energy-cost disadvantage, forcing reliance on international sourcing.
North America retains feedstock advantage in parts of petrochemical system due to cheap ethane from shale gas. US gas price still low compared to EU gas and oil prices surging.
Asia experiences restricted import arrivals and elevated feedstock costs triggering significant price increases for primary industrial intermediates. Japan naphtha costs at 559 per tonne CFR Japan in February show sensitivity to crude movements.
Pricing Outlook And Buyer Strategies
Chemical price trends by region in 2026 suggest buyers should separate feedstock trend from conversion trend. A category that appears stable upstream can still carry 3% to 8% cost pressure from utilities, wastewater treatment, or low-capacity utilization.
For procurement teams managing food-grade chemicals, practical steps include tracking crude oil and natural gas separately from mineral feedstock indexes like zinc LME. Use tiered budgeting with base case 0 to 3%, pressure case 4 to 8%, disruption case above 8%. Align contract terms with cost reality using indexed pricing linked to LME or natural gas TTF plus conversion fee, with energy surcharge triggers.
Global chemical forecast notes substitution decisions need updated cost logic. Lower nominal price does not always equal lower total exposure if energy pass-through clauses are aggressive. That applies to choosing between ferrous sulfate commodity versus ferric pyrophosphate specialty. The specialty may have higher invoice price but lower total exposure because it avoids rework, color rejection, and vitamin degradation.
Focus on four decision signals: input trend, lead-time movement, supplier capacity discipline, and compliance friction. When three move same direction for 6 to 8 weeks, probability of sustained price pressure rises materially. Suppliers mentioning allocation, maintenance shutdowns, packaging shortages, or shortened quotation validity from 30 days to 7 days signal uncertainty.
Market will experience accelerated adoption of digital and sustainable technologies, with notable shift toward bio-based and circular chemicals. Global market for sustainable chemical feedstocks 2027-2035 represents change in raw material base comparable to shift from coal to oil in mid-twentieth century. That shift will gradually decouple some chemical pricing from crude oil and natural gas, but for 2026-2027, crude and gas remain fundamental drivers.
Sources:
Chemicals Price Trends by Region in 2026 – HantecOrg – feedstock structure affects impurity profile, lot consistency, production flexibility – feedstock advantage real but not permanent – https://hantecorg.com
Industry trends Chemicals October 2026 – Atradius – Indonesia and Vietnam feedstock exposure – businesses only able to pass on higher feedstock costs limited extent – https://group.atradius.com
Chemical Manufacturing Trends Shaping Cost and Supply – SectorPulseLive – crude oil, natural gas, coal still influence many chains – conversion efficiency, utility cost, process yield determine competitiveness – https://sectorpulselive.com
Global Chemical Forecast: 2026 Cost Drivers to Watch – HGiron – natural gas and electricity costs reset floor price quickly – https://hgiron.com
Geopolitical Risks And Global Chemical Market Trends in 2026 – Energy Prices and Freight Costs Two Key Drivers – https://jinforestchem.com
Borax Anhydrous (Technical Grade) - Argentina
Found this useful?