Global Fertilizer Price Trends 2027: Supply-Demand Dynamics and International Market Developments
Global Fertilizer Price Trends 2027: Supply-Demand Dynamics and International Market Developments
Current Price Pressure Extending Into 2027
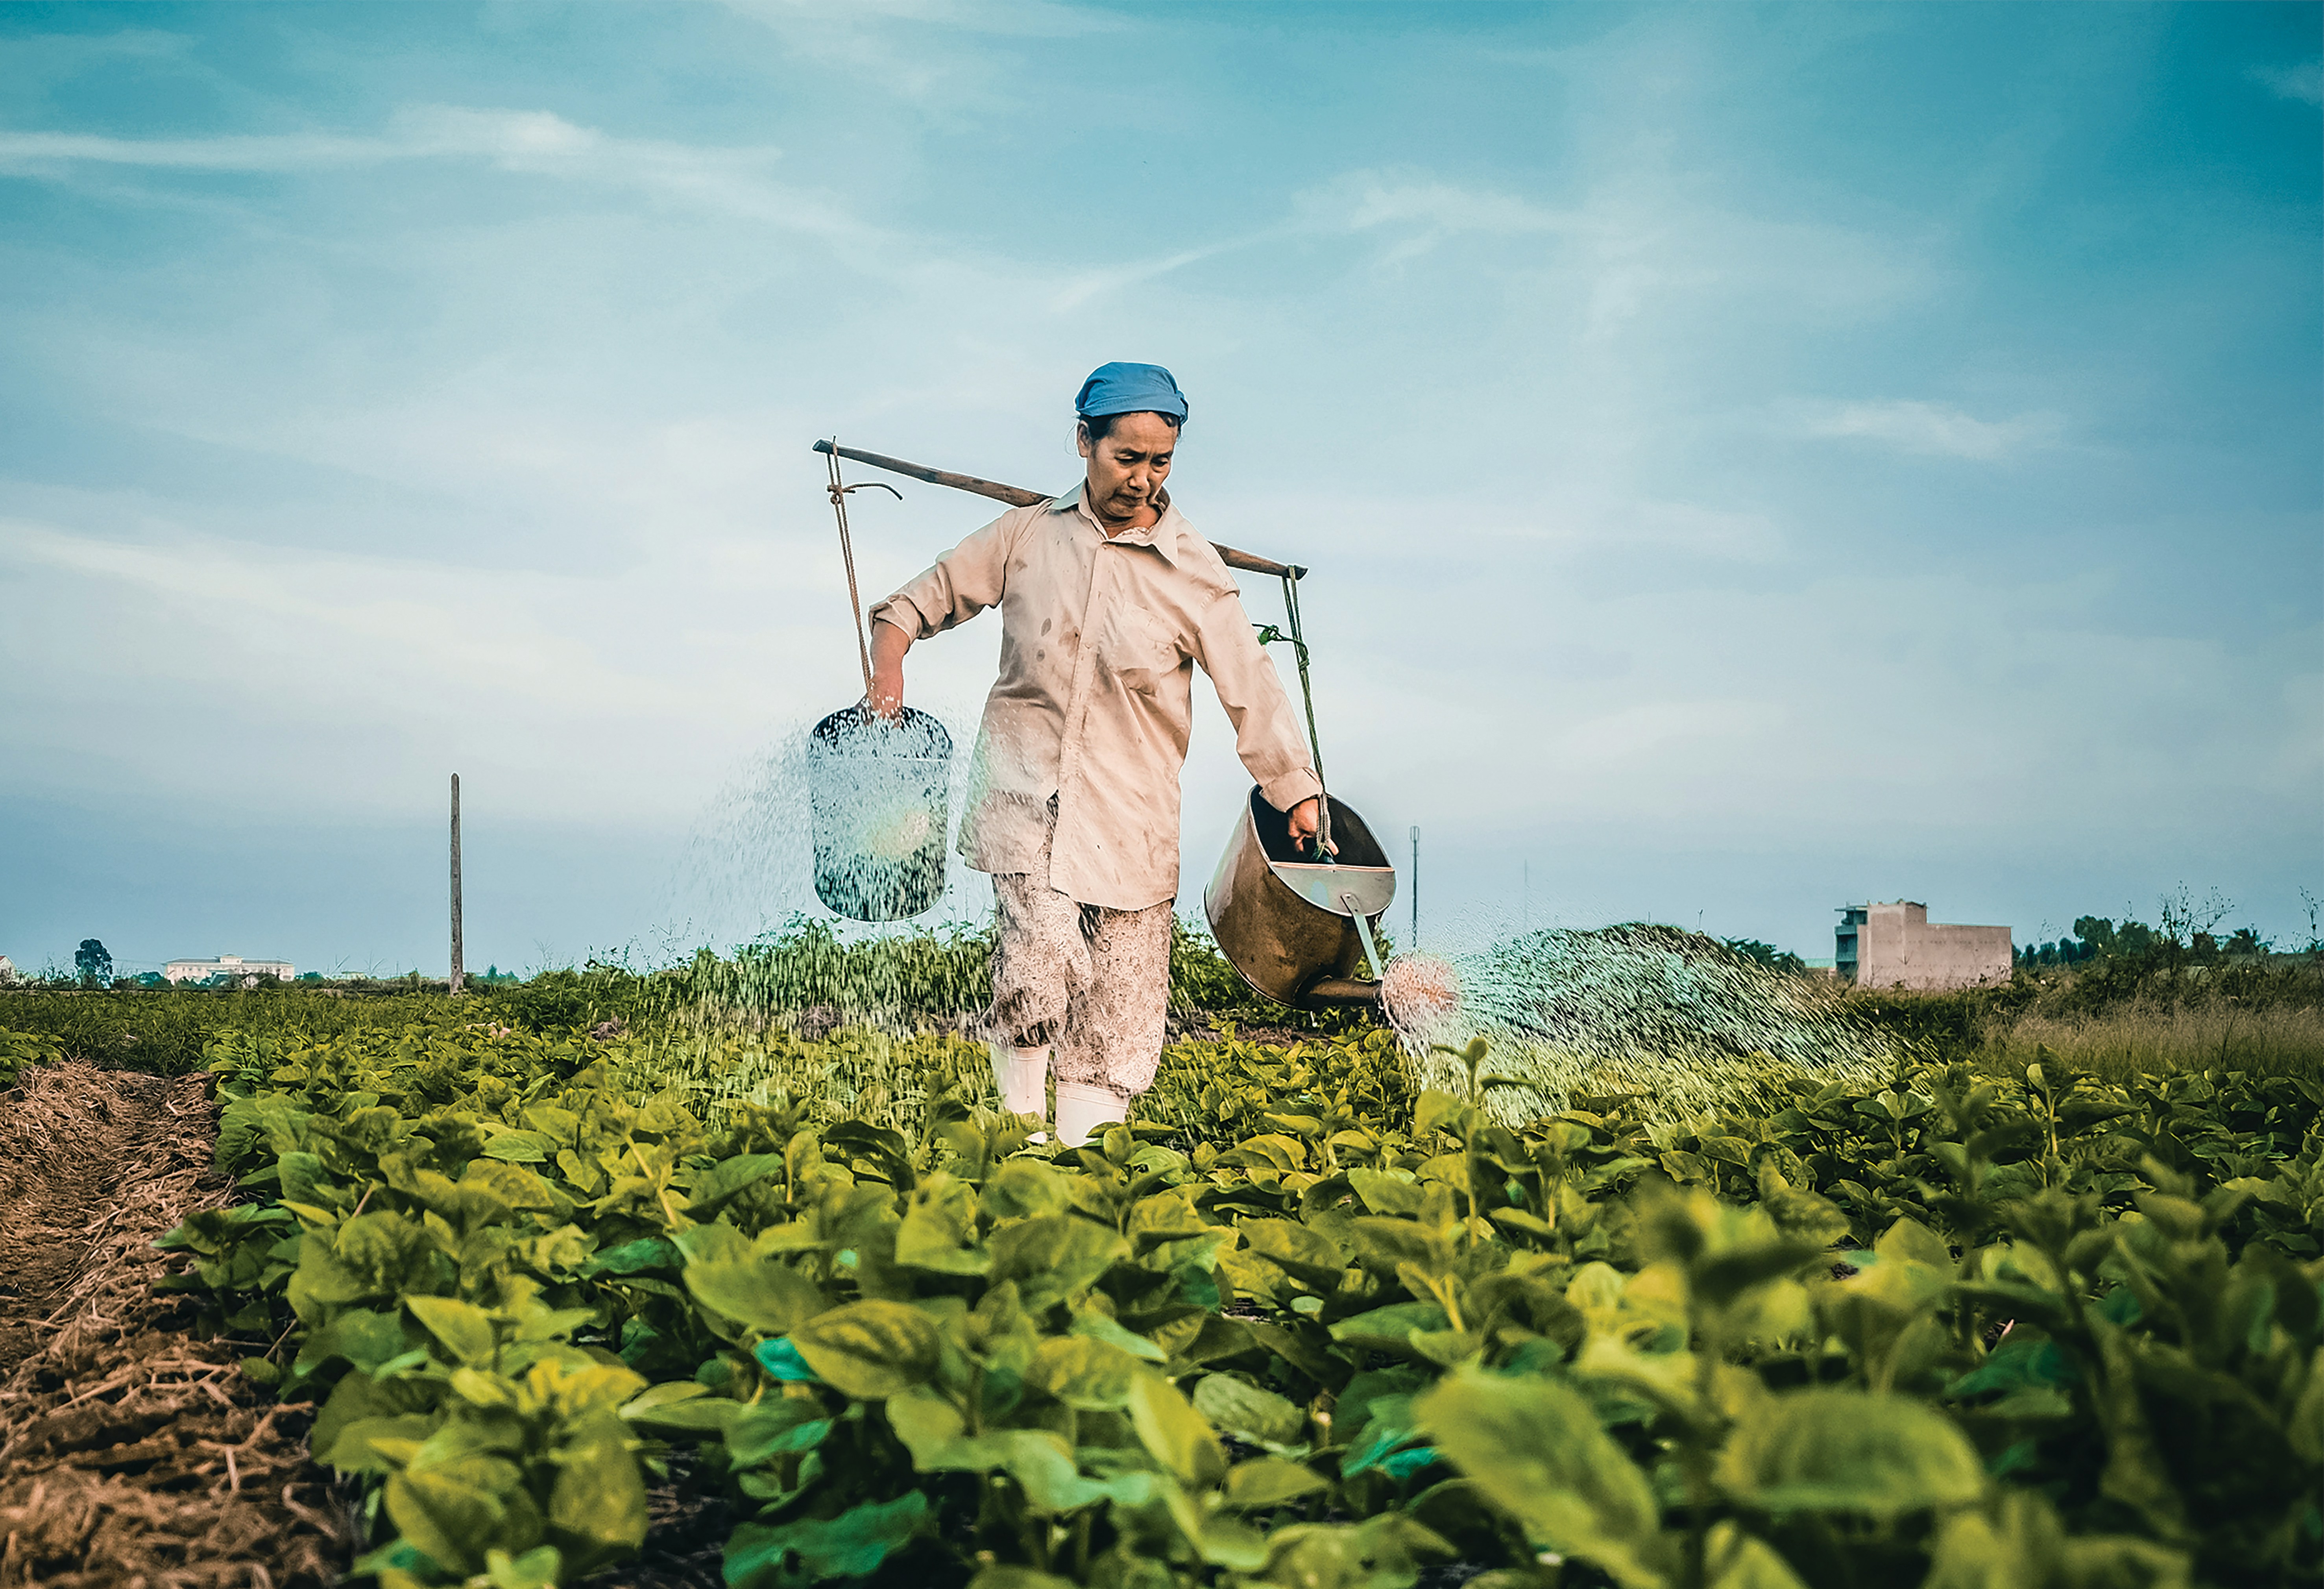
Fertilizer costs are already climbing as farmers prepare for 2027 growing season. University of Illinois researchers report that diammonium phosphate DAP prices have risen from about 700 dollars per ton early in 2026 to around 850 dollars per ton, while sulfur prices have surged more than 130% since early 2026. U.S. farmers are facing mounting fertilizer supply risks as of October 21, 2026, with industry analysts warning that disruptions in global nitrogen, phosphate and sulfur markets could extend into spring 2027.
The ripple effect of the Middle East conflict, compounded with tight supplies, will create higher fertilizer prices and complicate sourcing well into 2027 and beyond, said Jacqui Fatka, farm supply and biofuels economist with CoBank. Availability and affordability concerns have already triggered demand destruction and deferral, making the price outlook increasingly difficult to predict. Ultimately, market recovery will depend on stabilization in the Middle East, lower sulfur prices and shifts in global trade.
Fertilizer prices could stay high until 2027. Countries are reacting to fertilizer shocks in myriad ways. Fertilizer supply chain is expected to remain volatile for most of this year, with phosphate prices projected to remain high into 2027, as growers around world debate applications heading into their growing seasons, according to agri-finance company Rabobank's semiannual fertilizer outlook. U.S. and Israel's war with Iran has quickly led to sharp increases in fertilizer prices.
World Bank And CoBank Outlook – Easing But Elevated
Fertilizer markets soften but remain constrained by trade policies. The fertilizer price index is expected to ease in 2026 and 2027 after rising 20 percent this year. Urea prices are projected to jump 30 percent in 2025 amid tighter markets, then decline by 7 percent in 2026 and 9 percent in 2027 as new capacity comes online in East Asia and Middle East. Fertilizer prices softened in late 2025 but remain elevated due to rising input costs, China's export restrictions, and shifting global trade flows.
Global fertilizer market faces long recovery. The ripple effect of Middle East conflict, compounded with tight supplies, will create higher fertilizer prices and complicate sourcing well into 2027 and beyond. Availability and affordability concerns have triggered demand destruction and deferral.
Fertilizer prices to remain elevated through 2028. That longer horizon suggests 2027 is not a return to pre-pandemic lows but a new normal where fertilizer prices remain structurally higher than historical averages.
Nitrogen – Energy Link Most Critical
Nitrogen fertilizer production is directly tied to natural gas and ammonia. Natural gas liquids derived from gas production serve as key raw materials for ammonia, which is precursor for urea, ammonium nitrate, and UAN. High natural gas costs led directly to idling of acetyls units in UK, and same dynamic hits ammonia plants in Europe.
European producers face severe operational pressures due to elevated natural gas expenditures. When EU gas surges while US gas remains relatively low, US nitrogen producers gain competitive advantage. That regional divergence is expected to persist into 2027. Potash relatively stable with more favorable 2027 global supply outlook, while nitrogen remains volatile.
Farmers seem reluctant to reduce nitrogen applications despite rising prices, but affordability will remain challenge because commodity prices have not rebounded as they did after 2022 Ukraine war-driven fertilizer price runup. Historically when fertilizer prices high, farmers prioritize nitrogen application over phosphate and potassium, pattern evident in 2008 and 2022.
Global agriculture braces for impact – 2026 fertilizer crisis and looming shadow over 2027. Market is bracing for new normal where fertilizer prices remain structurally higher than historical averages. Market opportunities may emerge for specialized biological fertilizer companies and tech firms that can demonstrate proven reductions in synthetic fertilizer needs.
Phosphate And Sulfur – The Tightest Links For 2027
DAP prices rising from 700 to 850 dollars per ton illustrate phosphate pressure. Sulfur prices surged more than 130% since early 2026, directly affecting phosphate production because sulfuric acid is required to produce DAP and MAP from phosphate rock.
Phosphate supply is constrained by China's export restrictions, Morocco's OCP dominance, and sulfur availability. Sulfur is byproduct of oil and gas refining. When oil supply falls by 5.2%, 5.5 million barrels per day in 2026 as projected, sulfur availability also falls, creating secondary tightness. That explains why market recovery will depend on stabilization in Middle East, lower sulfur prices and shifts in global production.
NDSU projects 2027 averages for fertilizer at 496 dollars for urea, 666 dollars for DAP, 660 dollars for MAP, 619 dollars for ammonia, and 361 dollars for UAN. Those levels remain well above 2020-2021 averages, indicating structurally higher baseline.
Potential for second wave of new capacity exists. If this capacity comes online as global demand softens due to acreage shift, market could see sharp correction in late 2027. Until then, phosphate prices projected to remain high into 2027.
Regional Supply-Demand Dynamics
Asia faces restricted import arrivals and elevated feedstock costs triggering significant price increases for primary industrial intermediates, while European producers continue to face severe pressures due to elevated natural gas. China, major producer of urea and phosphates, has imposed export restrictions to secure domestic supply, tightening global market and shifting trade flows toward Middle East and Russia.
India, world's largest urea importer, faces mounting costs due to subsidy burden. Indonesia and Vietnam face similar feedstock exposure but benefit from relatively stronger domestic demand growth. Malaysia comparatively more resilient due to gas-linked capacity, although downstream derivatives remain exposed to higher input costs.
United States benefits from low-cost natural gas for nitrogen but remains import dependent for potash and phosphate. U.S. farmers facing mounting supply risks as of October 2026. Industry analysts warn disruptions could extend into spring 2027. Brazil, major importer of all three nutrients, faces freight cost increases due to Brent crude forecast averaging 91 dollars per barrel in 2026 up from 69 in 2025, before easing to 79 in 2027.
EU remains most vulnerable due to natural gas dependency. Fertilizer plants curtailment in 2022 repeated in 2026 with high gas prices. EU chemicals trade surplus reaches 257 billion euros in 2025, but fertilizer sector remains deficit.
Impact On Food-Grade Minerals And Broader Chemical Trade
Fertilizer trends directly affect food-grade minerals. Sulfuric acid price drives zinc sulfate production costs. Zinc sulfate tracks zinc metal plus sulfuric acid. When sulfur surges 130%, zinc sulfate food grade monohydrate costs rise even if zinc metal stable.
Phosphate rock processing competes with food-grade dicalcium phosphate production. Higher DAP prices incentivize phosphate rock producers to prioritize fertilizer grade over food grade, tightening food-grade phosphate supply for bakery and dairy applications.
Ammonia and urea price increases raise costs for chelated minerals like zinc bisglycinate that use ammonia in synthesis, and for encapsulation materials using urea-formaldehyde.
Potash stability offers some relief for potassium iodide and potassium iodate used in salt iodization, as potash provides potassium feedstock.
Pricing Outlook And Buyer Strategies For 2027
Will fertilizer prices go down in 2027? Global fertilizer supply conditions could improve in 2027, which may provide some price relief. However, energy prices, international trade, shipping disruptions, and spring demand could keep some fertilizer prices elevated. Natural gas prices, global production and spring demand will be important factors.
Buyers of agricultural inputs and food-grade minerals should consider tiered budgeting. Base case assumes modest decline in urea 7% in 2026 and 9% in 2027 as new capacity comes online in East Asia and Middle East. Pressure case assumes Middle East conflict persists, sulfur remains elevated, DAP stays at 850 dollars. Disruption case assumes Super El Niño affecting logistics and further oil supply decline.
Practical strategies include securing nitrogen needs early for 2027 planting, as farmers prepare now and costs climbing. Consider biological fertilizer alternatives that demonstrate proven reductions in synthetic needs, as market opportunities emerge for specialized companies. Track sulfur as leading indicator for phosphate pricing. For food-grade zinc sulfate and ferrous fumarate, lock in sulfuric acid linked pricing where possible, and diversify sourcing away from gas-dependent European production toward regions with secure energy and feedstock access.
Fertilizer supply chain expected to remain volatile, with trade policies, China's export restrictions, and shifting global trade flows shaping markets. Companies reassessing supply chains prioritizing resilience alongside cost efficiency will accelerate regionalization trends, encourage investment in integrated production hubs, and increase strategic importance of countries with secure energy and feedstock access.
Sources:
Agricultural train wreck and 2027 global food crisis – InvestorIdeas – DAP prices risen from 700 to 850 per ton – sulfur surged 130% – supply risks extend into spring 2027 – https://investorideas.com
Fertilizer markets soften but remain constrained by trade policies – World Bank Blogs – fertilizer price index expected to ease in 2026 and 2027 after rising 20% – urea jump 30% in 2025 then decline 7% 2026 and 9% 2027 – https://blogs.worldbank.org
Global Fertilizer Market Faces Long Recovery – Pennsylvania Ag Connection – CoBank Fatka – ripple effect Middle East conflict – higher prices complicate sourcing well into 2027 – https://pennsylvaniaagconnection.com
Fertilizer prices to remain elevated through 2028 – World Fertilizer – CoBank – demand destruction and deferral – https://worldfertilizer.com
Aluminium Stearate
Found this useful?