Low-Carbon Chemical Manufacturing: Technologies, Challenges and Market Outlook
Chemical manufacturers face a growing challenge: reducing greenhouse gas emissions without compromising production reliability, product quality or international competitiveness. Low-carbon chemical manufacturing offers a pathway to meet this challenge by changing how factories use energy, source raw materials and manage industrial emissions.
The transition matters across commodity chemicals, petrochemicals, fertilisers and specialty ingredients. Producers must evaluate technologies that can reduce emissions while helping buyers maintain dependable supply and manageable procurement costs. For chemical traders and importers, these changes may also reshape export opportunities, supplier selection and the commercial value of lower-emission products.
What Is Low-Carbon Chemical Manufacturing?
Low-carbon chemical manufacturing involves producing chemicals with lower greenhouse gas emissions than conventional production routes. Manufacturers achieve this through cleaner energy, more efficient processes, alternative feedstocks, carbon capture and improved resource recovery.
The concept covers more than switching from fossil fuels to renewable electricity. Chemical plants also release emissions through the chemical reactions that transform raw materials into finished products, while fossil-based feedstocks introduce additional carbon into production systems. Effective decarbonisation must address both energy consumption and the carbon embedded in manufacturing processes.
Common approaches include:
Energy efficiency: Improving heat recovery, insulation, process control and equipment performance to reduce fuel and electricity consumption.
Renewable electricity: Replacing fossil-fuel-based power with electricity generated from renewable sources.
Low-carbon feedstocks: Using suitable recycled, bio-based or other alternative raw materials instead of conventional fossil-based inputs.
Low-emission hydrogen: Using hydrogen produced through lower-emission pathways in processes that require hydrogen as a reactant or energy carrier.
Carbon capture: Capturing carbon dioxide from industrial processes and directing it towards suitable utilisation or permanent storage.
Manufacturers do not need to implement every technology simultaneously. The most effective strategy depends on the chemical product, existing plant equipment, local energy availability and the cost of changing established production processes.
Technologies Transforming Chemical Production
Several technologies can reduce emissions, although their readiness, economics and suitability differ across chemical applications.
Electrification and renewable energy
Electrification allows manufacturers to replace certain fossil-fuel-based heating and processing systems with electrical alternatives. Renewable electricity can reduce associated emissions when it displaces more carbon-intensive power, although the result depends on the electricity supply and the specific production process.
Electric heating, heat pumps and electrically driven process equipment offer opportunities for facilities that require substantial thermal energy. However, some chemical reactions need very high temperatures or specialised equipment, making direct electrification more difficult than replacing conventional motors or auxiliary systems.
Green hydrogen and low-emission ammonia
Hydrogen plays an important role in chemical manufacturing, particularly in ammonia and methanol production. Conventional hydrogen production often relies on fossil fuels, while electrolytic hydrogen uses electricity to split water into hydrogen and oxygen.
When electrolysis relies on low-emission electricity, it can provide a lower-carbon hydrogen source. Manufacturers can use this hydrogen to produce lower-emission ammonia and other chemicals, subject to the wider production pathway and its associated emissions.
For fertiliser producers and industrial buyers, this shift could influence the availability, cost and sourcing requirements of ammonia-based products. However, renewable electricity prices, electrolyser investment and hydrogen transport infrastructure remain important commercial considerations.
Carbon capture, utilisation and storage
Carbon capture, utilisation and storage (CCUS) provides another route for reducing emissions, particularly where chemical reactions release carbon dioxide or existing production systems remain difficult to replace.
Manufacturers can capture carbon dioxide, then either use it in suitable applications or transport it to facilities designed for permanent storage. The effectiveness of this approach depends on capture performance, energy requirements, transport arrangements and the final destination of the captured carbon.
CCUS may prove especially relevant for established chemical plants that cannot immediately transition to alternative feedstocks or production technologies. Nevertheless, installation costs and access to shared transport and storage infrastructure can determine whether a project makes commercial sense.
Recycling and alternative feedstocks
Chemical recycling and mechanical recycling can reduce demand for virgin fossil-based materials when recovered inputs meet the quality requirements of downstream manufacturing. Recycled feedstocks can support circular material flows, while suitable bio-based inputs may replace fossil-derived carbon in selected products.
These alternatives require careful assessment of purity, consistency, availability and compatibility with existing processes. Buyers must also examine whether the alternative material meets technical specifications and whether its emissions benefits extend across the wider supply chain.
The Main Challenges Facing Chemical Manufacturers
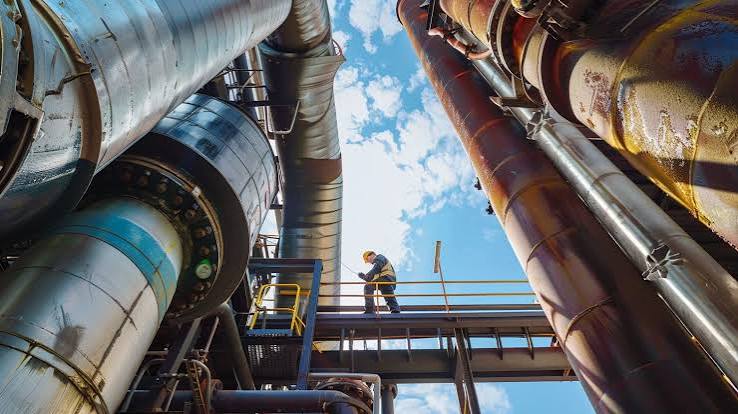
Low-carbon technologies can reduce emissions, but manufacturers must balance environmental objectives against operating costs, production requirements and investment risks.
High capital expenditure remains a major barrier. Replacing reactors, installing electric heating systems, developing hydrogen production capacity or integrating carbon capture can require substantial upfront investment. Companies must assess whether projected energy savings, customer demand and available financial support justify the expenditure.
Energy prices affect the business case. Electricity-intensive production routes may struggle to compete when renewable power or low-emission hydrogen costs more than conventional alternatives. Regional differences in energy prices can therefore influence where manufacturers build new facilities and which production routes they select.
Other challenges include:
Technology readiness: Some improvements are commercially established, while emerging processes still require demonstration, engineering development and reliable operating records.
Feedstock availability: Recycled and bio-based raw materials may face inconsistent supply, variable quality or competition from other industries.
Infrastructure limitations: Hydrogen networks, renewable electricity connections and carbon dioxide transport systems may not exist near every industrial facility.
Production continuity: Manufacturers must introduce new equipment or operating methods without disrupting customer deliveries or compromising product specifications.
Measurement and verification: Companies need consistent methods to calculate emissions and substantiate environmental claims across production stages.
These barriers rarely have a single solution. Manufacturers often benefit from implementing proven efficiency measures first while preparing longer-term investments in new process technologies.
How Low-Carbon Manufacturing Could Reshape Chemical Trade
The transition can change international chemical trade by influencing production costs, supplier competitiveness and the location of future manufacturing capacity.
Regions with abundant renewable electricity and access to suitable raw materials may gain advantages in producing certain lower-emission chemicals. Countries with established chemical infrastructure may also retain a competitive position by upgrading existing facilities rather than constructing entirely new plants.
The International Renewable Energy Agency identifies renewable electricity, renewable hydrogen, alternative feedstocks and carbon management as important pathways for decarbonising chemical and petrochemical production. These pathways could gradually influence the geography of chemical supply chains.
For importers, exporters and trading companies, several developments deserve attention:
Changing supplier preferences: Buyers may increasingly request emissions information alongside conventional specifications, prices and delivery terms.
New export opportunities: Producers that develop credible lower-emission products may access customers seeking to reduce supply-chain emissions.
Regional cost differences: Manufacturers with affordable low-carbon energy could gain an advantage in selected products, while higher energy costs may constrain other producers.
Traceability requirements: Importers may need stronger documentation covering feedstock origin, production methods and emissions calculations.
Product differentiation: Verified emissions performance could become an additional factor in supplier evaluation, particularly where customers have formal sustainability targets.
These changes will not affect every chemical in the same way. Commodity products with narrow margins may face different adoption pressures from specialty chemicals whose customers place greater emphasis on traceability, technical performance and sustainability credentials.
Regulations, Carbon Reporting and Buyer Expectations
Regulatory requirements and customer expectations increasingly shape how manufacturers evaluate their environmental performance. Companies operating across several markets may need to manage different emissions reporting frameworks, product standards and disclosure requirements.
For chemical suppliers, emissions reporting can influence customer qualification and contract negotiations. Buyers may ask suppliers to provide information about production energy, feedstock sourcing, manufacturing emissions and the methods used to calculate a product's carbon footprint.
Three areas deserve particular attention:
Carbon accounting: Manufacturers need reliable emissions data covering relevant production activities and energy inputs. Consistent calculations help companies identify reduction opportunities and respond to customer requests.
Product-level transparency: Buyers may seek emissions information for individual products rather than relying solely on a supplier's overall sustainability claims. Clear documentation helps procurement teams compare suppliers on a more consistent basis.
Environmental claims: Companies should support claims such as low-carbon or reduced-emission with appropriate evidence. A product's environmental performance depends on its manufacturing route, energy sources and relevant supply-chain activities.
Regulatory exposure also varies by destination market and product category. Chemical traders should monitor applicable import rules, reporting obligations and customer-specific requirements instead of assuming that one certification or reporting method will satisfy every buyer.
Market Outlook: Investment, Innovation and Competitive Positioning
The outlook for low-carbon chemical manufacturing depends on how quickly producers can deploy suitable technologies, secure affordable energy and establish reliable markets for lower-emission products.
The International Energy Agency's net-zero pathway for primary chemicals illustrates the scale of the anticipated transformation. Its 2023 roadmap update projects that near-zero-emission production could account for 17% of primary chemical output by 2030 and 93% by 2050 under its net-zero scenario. These figures represent a scenario pathway rather than a guaranteed market outcome.
Several developments could shape investment and trade over the coming years.
Efficiency improvements will remain an immediate priority. Manufacturers can often reduce energy consumption through better process control, heat recovery and equipment upgrades before committing to more expensive production technologies. These measures can also help lower operating costs while companies assess longer-term investments.
Hydrogen-based production may expand selectively. Lower-emission hydrogen could support changes in ammonia and methanol production, particularly where renewable electricity and suitable infrastructure are available. Commercial adoption will depend on production costs, dependable supply and demand for the resulting products.
Carbon capture could support existing industrial assets. Facilities with significant process emissions may consider carbon capture where alternative production routes remain technically difficult or economically unattractive. Access to transport and storage infrastructure will strongly influence project feasibility.
Circular feedstocks could change raw material purchasing. Recycled materials and suitable bio-based alternatives may create new sourcing opportunities for manufacturers seeking to reduce reliance on virgin fossil resources. Consistent quality and dependable volumes will remain essential for large-scale adoption.
The commercial outlook will therefore differ across regions and chemical categories. Producers with access to competitive low-carbon energy, dependable feedstocks and established infrastructure may move faster, while others may prioritise incremental improvements until costs and market demand become more favourable.
What Procurement Teams Should Do Now
Procurement teams can prepare for this transition without immediately replacing established suppliers or paying a premium for every product labelled sustainable. A structured assessment of suppliers, technical requirements and total sourcing costs provides a practical starting point.
The following actions can help buyers manage the shift:
1. Review priority chemicals. Identify products with significant energy requirements, exposure to customer emissions targets or potential supply-chain changes. Focus initial assessments on chemicals that matter most to purchasing budgets and operational continuity.
2. Request comparable emissions information. Ask suppliers how they calculate product emissions, which production stages they include and whether independent verification supports their claims. Consistent boundaries make supplier comparisons more meaningful.
3. Assess technical equivalence. Confirm that lower-emission alternatives meet required purity levels, performance standards, documentation requirements and applicable regulations before approving them for use.
4. Compare total delivered costs. Evaluate product prices alongside freight, storage, handling, certification requirements and potential supply disruptions. A lower-emission option must also meet the buyer's practical sourcing needs.
5. Diversify qualified suppliers. Monitor producers in different regions to understand where new manufacturing capacity may emerge. Alternative suppliers can improve resilience when energy prices, regulations or feedstock availability affect established trade routes.
6. Use contracts to improve visibility. Where commercially appropriate, include provisions for emissions reporting, product traceability, quality assurance and advance notification of production changes. Clear requirements can help both parties manage expectations.
Chemical traders can also strengthen their market position by connecting buyers with suppliers that provide reliable product documentation and transparent production information. Verified emissions data, consistent specifications and dependable delivery can help distinguish a supplier in a market where sustainability expectations continue to evolve.
The most effective sourcing strategy combines environmental performance with technical suitability, cost discipline and supply reliability. Buyers that begin evaluating these factors now will be better prepared to respond as lower-carbon production becomes more commercially relevant.
Ammonium Bicarbonate (E503(ii))
SOURCE LINK: https://www.iea.org/
Found this useful?