Petrochemical Industry Outlook 2026: Key Trends in Demand, Production, and Global Trade
Petrochemical Industry Outlook 2026: Key Trends in Demand, Production, and Global Trade
The global petrochemical industry is entering 2026 amid changing demand patterns, production challenges, rising feedstock costs, and shifts in international trade. Petrochemicals remain essential to modern manufacturing, providing the building blocks for plastics, synthetic fibres, packaging, automotive components, construction materials, detergents, and countless industrial products.
However, the industry's growth is no longer determined by demand alone. Production capacity, energy prices, geopolitical developments, freight costs, environmental regulations, and competition between manufacturing regions are increasingly influencing profitability and investment decisions.
In 2026, the industry faces a complex combination of structural oversupply and supply-side disruptions. While some producers are benefiting from tighter availability and higher selling prices, others are struggling with expensive raw materials and weak downstream demand. These differences are reshaping how chemical manufacturers plan production, manage inventory, and compete in international markets.
Global Petrochemical Market Overview in 2026
The petrochemical sector is expected to remain an important driver of long-term chemical demand, supported by applications across packaging, consumer goods, construction, healthcare, electronics, and transportation.
According to Krungsri Research's 2026 industry outlook, global petrochemical demand could grow by an average of 3.0%–4.5% annually over 2026–2028, although the outlook remains exposed to economic uncertainty and supply-side risks. This is a forecast rather than a guaranteed growth rate, and actual market performance will vary by product and region. Source: Krungsri Research.
Several factors are shaping the industry:
Demand recovery: Consumption of petrochemical products depends on economic activity, industrial output, consumer spending, and manufacturing growth.
Uneven production capacity: New capacity in some markets continues to challenge older or higher-cost facilities.
Feedstock volatility: Changes in crude oil, naphtha, ethane, propane, and natural gas prices affect production costs and margins.
Trade and logistics disruptions: Shipping constraints and geopolitical tensions can interrupt raw material supplies and finished-product deliveries.
Sustainability pressures: Recycling, renewable feedstocks, energy efficiency, and lower-emission manufacturing are becoming more important to long-term competitiveness.
Together, these developments are making regional cost advantages and supply chain flexibility increasingly important for petrochemical producers.
1. Petrochemical Demand Trends in 2026
Packaging and Consumer Goods
Packaging remains a major application for petrochemical-derived polymers, including polyethylene (PE) and polypropylene (PP). These materials are widely used in films, containers, bottles, protective packaging, and household products.
Demand depends on consumer spending, e-commerce activity, food distribution, and industrial packaging requirements. However, the market is also evolving as manufacturers seek lighter packaging, improved material efficiency, recycled content, and alternatives to conventional plastics.
Producers must therefore balance demand for cost-effective materials with changing customer expectations and packaging regulations.
Automotive and Transportation
The automotive industry continues to create demand for engineering plastics, synthetic rubber, adhesives, coatings, and other petrochemical-based materials. Applications include interior components, tyres, electrical insulation, and lightweight structural parts.
Electric vehicles also require polymers and specialty materials for cable insulation, battery-related components, thermal management, and electronic systems. However, vehicle production cycles and competition among manufacturers can influence short-term demand.
In 2026, product segments linked to automotive applications may perform differently from those serving construction or consumer packaging, making product-level market analysis essential.
Construction and Infrastructure
Construction supports demand for polyvinyl chloride (PVC), insulation materials, sealants, coatings, adhesives, and other chemical products.
Infrastructure investment and urban development can create opportunities for petrochemical suppliers, particularly in growing economies. Nevertheless, high financing costs, slow property markets, and delays in construction projects may limit consumption in some regions.
Emerging Economies and Industrial Growth
Asia remains central to global petrochemical consumption because of its manufacturing base, large consumer markets, and expanding industrial activity. India and Southeast Asian economies offer opportunities in packaging, infrastructure, automotive manufacturing, and consumer products.
China remains a major influence on the global market because of its large petrochemical production capacity and domestic manufacturing sector. Yet capacity growth and changes in China's economic activity can affect both local prices and export availability.
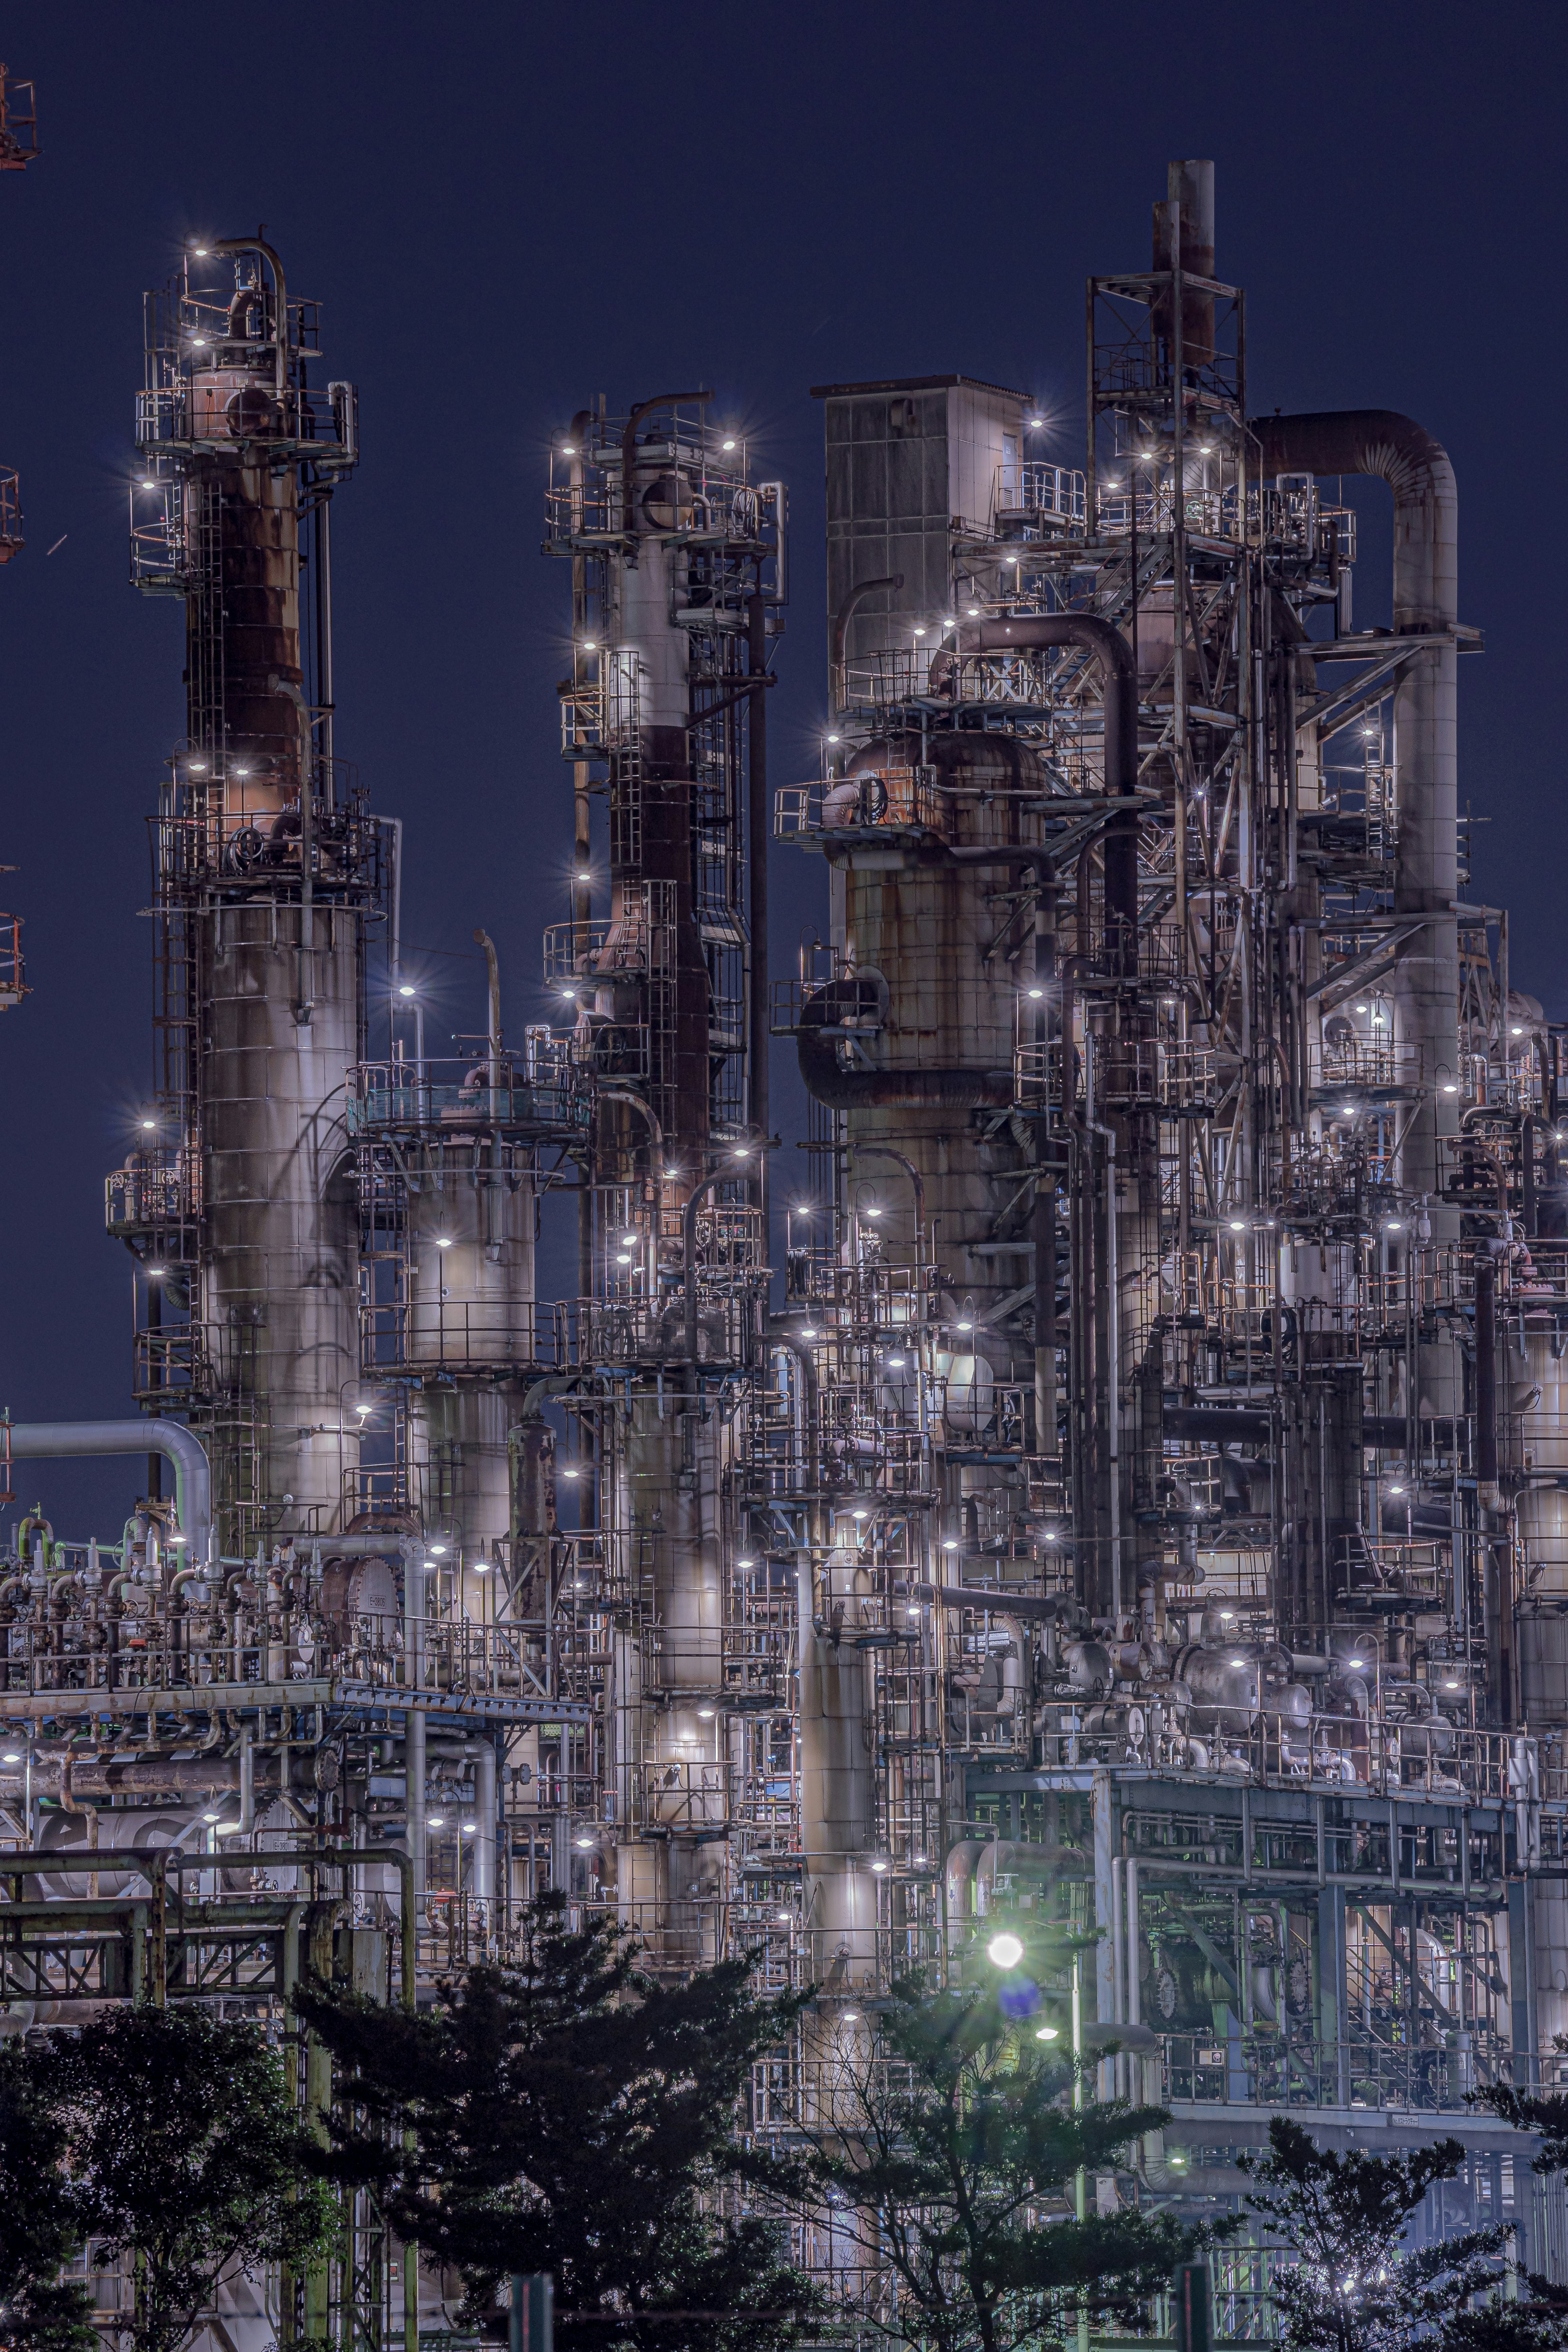
Asia remains a central market for petrochemicals, with China serving as a major producer and consumer. India and Southeast Asia also provide important opportunities as manufacturing, infrastructure, and consumer markets develop.
However, regional producers face differing challenges. Some benefit from domestic feedstock availability or integrated manufacturing facilities, while others depend heavily on imported naphtha and liquefied petroleum gas.
This creates opportunities for suppliers that can diversify procurement, maintain reliable inventories, and respond quickly to changing regional demand.
North America: Feedstock Cost Advantages
North America, particularly the United States, benefits from access to ethane and other natural gas liquids. These feedstocks can provide a cost advantage for ethylene production compared with naphtha-based manufacturing when relative prices are favourable.
Export infrastructure allows North American producers to supply overseas markets, including Asia and Europe. However, shipping costs, trade policies, port capacity, and international price differences influence whether exports remain commercially attractive.
Europe: Competitiveness and Industrial Restructuring
European petrochemical producers face pressure from energy and feedstock costs, international competition, and environmental requirements. Older or less-efficient facilities may struggle when imported products can be produced at lower cost elsewhere.
These challenges are encouraging manufacturers to evaluate energy efficiency, operational improvements, specialty chemical opportunities, and the future viability of individual production assets.
The Middle East: Feedstock and Logistics Exposure
The Middle East remains a strategically important petrochemical production region because of its hydrocarbon resources and established industrial infrastructure.
Nevertheless, geopolitical tensions and disruptions to critical shipping routes can affect exports of feedstocks and finished chemicals. These risks highlight the importance of alternative logistics arrangements, regional storage, and diversified supply contracts.
For global buyers, the lowest quoted product price may not represent the lowest total procurement cost if freight rates, insurance, delivery uncertainty, and inventory requirements increase.
4. Key Petrochemical Products to Watch in 2026
Different petrochemical products face different supply-demand conditions, making it important to assess individual markets rather than treating the industry as one uniform sector.
Product | Major applications | Key market considerations |
|---|---|---|
Ethylene | Polyethylene, ethylene oxide, other chemical intermediates | Feedstock economics, cracker capacity, and polymer demand |
Propylene | Polypropylene, acrylonitrile, propylene oxide | PDH capacity, refinery output, and regional supply balances |
Polyethylene (PE) | Packaging, films, containers, pipes | Packaging demand, exports, and capacity additions |
Polypropylene (PP) | Automotive parts, packaging, household goods | Consumer demand, production costs, and new capacity |
Polyvinyl chloride (PVC) | Pipes, construction materials, profiles | Construction activity, regional supply, and regulatory developments |
Benzene | Styrene, phenol, other aromatic chemicals | Refinery operations, derivative demand, and feedstock costs |
Purified terephthalic acid (PTA) and PET | Polyester fibres, bottles, packaging | Textile demand, packaging consumption, and production capacity |
Market conditions can differ significantly even between products within the same value chain. For example, tight propylene availability does not necessarily mean that polypropylene producers can pass higher costs on to customers if downstream demand remains weak.
Krungsri Research's 2026 outlook also identifies differences in expected product margins across ethylene, propylene, HDPE, polypropylene, benzene, PET, and PVC. These differences illustrate why producers and buyers need product-specific market intelligence. Read the industry outlook.
5. Sustainability and the Transition Toward Circular Petrochemicals
Sustainability is becoming an increasingly important consideration in petrochemical investment and product development. Manufacturers are exploring ways to reduce waste, improve energy efficiency, lower emissions, and incorporate alternative raw materials.
Chemical Recycling
Chemical recycling technologies aim to convert selected plastic waste streams into chemical feedstocks or other useful intermediates. Depending on the process, these outputs may be used in the production of new polymers or other chemicals.
Chemical recycling could complement mechanical recycling for suitable waste streams that are difficult to process through conventional methods. However, its environmental and economic performance depends on technology, energy consumption, waste quality, conversion yields, and the treatment of process emissions.
Bio-Based Feedstocks
Renewable feedstocks derived from agricultural residues, biomass, plant oils, and other biological resources offer alternative sources of carbon for certain chemical products.
These materials can help diversify feedstock supply and may reduce lifecycle emissions in appropriate applications. Their adoption depends on sustainable sourcing, product performance, availability, and cost competitiveness.
Energy Efficiency and Emissions Reduction
Manufacturers are also investing in process optimization, heat recovery, electrification where technically feasible, and lower-emission energy sources.
For energy-intensive petrochemical facilities, these measures can improve resource efficiency and potentially reduce operating costs over time. The pace of adoption depends on capital availability, infrastructure, technology maturity, and regional energy markets.
6. Major Risks Facing the Petrochemical Industry
Several risks could influence market conditions throughout the remainder of 2026.
Geopolitical uncertainty: Conflicts and disruptions to key shipping routes can affect feedstock availability, insurance costs, and delivery schedules.
Weak downstream demand: Higher chemical prices may not translate into stronger profitability if customers reduce orders or postpone purchases.
Structural oversupply: Excess capacity can continue to weigh on margins even when temporary supply disruptions push prices upward.
Freight and logistics volatility: Higher shipping costs and limited vessel availability can change the economics of international trade.
Regulatory developments: Environmental requirements, recycled-content policies, and restrictions on certain materials may alter investment priorities and product demand.
Investment uncertainty: Prolonged market volatility can delay capacity additions, plant upgrades, and decisions to retire older assets.
These risks are interconnected. For example, a shipping disruption may increase feedstock prices, force production cuts, and raise chemical prices without improving demand from end users.
S&P Global's second-half 2026 chemicals outlook discusses the risk of weak consumption, elevated inventories, and continued price volatility across chemical markets.
7. What Petrochemical Companies Should Prioritize
To navigate changing market conditions, manufacturers, distributors, and procurement teams should focus on operational flexibility and informed purchasing decisions.
Diversify feedstock sourcing: Identify alternative suppliers and suitable feedstock routes to reduce dependence on a single region or transportation corridor.
Monitor product-level market trends: Track prices, supply availability, operating rates, inventories, and demand indicators for individual chemicals rather than relying solely on broad industry forecasts.
Improve inventory planning: Balance the cost of holding stock against the risks of shortages, longer lead times, and sudden price changes.
Strengthen supplier relationships: Work with reliable suppliers that provide consistent specifications, transparent delivery commitments, and clear communication about disruptions.
Evaluate total landed cost: Consider product price, freight, insurance, duties, handling, and delivery reliability when comparing international suppliers.
Invest in operational efficiency: Improve energy use, maintenance planning, production flexibility, and resource efficiency to strengthen competitiveness.
Assess circular and renewable alternatives: Evaluate recycled and bio-based inputs where they can meet technical requirements and deliver credible economic or environmental benefits.
Conclusion: What Lies Ahead for Petrochemicals in 2026?
The petrochemical industry in 2026 is being shaped by two forces that can operate in opposite directions: long-term demand for chemical products and short-term pressures from excess capacity, volatile feedstocks, and trade disruptions.
Asia remains central to the industry's production and consumption outlook, while North America retains important feedstock advantages and Europe faces continued competitiveness challenges. The Middle East remains a critical supply region, but recent disruptions demonstrate how quickly logistics risks can affect global markets.
For manufacturers and buyers, success will depend on understanding individual product markets, maintaining flexible supply chains, and making procurement and investment decisions based on current conditions rather than headline price movements alone.
Over the longer term, technological innovation, operational efficiency, recycling, and renewable feedstocks will influence how the industry develops. Companies that combine cost competitiveness with supply chain resilience and responsible production practices will be better positioned to navigate the next phase of global petrochemical manufacturing.
Sources and Further Reading
Activated Carbon (Powder) - India
Found this useful?