Saudi Arabia’s SAN-7 Fertilizer Complex: What the $3.46 Billion Project Means for Ammonia and Urea Markets
Saudi Arabia has approved a new $3.46 billion fertilizer complex that will add 1.2 million tonnes per year of ammonia capacity and 2.6 million tonnes per year of combined urea capacity. The SAN-7 project, developed by SABIC Agri-Nutrients in Jubail, also includes carbon capture and is scheduled to reach commercial production in the fourth quarter of 2030.
For ammonia and urea buyers, the project represents more than another industrial expansion. It points to a substantial increase in Saudi Arabia’s future fertilizer output and creates a development that procurement teams will need to track as they plan long-term sourcing strategies.
SAN-7 Brings a Major Increase in Saudi Urea Capacity
The scale of SAN-7 stands out because it will substantially increase SABIC Agri-Nutrients’ existing urea production base. The company currently has approximately 4.8 million tonnes per year of urea capacity, while the new project is expected to raise that figure to 7.4 million tonnes per year.
That represents an approximately 54% increase in urea production capacity, according to the company’s project announcement. Construction is expected to begin during the fourth quarter of 2026, followed by commissioning in the third quarter of 2030 and commercial production in the fourth quarter of the same year.
The project includes:
1.2 million tonnes per year of ammonia capacity, forming the core upstream production unit.
2.6 million tonnes per year of combined urea capacity, supplied through two urea plants.
A post-combustion carbon capture unit, integrating carbon management into the production complex.
A $3.465 billion EPC contract awarded to Samsung E&A for project execution.
For buyers, the important point is the additional nameplate capacity. Once commercial operations begin, the project should create significantly more potential availability from one of the region’s established fertilizer producers.
Why Samsung E&A’s EPC Role Matters
SABIC Agri-Nutrients selected South Korea’s Samsung E&A to execute the engineering, procurement and construction contract. Samsung E&A announced the contract at approximately $3.5 billion and confirmed that it will carry out the EPC work for the project through completion targeted for 2030.
The arrangement also reflects the increasingly international structure of large chemical projects. Saudi feedstock and industrial infrastructure combine with Korean engineering expertise and technology providers from several international companies.
Samsung E&A identifies ammonia and urea facilities as part of its core hydrocarbon-sector capabilities. The company also points to its previous project relationship with SABIC and its experience executing major projects in Saudi Arabia.
For chemical traders, EPC execution matters because commissioning schedules directly affect when additional product capacity can actually enter the market. The current schedule places construction from late 2026 and commercial operations in late 2030.
Carbon Capture Adds a New Dimension to Fertilizer Production
SAN-7 does not simply add ammonia and urea production. The complex will also incorporate a post-combustion carbon capture unit, with carbon capture integrated into the production system. SABIC Agri-Nutrients describes the technology as part of its efforts to reduce emissions intensity and strengthen the sustainability profile of its operations.
The relationship between ammonia and urea production makes carbon management particularly relevant. Captured carbon dioxide can form part of the urea production process, creating an opportunity to connect emissions management with fertilizer manufacturing.
This is increasingly relevant for international buyers as procurement teams examine not only product availability and pricing but also production characteristics and carbon-related requirements. A large new facility designed with carbon capture from the project stage can therefore have commercial relevance beyond its additional tonnes.
What SAN-7 Means for Ammonia and Urea Supply
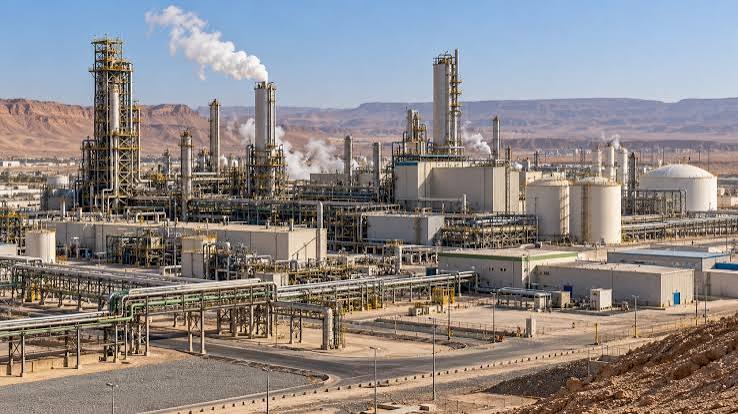
The additional production capacity could influence the future supply landscape for nitrogen fertilizers. The project is designed around 1.2 million tonnes per year of ammonia and 2.6 million tonnes per year of urea, creating a large integrated production platform.
For procurement managers, several implications deserve attention:
Greater Saudi production capacity: The expansion strengthens the country's ability to produce larger volumes of nitrogen fertilizer for domestic and international markets.
Long-term sourcing opportunities: Buyers can monitor the project as a potential future source when commercial production approaches.
Export relevance: Samsung E&A has stated that the fertilizer production is intended for export, increasing the project's importance to international trade flows.
Integrated production: Linking ammonia and urea production within one industrial complex can support coordinated feedstock and production operations.
The additional supply will not necessarily translate into a simple one-for-one change in global prices. Fertilizer pricing also depends on natural gas and feedstock economics, freight costs, crop demand, inventories, seasonal purchasing and production levels elsewhere.
Feedstock and Location Strengthen the Project’s Trade Position
SAN-7 is planned for Jubail Industrial City in Saudi Arabia’s Eastern Province, one of the Kingdom’s major industrial centers. SABIC Agri-Nutrients had already received approval for the feedstock allocation required for the project before reaching its final investment decision.
The location provides an established industrial environment for a large-scale chemical complex. For exporters, infrastructure and access to logistics networks can be just as important as production capacity when evaluating future supply availability.
Saudi Arabia already occupies an important position in global chemicals and fertilizer trade. Expanding production within an established industrial hub can therefore support additional export volumes once the new facility reaches stable commercial operation.
Procurement Risks Buyers Should Track Through 2030
The project is not expected to enter commercial production immediately. Buyers have several years before the planned fourth-quarter 2030 start, which makes timing one of the most important procurement considerations.
During this period, procurement teams should monitor:
Construction progress: Delays during engineering, equipment procurement or construction could affect the commissioning timeline.
Commissioning performance: Nameplate capacity does not automatically mean full commercial production from the first day of operation.
Global fertilizer balances: New Saudi capacity will enter a market that continues to change with production, agricultural demand and trade flows.
Freight economics: The commercial attractiveness of Saudi-origin fertilizer will vary across destination markets depending on shipping costs and regional supply.
Product specifications: Buyers should confirm the exact grade, packaging, loading terms and quality requirements before establishing long-term supply arrangements.
Maintaining diversified sourcing can also help buyers manage the gap between current requirements and future capacity additions. Existing suppliers remain important while SAN-7 moves from construction toward commercial operations.
How the Project Could Affect Global Fertilizer Trade
The international fertilizer market depends heavily on large-scale production centers because ammonia and urea require substantial industrial infrastructure. A project of SAN-7’s scale therefore has relevance beyond Saudi Arabia.
The 2.6 million tonnes per year of new urea capacity represents a sizeable addition to SABIC Agri-Nutrients’ production base. At the same time, the 1.2 million tonnes per year ammonia unit expands the upstream component needed to support nitrogen fertilizer production.
The project's export orientation could make Saudi Arabia an important source for buyers across multiple destination markets. However, actual trade flows will depend on commercial agreements, regional demand, freight economics and market conditions after the facility starts operating.
For traders, this creates an opportunity to monitor future availability well before the plant reaches commercial production. Early market intelligence can help buyers understand how additional Saudi volumes may fit into existing sourcing portfolios.
Looking Ahead to 2030: What Buyers Should Do Now
SAN-7 gives the fertilizer market a clear long-term capacity signal. SABIC Agri-Nutrients expects the project to raise its urea capacity from 4.8 million tonnes per year to 7.4 million tonnes per year, while adding 1.2 million tonnes per year of ammonia capacity.
For procurement teams, the most practical approach is to track the project through defined milestones rather than waiting for commercial production.
Key areas to monitor include:
EPC progress after construction begins in Q4 2026.
Equipment procurement and major construction milestones.
Commissioning progress expected from Q3 2030.
Commercial production targeted for Q4 2030.
Future export availability and destination-market opportunities.
Pricing relationships between Saudi-origin fertilizer and competing supply sources.
The project also highlights a broader trend in chemical procurement. Large fertilizer investments increasingly combine production scale with carbon management, while buyers continue to place greater emphasis on supply reliability, origin, logistics and long-term availability.
For traders and importers, following these developments early can provide better visibility into future nitrogen fertilizer supply. As SAN-7 progresses toward its planned 2030 completion, its additional ammonia and urea capacity will become an important factor in evaluating Saudi Arabia’s role in global fertilizer trade.
Ammonia Anhydrous
Found this useful?