Tariff and Origin Rules Continue Driving Nearshoring of Selected Chemical Supply Chains
Tariff and Origin Rules Continue Driving Nearshoring of Selected Chemical Supply Chains
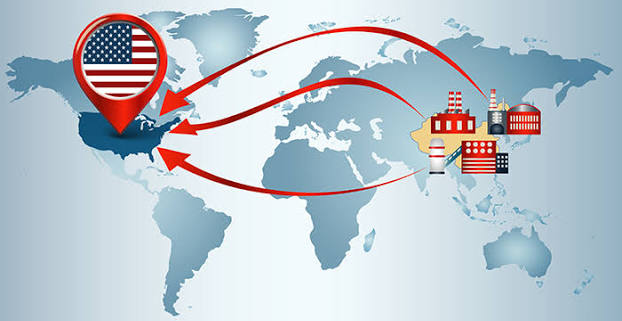
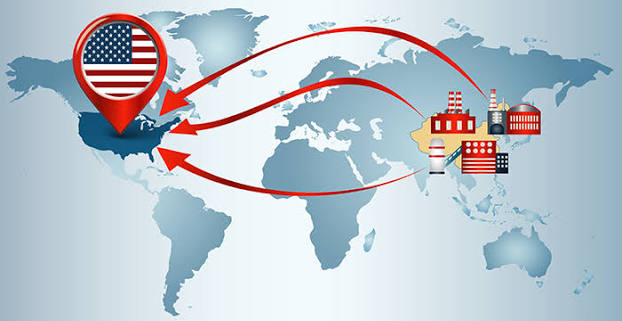
Trade policy has become a first-order variable in chemical supply-chain design. Layered tariffs, preferential origin requirements and customer or government mandates favoring domestic or allied sources are prompting buyers and producers to relocate or dual-source selected intermediates, additives and specialty grades closer to end markets. The trend is uneven—commodity molecules with broad global capacity move less readily than higher-value or regulated chemistries—but it is persistent enough to reshape investment, qualification and contracting decisions across multiple regions.
Nearshoring and friend-shoring respond to several overlapping pressures. Tariffs raise the landed cost of material from certain origins, sometimes decisively. Rules of origin attached to free-trade agreements or government procurement preferences require a minimum level of regional value content. Downstream customers, particularly in automotive, electronics, packaging and defense-related applications, increasingly write supply-chain resilience and geographic diversification into supplier scorecards. Together these factors make pure lowest-FOB sourcing less attractive for a growing list of products.
Where the Shift Is Most Visible
The effect is clearest in intermediates and specialties that combine meaningful tariff exposure with manageable technical barriers to relocation or dual qualification. Certain additives, performance chemicals, pharmaceutical intermediates and battery-related materials have seen accelerated qualification of North American, European, Mexican or other allied sources. In parallel, some Asian producers are investing in capacity inside preferential trade zones or partner countries to preserve access to Western markets under more favorable origin treatment.
Not every chemical chain is equally mobile. Large-scale commodity production remains anchored by feedstock advantage and existing infrastructure. Where molecules are tightly linked to specific process technologies or require extensive re-qualification, the transition is slower and more expensive. Even in those cases, however, buyers are often adding secondary origins or regional inventory hubs to reduce single-source and single-geography risk.
Implications for Investment and Procurement
Producers evaluating new capacity or debottlenecking now routinely model tariff and origin scenarios alongside traditional cost curves. Projects that can deliver qualifying origin status for key customer markets gain a strategic premium. Existing assets in high-tariff jurisdictions face greater pressure to justify their position through cost, quality or irreplaceable technology. Contract manufacturing and tolling arrangements in nearer or preferential locations have become more common bridging solutions.
For procurement teams, the practical work includes mapping current origin exposure, identifying tariff and rule-of-origin breakpoints, and expanding the pipeline of qualified regional suppliers. Total-cost models must incorporate duty, freight, inventory and risk premia rather than focusing solely on unit price. Longer-term agreements that secure capacity in preferred geographies are increasingly used to underwrite both supplier investment and buyer continuity.
Tariff and origin rules will not reverse global chemical trade, but they are selectively redirecting it. Nearshoring and friend-shoring of intermediates, additives and specialties have moved from contingency planning into active supply-chain strategy. Companies that treat trade-policy parameters as design inputs—rather than after-the-fact cost adjustments—will build more resilient and commercially durable sourcing networks for the remainder of the decade.
Aluminium Chloride
Found this useful?