Chemical Trade Intelligence: Using Import and Export Data to Identify Market Opportunities
Chemical Trade Intelligence: Using Import and Export Data to Identify Market Opportunities
Global Trade Shifts Creating New Opportunities
Five forecasts for global chemical markets in 2026 highlight key shift: I expect China to move fully into net-export territory for PP as self-sufficiency also rises in other chemicals and polymers. By end of 2026, consensus among producers will be no return to 1992-2021 operating rates during Chemicals Supercycle until 2032. But ICIS Supply and Demand Database suggests global ethylene operating rate of just 80% in 2036.
Chemicals in Q3 2026 what we are seeing in October 2026 shows chemicals total shareholder return rose 14% through mid-September 2026 compared with 10% for broader world index. Approximately 8 million metric tons per annum of global ethylene capacity came online from April through July 2026. China's lower petrochemical import requirement is limiting impact of supply constraints on Asian markets. China's net polyethylene imports fell by approximately 6 MTA on run-rate basis, showing self-sufficiency impact.
2026 Chemical Industry Outlook Deloitte notes new ethylene and polyethylene plants expected to start in 2026 in United States and Qatar where low-cost feedstocks usually available. United States is both major importer and exporter of chemicals, leaving sector highly sensitive to tariff shifts. US chemical imports spiked to over 20 billion dollars in March 2025, highest in over three years, before dropping to 17 billion in April, illustrating volatility.
Middle East grabbed more than 40% of global polyethylene exports in year 2025 according to Reuters, showing concentration of export power in low-cost feedstock regions.
Import And Export Data Reveals Regional Imbalances
Chemicals trends summary report provides snapshot of chemical industry performance in 27 countries of European Union based on data released by Eurostat. Basic chemicals sales down 23% and driven largely by weaker sales to United States down 29%. Although EU27 maintained substantial chemical trade surplus in value terms 18.4 billion euros in H1 2026, it narrowed as exports fell faster than imports. In volume terms, trade deficit improved by 3.7 million tonnes as imports declined.
Cefic Chemical Trends Report Q1 2026 shows EU27 chemical industry weak demand and high energy costs delay recovery. In first quarter 2026, chemical production declined by 3.2% year on year highlighting fragility. EU27 chemical trade weakened markedly in early 2026 with exports falling by 4.6 billion euros 12.4% and imports declining even more sharply by 4.8 billion euros 15.7%, reflecting softer external demand and contraction in domestic industrial activity.
Cefic Chemical Trends Report Q3 2026 shows EU27 chemical industry remains under pressure despite improving confidence. Production declined by 2.0% between January and July 2026 compared to 2025, demand weak, structural competitiveness pressures intensified. Trade performance weakened between January and July, export values fell by 4.2% and imports by 3.1%, reducing extra-EU27 chemical trade surplus by 2.2 billion euros to 21.4 billion.
Singapore chemical logistics market valued at 3.9 billion in 2025 and projected to grow from 4.07 billion in 2026 to 5.01 billion by 2031, CAGR of 4.23% during 2026-2031 forecast period, supported by rising specialty-chemical re-exports, advanced port automation, certified storage demand and expanding pharmaceutical logistics requirements. Enterprise Singapore recorded SGD 91.5 billion equivalent to 68.6 billion dollars in chemicals trade.
Emerging Market Opportunities From Trade Data
Southeast Asia organic chemicals export market experiencing period of unprecedented growth. According to Alibaba platform data, category Other Organic Chemical ID 80312 has seen buyer count skyrocket by 181.07% year-over-year. Demand index for Food Additives and Water Treatment Chemicals two key end-uses for organic acids has grown by 35.2% and 28.7% quarter-over-quarter respectively, indicating strong downstream opportunity.
Egyptian chemical exports to China surged 678% year on year to 287 million dollars during first eight months of 2026, up from 37 million same period last year, according to data from General Organization for Export and Import Control GOEIC. Sector top 10 export markets collectively accounted for 56% of total, showing concentration but also growth potential in China link.
On 15 October, Covestro unveiled plans to scale back polycarbonate manufacturing at Antwerp facility, reducing number of operating production lines from four to one, while phasing out bisphenol-A BPA production at site. That capacity closure in Europe creates import opportunity for low-cost producers and for specialty alternatives.
Global chemical industry outlook 2026 oversupply regional competition and new era of strategic sourcing notes according to European Chemical Industry Council Cefic EU27 chemical production declined by 2.0% January to July 2026 compared same period 2025. That decline opens gap for imports but also signals need for European buyers to diversify.
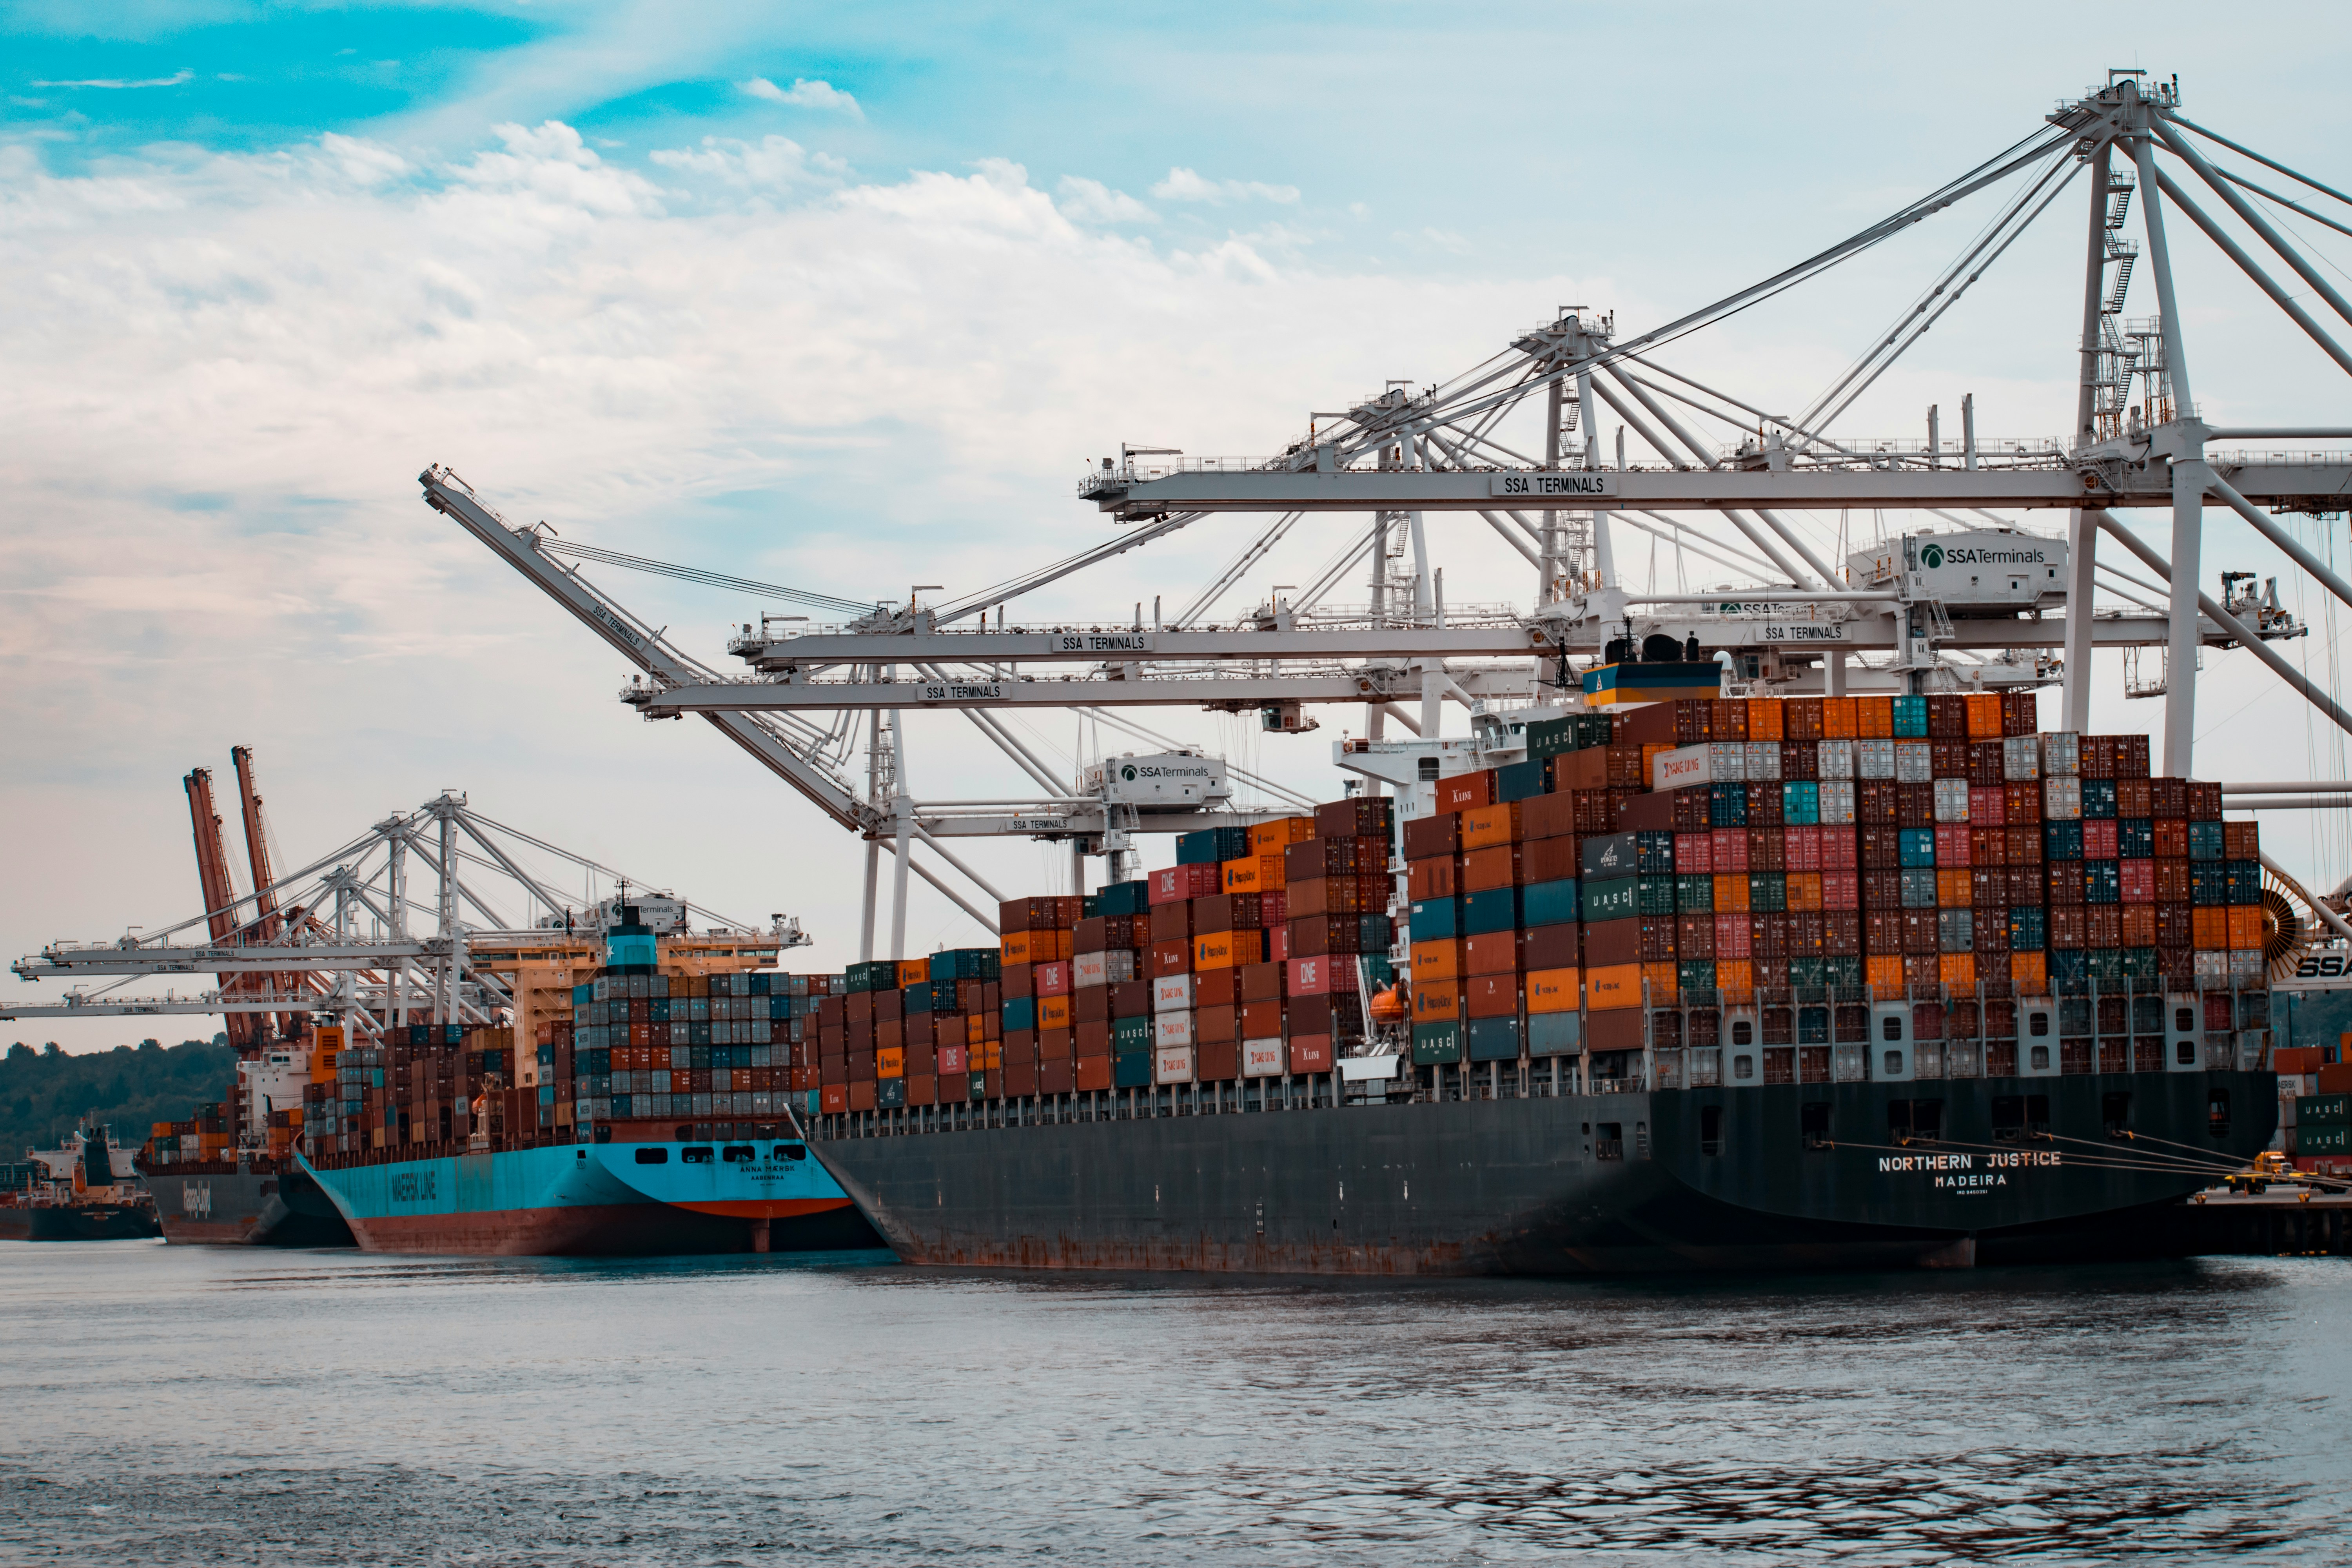
How To Use Trade Data For Market Intelligence
Import and export data analysis involves tracking several layers: volume trends, value trends, unit prices, origin-destination shifts, and product grade mix. For food-grade minerals, that means tracking HS codes for zinc sulfate 2833.29, ferrous fumarate 2915.12, calcium carbonate 2836.50, with 12-digit precision now required in GCC countries since January 1 2025.
Key approaches include monitoring China self-sufficiency ratios, as China moving to net-export territory for PP indicates oversupply pressure that will depress global prices and create buying opportunities. Monitoring EU trade surplus narrowing as exports fell faster than imports indicates weaker external demand, signaling potential for lower prices but also supply risk if European plants close.
Tracking polyethylene export share Middle East over 40% shows low-cost feedstock advantage remains decisive. For buyers, that means sourcing from Middle East or US Gulf Coast offers cost advantage, but freight and geopolitical risk must be factored. Shanghai Containerized Freight Index 231% higher year-on-year adds to landed cost, offsetting some feedstock advantage.
Analyzing buyer count growth 181% for organic chemicals in Southeast Asia indicates emerging demand hotspots. Food additives demand index up 35.2% indicates nutrition and fortification growth, supporting demand for zinc sulfate monohydrate, ferrous fumarate, and calcium carbonate GCC for fortified foods.
Food-Grade And Specialty Opportunities
Food and beverage segment expected to have highest CAGR during forecast period, with food grade minerals market valued at 5.6 billion dollars in 2025 projected toward 15 billion. Import data shows demand for FCC grade minerals growing faster than technical grade, with compliance requirements GFSI certification FSSC 22000, Halal, Kosher, heavy metal limits becoming trade barriers that create premium for compliant suppliers.
Trade intelligence for specialty chemicals shows conventional specialty chemicals still dominate, yet next-generation products designed for electric mobility, advanced electronics, digital applications rapidly gaining traction. Market covers specialty polymers, electronic chemicals, construction chemicals, agrochemicals, personal care ingredients, water treatment chemicals, coatings additives, adhesives, sealants, surfactants.
Sustainable chemistry creates trade opportunity, with bio-based feedstock adoption reaching 9% of new projects. Concrete admixtures with calcium carbonate derivatives demonstrated up to 20% reduction in carbon footprint. Brands using blockchain-tracked GCC report 19% higher purchase intent in climate-conscious demographics. That sustainability premium can be captured through export data showing which markets pay premium for low-carbon certified materials.
Weekly chemical market tracker update October 12-19 2026 notes Middle East grabbed more than 40% of global polyethylene exports, indicating concentration risk but also opportunity for alternative suppliers like US and Qatar with low-cost feedstocks where new plants expected to start in 2026.
Practical Strategies For Buyers
Chemical trade intelligence best used with layered planning. Separate raw material trend from conversion trend, track four decision signals input trend, lead-time movement, supplier capacity discipline, compliance friction, and build tiered budgets with base, pressure, and disruption cases.
For import-dependent markets like India, Southeast Asia, Africa, tracking China FOB prices versus local landed costs helps identify arbitrage. For example, sodium bicarbonate China FOB 177.78 dollars MT versus Europe 0.46 dollars per kg shows spread, titanium dioxide China 2,003 dollars MT versus Germany 3,650 dollars MT shows similar.
Require landed-cost comparison not ex-works only, as freight and fuel surcharges have become revenue lever for carriers, with LTL rate per pound index expected to reach 82.5% above January 2018 baseline. Focus on new HS codes and compliance friction, as 12-digit codes and precision tariffs add fixed costs.
Companies reassessing supply chains prioritizing resilience alongside cost efficiency will accelerate regionalization trends, encourage investment in integrated production hubs, and increase strategic importance of countries with secure energy and feedstock access. That shift creates opportunities for suppliers in regions with secure gas, renewable energy, and limestone reserves.
Ultimately, chemical trade intelligence using import and export data reveals market opportunities by tracking China net-export shifts, EU production decline and trade surplus narrowing, Southeast Asia organic chemicals buyer growth 181%, Egyptian exports to China surge 678%, and polyethylene export concentration Middle East 40%. Buyers who monitor volume, value, unit price, origin-destination, and grade mix will identify arbitrage, supply risks, and emerging demand ahead of competitors.
Sources:
Five Forecasts for Global Chemical Markets in 2026 – ICIS – China to move fully into net-export territory for PP – no return to 1992-2021 operating rates until 2032 – ethylene operating rate 80% 2036 – https://icis.com
Cefic Chemical Trends Report Q1 2026 – EU27 exports falling 4.6bn 12.4% imports 4.8bn 15.7% – https://cefic.org
Chemicals in Q3 2026 Where industry stands – McKinsey – chemicals TSR rose 14% – 8M MTA ethylene capacity online April-July 2026 – China net PE imports fell 6 MTA – https://mckinsey.com
Borax Anhydrous (Technical Grade) - Turkey
Found this useful?