Europe’s Airlines Are Buying More Sustainable Aviation Fuel Than Required
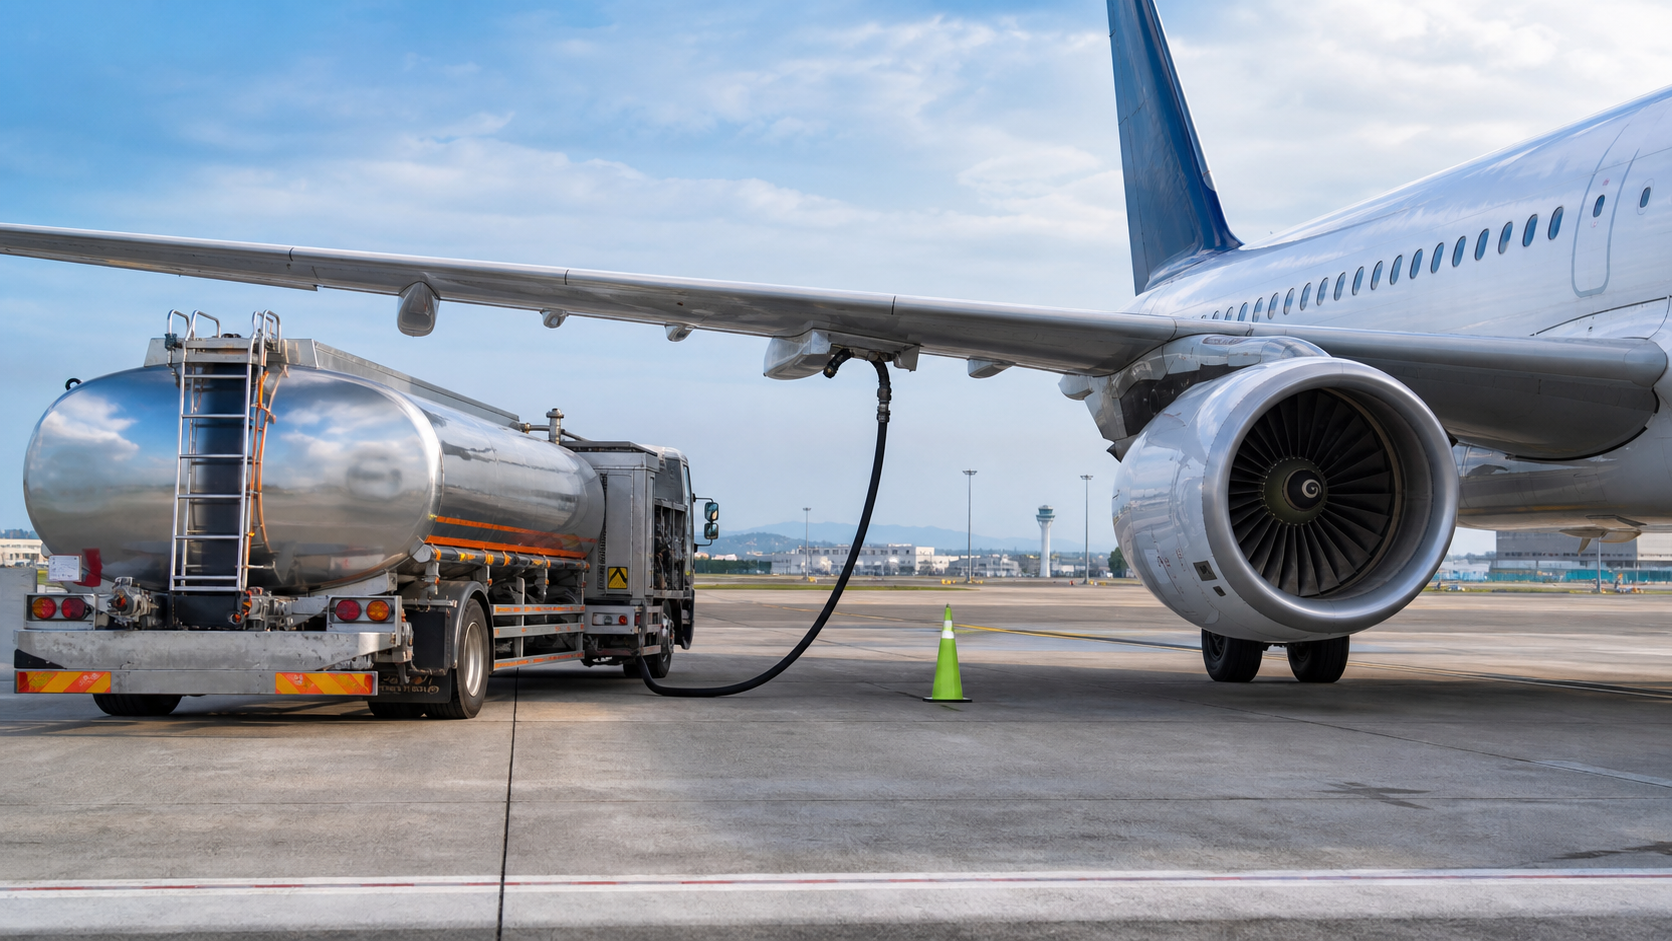
Europe’s aviation industry is showing stronger demand for sustainable aviation fuel (SAF) than regulatory minimums alone would suggest. EASA reported that actual EU SAF supply exceeded the mandated 2025 ReFuelEU blending target ahead of schedule, indicating that airlines and fuel buyers are already moving beyond compliance-driven purchasing.
That shift matters across the wider chemical and energy trading ecosystem. Higher SAF demand can influence feedstock procurement, refining capacity, certification requirements, logistics planning and long-term supply agreements as European aviation works toward progressively higher blending requirements.
ReFuelEU Is Changing the European Aviation Fuel Market
The ReFuelEU Aviation framework establishes minimum SAF requirements for aviation fuel supplied at EU airports. These requirements are designed to increase gradually, giving airlines, fuel suppliers and producers a clear pathway toward greater use of lower-carbon aviation fuels.
The fact that actual SAF supply moved above the 2025 requirement signals that the market is developing faster than a purely compliance-based model would suggest.
For procurement teams, this creates an important distinction. Regulatory demand sets a floor, while commercial demand can move above that floor when airlines pursue emissions targets, corporate sustainability commitments and longer-term fuel strategies.
Why Airlines Are Buying More SAF
Airlines face increasing pressure to reduce the emissions associated with air travel while maintaining reliable fuel supply. SAF provides one of the principal pathways available to reduce lifecycle emissions without requiring the entire commercial aviation fleet to transition to a completely different propulsion system.
Several factors are supporting stronger purchasing activity:
Regulatory requirements are establishing a growing baseline for SAF consumption across European aviation.
Corporate climate commitments encourage airlines to secure additional lower-carbon fuel beyond mandatory volumes.
Passenger and investor expectations are increasing attention on aviation emissions and sustainability performance.
Fuel procurement strategies are shifting toward longer-term agreements that can provide greater supply visibility.
Producer investment is expanding the range of SAF production pathways and available supply.
For traders and suppliers, these drivers indicate that SAF should not be viewed only as a regulatory product. It is becoming a strategic component of aviation fuel procurement.
SAF Supply Is Becoming a Procurement Priority
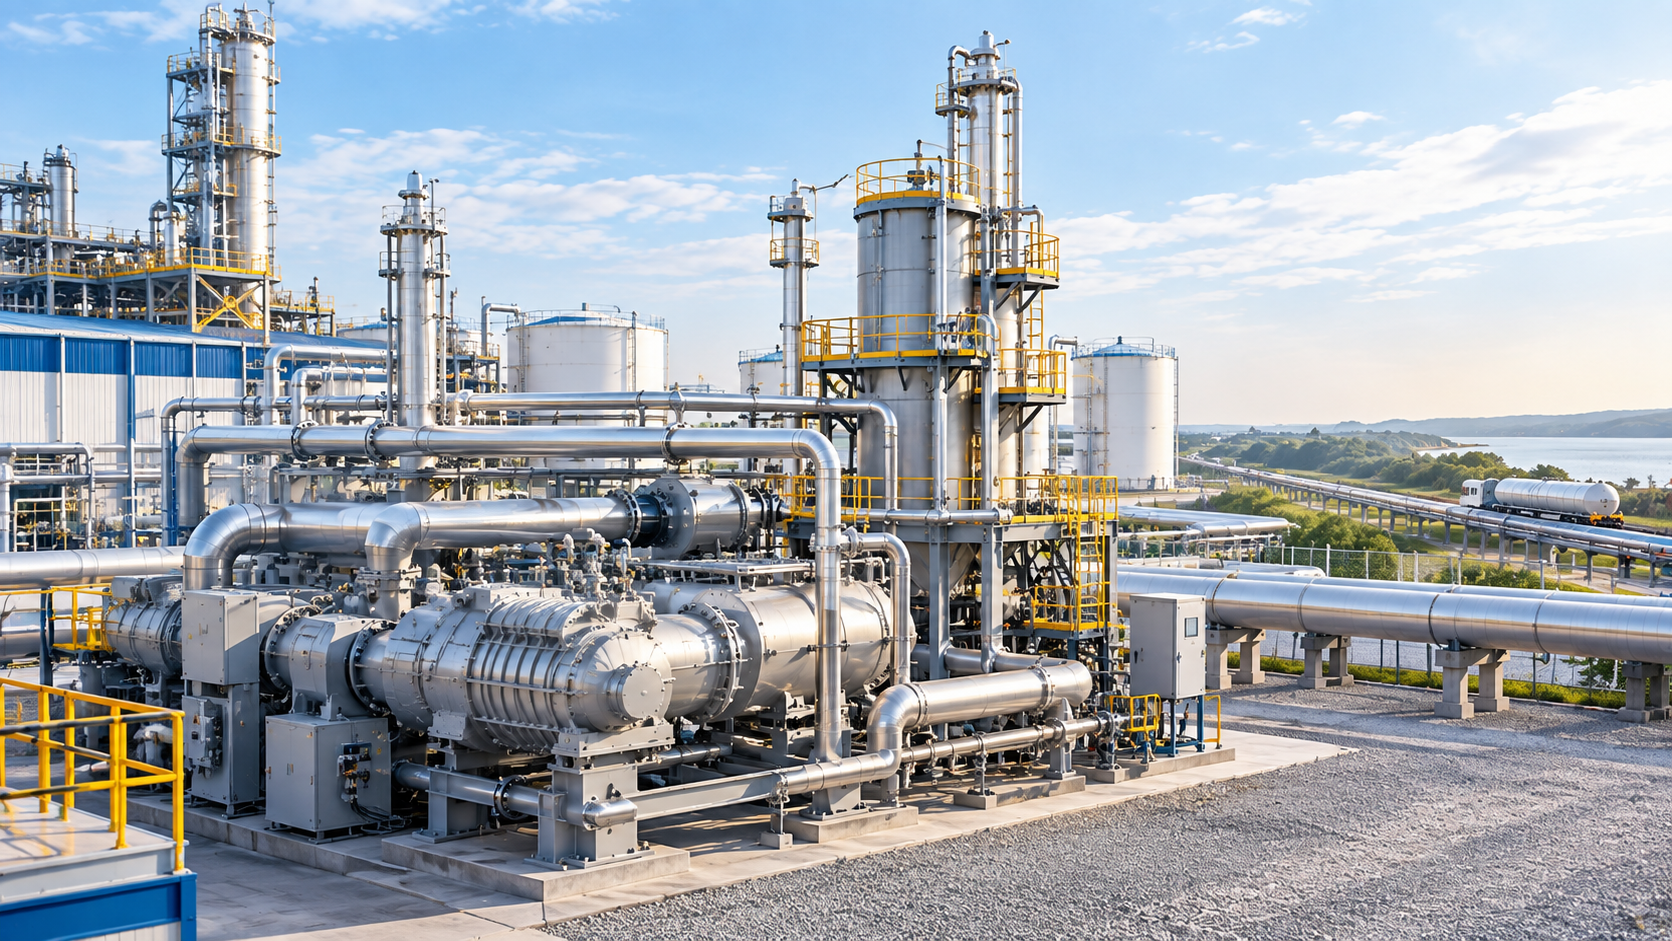
The European SAF market connects several industries that traditionally operated across different parts of the energy and chemical supply chain. Feedstock providers, chemical processors, fuel producers, logistics companies, certification specialists and airlines all play roles in getting compliant SAF to the airport.
Supply availability therefore depends on more than production capacity. Buyers also need to consider feedstock origin, sustainability characteristics, production technology, certification status and delivery infrastructure.
A procurement team evaluating SAF suppliers should pay particular attention to:
Feedstock availability, because competing demand can affect both cost and supply security.
Production pathway, since different technologies can have different technical and sustainability characteristics.
Certification and traceability, which support compliance and purchasing requirements.
Contract structure, particularly when airlines want predictable volumes over multiple years.
Logistics capacity, including storage, blending and airport delivery arrangements.
The Supply Chain Behind Sustainable Aviation Fuel
SAF does not represent a single chemical product with one universal production route. Producers can use different feedstocks and conversion technologies to manufacture fuels suitable for aviation applications.
This diversity creates opportunities for chemical traders and raw material suppliers while also introducing additional procurement complexity.
Common SAF feedstock categories can include waste-derived oils and fats, agricultural residues and other carbon-based materials suitable for approved production pathways. The availability and quality of these inputs can directly affect production economics.
For international traders, this means SAF sourcing increasingly requires visibility across the upstream chain. A buyer may need to evaluate not only the fuel producer but also the origin and characteristics of the feedstock supporting production.
What Higher SAF Demand Means for Traders
When demand grows faster than mandatory requirements, suppliers gain a stronger incentive to expand production and secure feedstock.
This can create new trading opportunities across several points of the supply chain. Chemical and energy traders with established relationships in feedstocks, specialty chemicals, refining inputs and industrial logistics may be well positioned to participate.
The market can also encourage more long-term procurement arrangements. Instead of relying entirely on spot purchases, airlines and fuel suppliers may seek structured contracts that provide predictable volumes and pricing mechanisms.
For exporters, Europe represents a particularly important destination because regulatory requirements create a defined long-term demand trajectory. However, access to this market depends heavily on meeting applicable sustainability and certification requirements.
Pricing Will Depend on More Than Conventional Jet Fuel
SAF pricing cannot be evaluated solely against conventional aviation fuel. Production pathways, feedstock costs, availability, processing requirements and sustainability attributes all influence the economics of the final product.
Higher demand can place pressure on available feedstocks, particularly where multiple industries compete for the same raw materials. At the same time, expanding production capacity can gradually improve supply availability and create more competitive sourcing options.
Procurement teams should therefore assess SAF offers using a broader commercial framework:
Delivered fuel cost, rather than production price alone.
Available volume, including guaranteed and optional quantities.
Feedstock and pathway characteristics, where relevant to purchasing requirements.
Certification and sustainability documentation.
Delivery schedule and logistics capabilities.
Contract flexibility, particularly for long-term supply agreements.
This approach can provide a more realistic picture of the commercial value of competing offers.
Europe’s SAF Demand Creates Opportunities for Global Suppliers
The European market can influence global SAF investment because producers often evaluate projects according to where long-term demand is most predictable.
European requirements can therefore support investment in production facilities, feedstock collection networks and associated logistics infrastructure outside the EU as well.
For suppliers targeting European buyers, market access depends on building a supply proposition around consistency and documentation rather than simply offering fuel volumes. Buyers need confidence that products can meet their technical, regulatory and sustainability requirements throughout the procurement cycle.
This also creates opportunities for specialist traders that can connect producers with buyers while managing international logistics, documentation and commercial negotiations.
Procurement Teams Need a Longer-Term SAF Strategy
The early achievement of the 2025 blending target provides an important signal for aviation fuel buyers. Procurement strategies based only on minimum regulatory obligations may not capture the pace at which the market is developing.
Airlines and fuel distributors can strengthen their position by monitoring both regulatory requirements and actual purchasing behavior.
A practical procurement strategy should include:
Building relationships with multiple qualified SAF suppliers rather than depending on one source.
Tracking feedstock markets that can affect SAF availability and pricing.
Reviewing certification and traceability documentation before finalizing contracts.
Evaluating multi-year supply agreements where predictable volumes provide commercial advantages.
Monitoring new production capacity and emerging SAF technologies.
Maintaining flexibility around delivery locations and logistics routes.
Early engagement can become increasingly valuable as more buyers compete for available sustainable fuel volumes.
Looking Ahead to 2027 and Beyond
Europe’s SAF market is entering a phase where regulatory targets and actual market demand can reinforce each other. The fact that supply already exceeded the mandated 2025 ReFuelEU blending target suggests that some participants are preparing for a market that extends beyond minimum compliance.
For chemical traders, exporters and procurement managers, the opportunity lies in understanding the entire value chain. Feedstocks, production technology, certification, transportation and long-term contracting will all influence how efficiently SAF reaches European aviation customers.
As requirements increase, buyers that establish diversified supply relationships early can gain greater visibility into availability and pricing. Suppliers that can provide reliable volumes with strong documentation will be better positioned to serve a market where sustainability is becoming a commercial procurement requirement, not simply a regulatory obligation.
Ready to source Sustainable Aviation Fuel from verified global suppliers? Explore competitive offers on our platform today.
Source:
Methanol
Found this useful?