European Chemical Plant Closures: The Structural Economics Behind the Numbers
European chemical manufacturers entered 2026 facing a business environment that has become increasingly difficult to sustain. A growing number of plant closure announcements attracted industry attention, but the announcements themselves tell only part of the story. The larger issue lies in the structural economics that continue to challenge European producers even when energy markets or crude oil prices temporarily improve.
For procurement professionals, understanding these long-term cost drivers is more valuable than simply following headlines. If the current wave of closures reflects a permanent shift in global competitiveness rather than a short-term market correction, sourcing strategies may need to evolve accordingly.
Why Europe Faces a Structural Competitive Challenge
Chemical manufacturing depends on three major factors, feedstock costs, energy costs and operating efficiency.
European producers continue facing disadvantages across several of these areas. Higher natural gas and electricity prices, complex regulatory requirements and weaker downstream industrial demand have combined to reduce operating margins for many commodity chemical plants.
At the same time, producers in North America and the Middle East benefit from more competitive feedstocks and lower energy costs, allowing them to manufacture many bulk chemicals at a lower overall production cost.
These structural differences influence investment decisions far more than temporary market fluctuations.
The Economics of Naphtha Crackers Versus Ethane Crackers
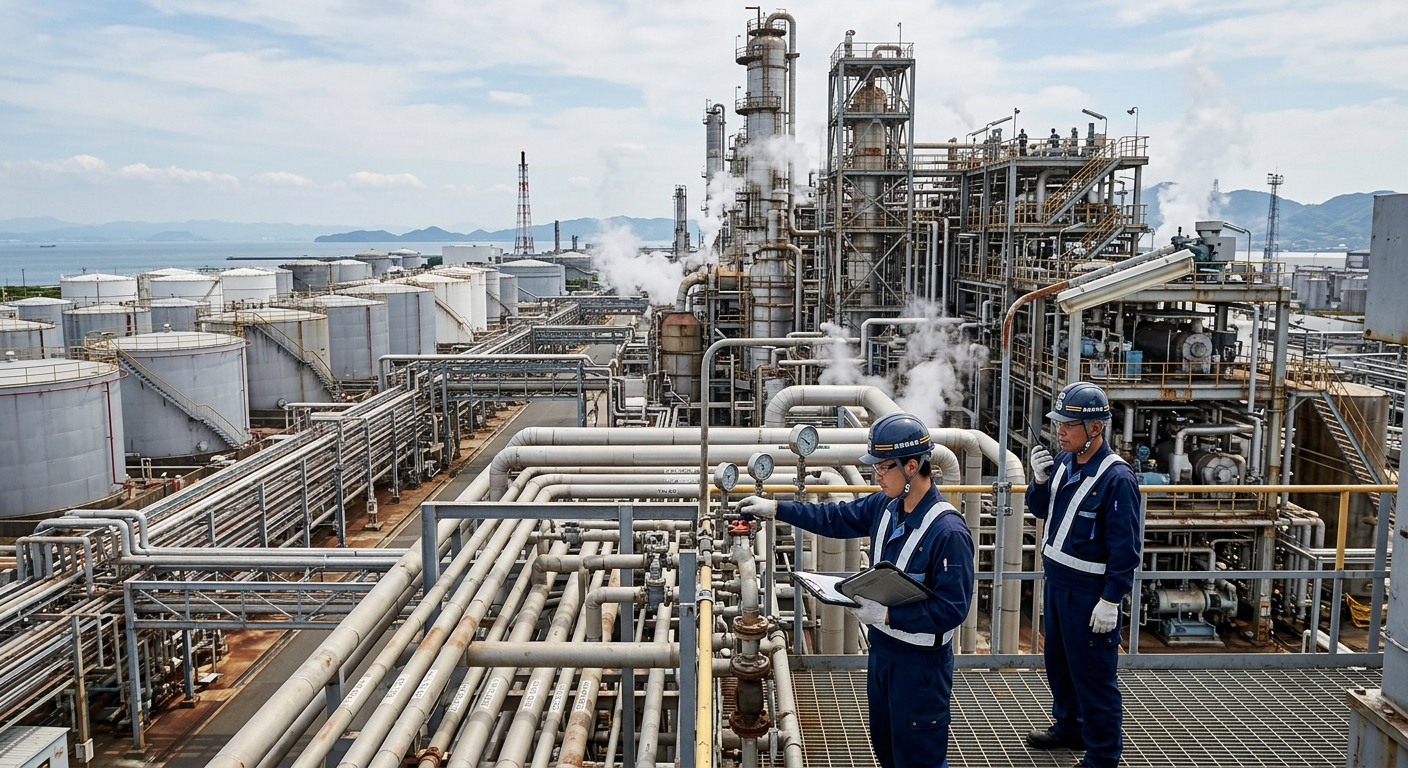
One of the clearest examples of structural cost differences appears in steam cracking.
Many European petrochemical facilities rely on naphtha as their primary feedstock. In contrast, numerous US producers operate ethane crackers supported by abundant natural gas resources.
Although exact production costs vary between facilities and market conditions, the structural relationship remains consistent.
Ethane cracking generally benefits from:
Lower feedstock costs.
Reduced energy consumption for key production stages.
Higher competitiveness when natural gas prices remain favourable.
European naphtha crackers face comparatively higher costs per tonne because feedstock economics and energy inputs remain less favourable, even during periods when crude oil prices soften.
Why Lower Crude Oil Prices Do Not Eliminate the Gap
Many buyers assume that falling oil prices automatically improve European competitiveness.
The reality is more complex.
Naphtha prices may decline alongside crude oil, yet several structural disadvantages remain unchanged. Electricity, natural gas, labour expenses and regulatory compliance continue representing significant components of total production costs.
Even if crude prices weaken, European manufacturers still operate within a higher-cost environment than many competitors.
This explains why temporary improvements in feedstock pricing rarely remove the broader competitiveness gap.
Regulatory Requirements Increase Operating Costs
European producers also operate within one of the world's most comprehensive regulatory environments.
Requirements under REACH, environmental permitting processes and broader sustainability obligations contribute to additional administrative and operational expenses throughout the life of a manufacturing facility.
These obligations support high environmental and safety standards, yet they also increase the cost of maintaining and expanding production assets.
For investment decisions, companies evaluate these regulatory costs alongside feedstock and energy economics when determining whether facilities remain commercially viable.
Weak Downstream Demand Adds More Pressure
Cost competitiveness represents only one side of the equation.
Demand from major European manufacturing sectors has also softened, particularly across construction and automotive industries in Germany.
Lower downstream activity reduces demand for many commodity chemicals, creating additional pressure on plant utilisation rates.
When producers face both weaker demand and higher operating costs, maintaining full production becomes increasingly difficult.
Chinese Capacity Expansion Reshapes Global Competition
Another important factor comes from outside Europe.
Large-scale chemical capacity additions in China continue increasing global supply across several commodity markets.
Greater production capacity creates stronger competition for export markets and places additional pressure on international pricing.
European producers therefore compete not only against domestic market conditions but also against suppliers operating in regions with different cost structures and expanding production capacity.
For procurement teams, this global perspective is essential when evaluating future supply availability.
Temporary Adjustment or Permanent Capacity Reduction?
One of the most important questions for buyers is whether current plant closures represent a short-term response or a lasting structural change.
Several indicators suggest that capacity rationalisation extends beyond temporary market weakness.
These include:
Continued investment in lower-cost production regions.
Persistent energy cost differences between Europe and competing markets.
Ongoing regulatory complexity affecting new investment.
Slower recovery in major downstream industries.
Global competition from recently commissioned production facilities.
Together, these factors indicate that some production capacity may not return even if market demand improves.
Procurement Implications for Chemical Buyers
Plant closures should not be viewed as isolated news events.
Instead, procurement teams should evaluate whether structural economics are changing the long-term geographic distribution of chemical manufacturing.
A stronger sourcing strategy includes:
Monitoring production investment outside Europe.
Diversifying supplier portfolios across multiple regions.
Evaluating long-term manufacturing competitiveness rather than short-term pricing.
Assessing supplier resilience alongside production capacity.
Planning alternative sourcing options for strategically important raw materials.
These actions improve supply security in an industry where production geography continues evolving.
What Buyers Should Watch Beyond 2026
The economics behind European chemical plant closures extend well beyond current market conditions. Feedstock advantages, energy pricing, regulatory obligations and global competition continue influencing where future investment is most likely to occur.
Procurement professionals who understand these structural drivers will be better prepared to distinguish temporary production interruptions from permanent capacity reductions. That perspective supports stronger sourcing decisions, improved supply continuity and more resilient procurement strategies. Ready to source industrial chemicals from verified global suppliers? Explore competitive offers on our platform today.
Ethyl Acetate
Found this useful?