European Steam Cracker Rationalization Tightens Regional Olefin and Derivative Supply
European Steam Cracker Rationalization Tightens Regional Olefin and Derivative Supply
Europe’s steam cracker fleet continues to contract under the weight of high energy costs, elevated naphtha-linked feedstocks and prolonged periods of weak margins. Between historic mothballing and a concentrated wave of shutdowns announced or executed from 2024 through 2027, several million tonnes of annual nameplate ethylene capacity have been removed or scheduled for removal. The result is a structurally smaller regional production base, tighter local balances for ethylene, propylene and associated co-products, and greater reliance on remaining efficient assets plus imports of both monomers and derivatives.
Utilization rates at surviving Western European crackers have frequently run well below preferred levels. Producers have responded with permanent closures of older, higher-cost units, extended turnarounds and selective rate cuts. Each closure reduces not only ethylene availability but also the accompanying slate of propylene, C4s, pygas and other intermediates that feed regional derivative chains. Downstream units that once relied on integrated or nearby cracker supply must increasingly secure merchant volumes or imported material.
Capacity Exit and the Changing Supply Map
The rationalization has been front-loaded. A substantial share of the announced reductions falls in the 2024–2026 window, shrinking Europe’s merchant naphtha-cracking footprint more quickly than new low-carbon or feedstock-advantaged projects can offset. While selected investments—such as ethane-based capacity under development—will add modern tonnes later in the decade, the near-term arithmetic is one of net capacity loss. Derivative markets feel the effect through reduced local availability of polyethylene, ethylene oxide/glycols, styrene precursors and other first-line products, even when global markets remain well supplied.
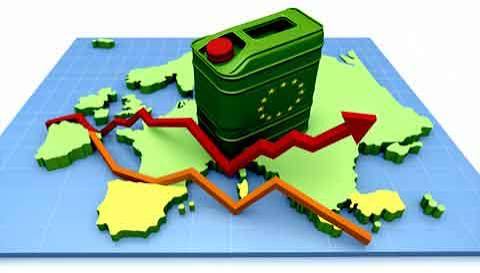
Energy and carbon costs remain central to the economics. European crackers operate with structurally higher variable costs than gas-advantaged peers in North America or some Middle Eastern producers. When downstream demand is only moderate, the margin incentive to keep marginal capacity running disappears, accelerating closure decisions. Policy and sustainability pressures add further weight to the case for retiring the least efficient assets.
Implications for Buyers and Trade Flows
For European consumers of olefins and derivatives, the tighter regional supply translates into a narrower set of local options, potentially longer lead times and a higher proportion of imported material in the supply mix. Procurement strategies are adjusting: more emphasis on multi-origin contracts, greater attention to logistics reliability from the US Gulf Coast, Middle East and Asia, and closer monitoring of turnaround calendars at the remaining European crackers. Price relationships between regional contract markets and import parity have become more sensitive to each incremental closure or extended outage.
Integrated producers with competitive remaining assets or strong downstream positions are relatively better placed. Stand-alone derivative operators and smaller buyers face a more complex supply environment and may need to accept higher baseline costs or reduced flexibility. Over time, the rationalization supports a re-balancing of European olefins toward a smaller, more competitive core of production supplemented by trade—an outcome already visible in rising import dependence for several derivative chains.
European steam cracker rationalization is not a temporary cyclical adjustment; it is a structural response to cost and margin realities. As capacity continues to exit, regional olefin and derivative supply will remain tighter than in the previous decade, making secure, diversified sourcing an enduring priority for downstream chemical and polymer buyers.
Modified Corn Starch (E1442)
Found this useful?