Global Fertilizer Industry Report: Production, Consumption and Trade Analysis
Global Fertilizer Industry Report: Production, Consumption and Trade Analysis
Market Size And Industry Structure
The global fertilizer market size is predicted to increase from 220.31 billion dollars in 2026 to approximately 284.58 billion by 2035, expanding at CAGR of 2.89% over forecast period from 2026 to 2035. Global fertilizer trade recorded 725 shipments between June 2026 and May 2026, a 2% year-over-year increase, involving 96 verified exporters and 174 buyers. US completed 19,976 shipments, China 19,325 and Spain 17,153, placing them among top traders.
Global fertilizer market was valued at 148 billion in 2025, is projected to reach 173 billion in 2026, and is expected to expand at 2.1% CAGR from 2026 to 2035, reaching 183 billion by 2035. Market covers manufacturer-level production, trade, and consumption of nitrogenous, phosphatic, and potassic fertilizers, as well as complex and specialty nutrient products used across commercial agricultural systems.
Global fertilizer market size valued at 187.9 billion in 2025. Looking forward, IMARC Group estimates market to reach 248.0 billion by 2034, exhibiting CAGR of 3.04% from 2026-2034, with global fertilizer nutrient consumption reaching 206 million metric tons in recent periods. Global fertilizer market estimated to be valued at 195.43 billion in 2026 and expected to reach 247.47 billion by 2033, exhibiting CAGR of 3.4% from 2026 to 2033. Nitrogen fertilizers segment expected to account for 26.7% of global fertilizer market in 2026, driven by essential role in improving crop yield and soil fertility.
Global agriculture fertilizers market size accounted for 230.84 billion in 2025, and anticipated to hit 239.38 billion by 2026, and predicted to reach around 317.79 billion by 2035, growing at CAGR of 3.65% from 2025 to 2034. International trade has approximately 1.8 million shipments per year.
Global Production Analysis
Global production around 235 million metric tonnes, according to 2026 Q2 report key events analysis. Strait of Hormuz exposed fertilizer's reliance on concentrated supply. Global demand around 190 million metric tonnes, abundant production means little when logistics disrupted.
Global consumption heavily concentrated, with China 42 million tons, India 37 million tons, and United States 34 million tons accounting for combined 33% of world demand in 2024. Demand met by production base led by China 64 million tons, Russia among top producers.
After reaching record 207 million tonnes in 2024, growth in global fertilizer consumption slowed, with fertilizer market update reviews global fertilizer production exceeding 190 million tonnes annually, trade data extending to April 2026, price data through May 2026.
China recorded strong export growth across three major nitrogen fertilizer products in September 2026. September exports 2.45 million MT, up 78.7% year-on-year, setting new monthly record. During April to September 2026, India's urea imports reached 5.59 million MT, increase of 40.5% year-on-year, showing India's dependence on imports despite domestic capacity.
Before conflict, approximately one-third of global nitrogen fertilizer trade, including urea and ammonia, as well as sulfur used in phosphate fertilizer production, passed through Strait of Hormuz. That concentration explains why Middle East conflict triggered severe disruptions in energy supply chains and fertilizer pricing.
China imported approximately 140,900 MT of sulfur in September 2026, decrease of 82.2% year-on-year, while China imported 2.9186 million MT of sulfur in January-August 2026, down 59.56% year on year. August imports totaled 272,300 MT, falling 29.35% month on month, indicating reduced phosphate production or alternative sourcing.
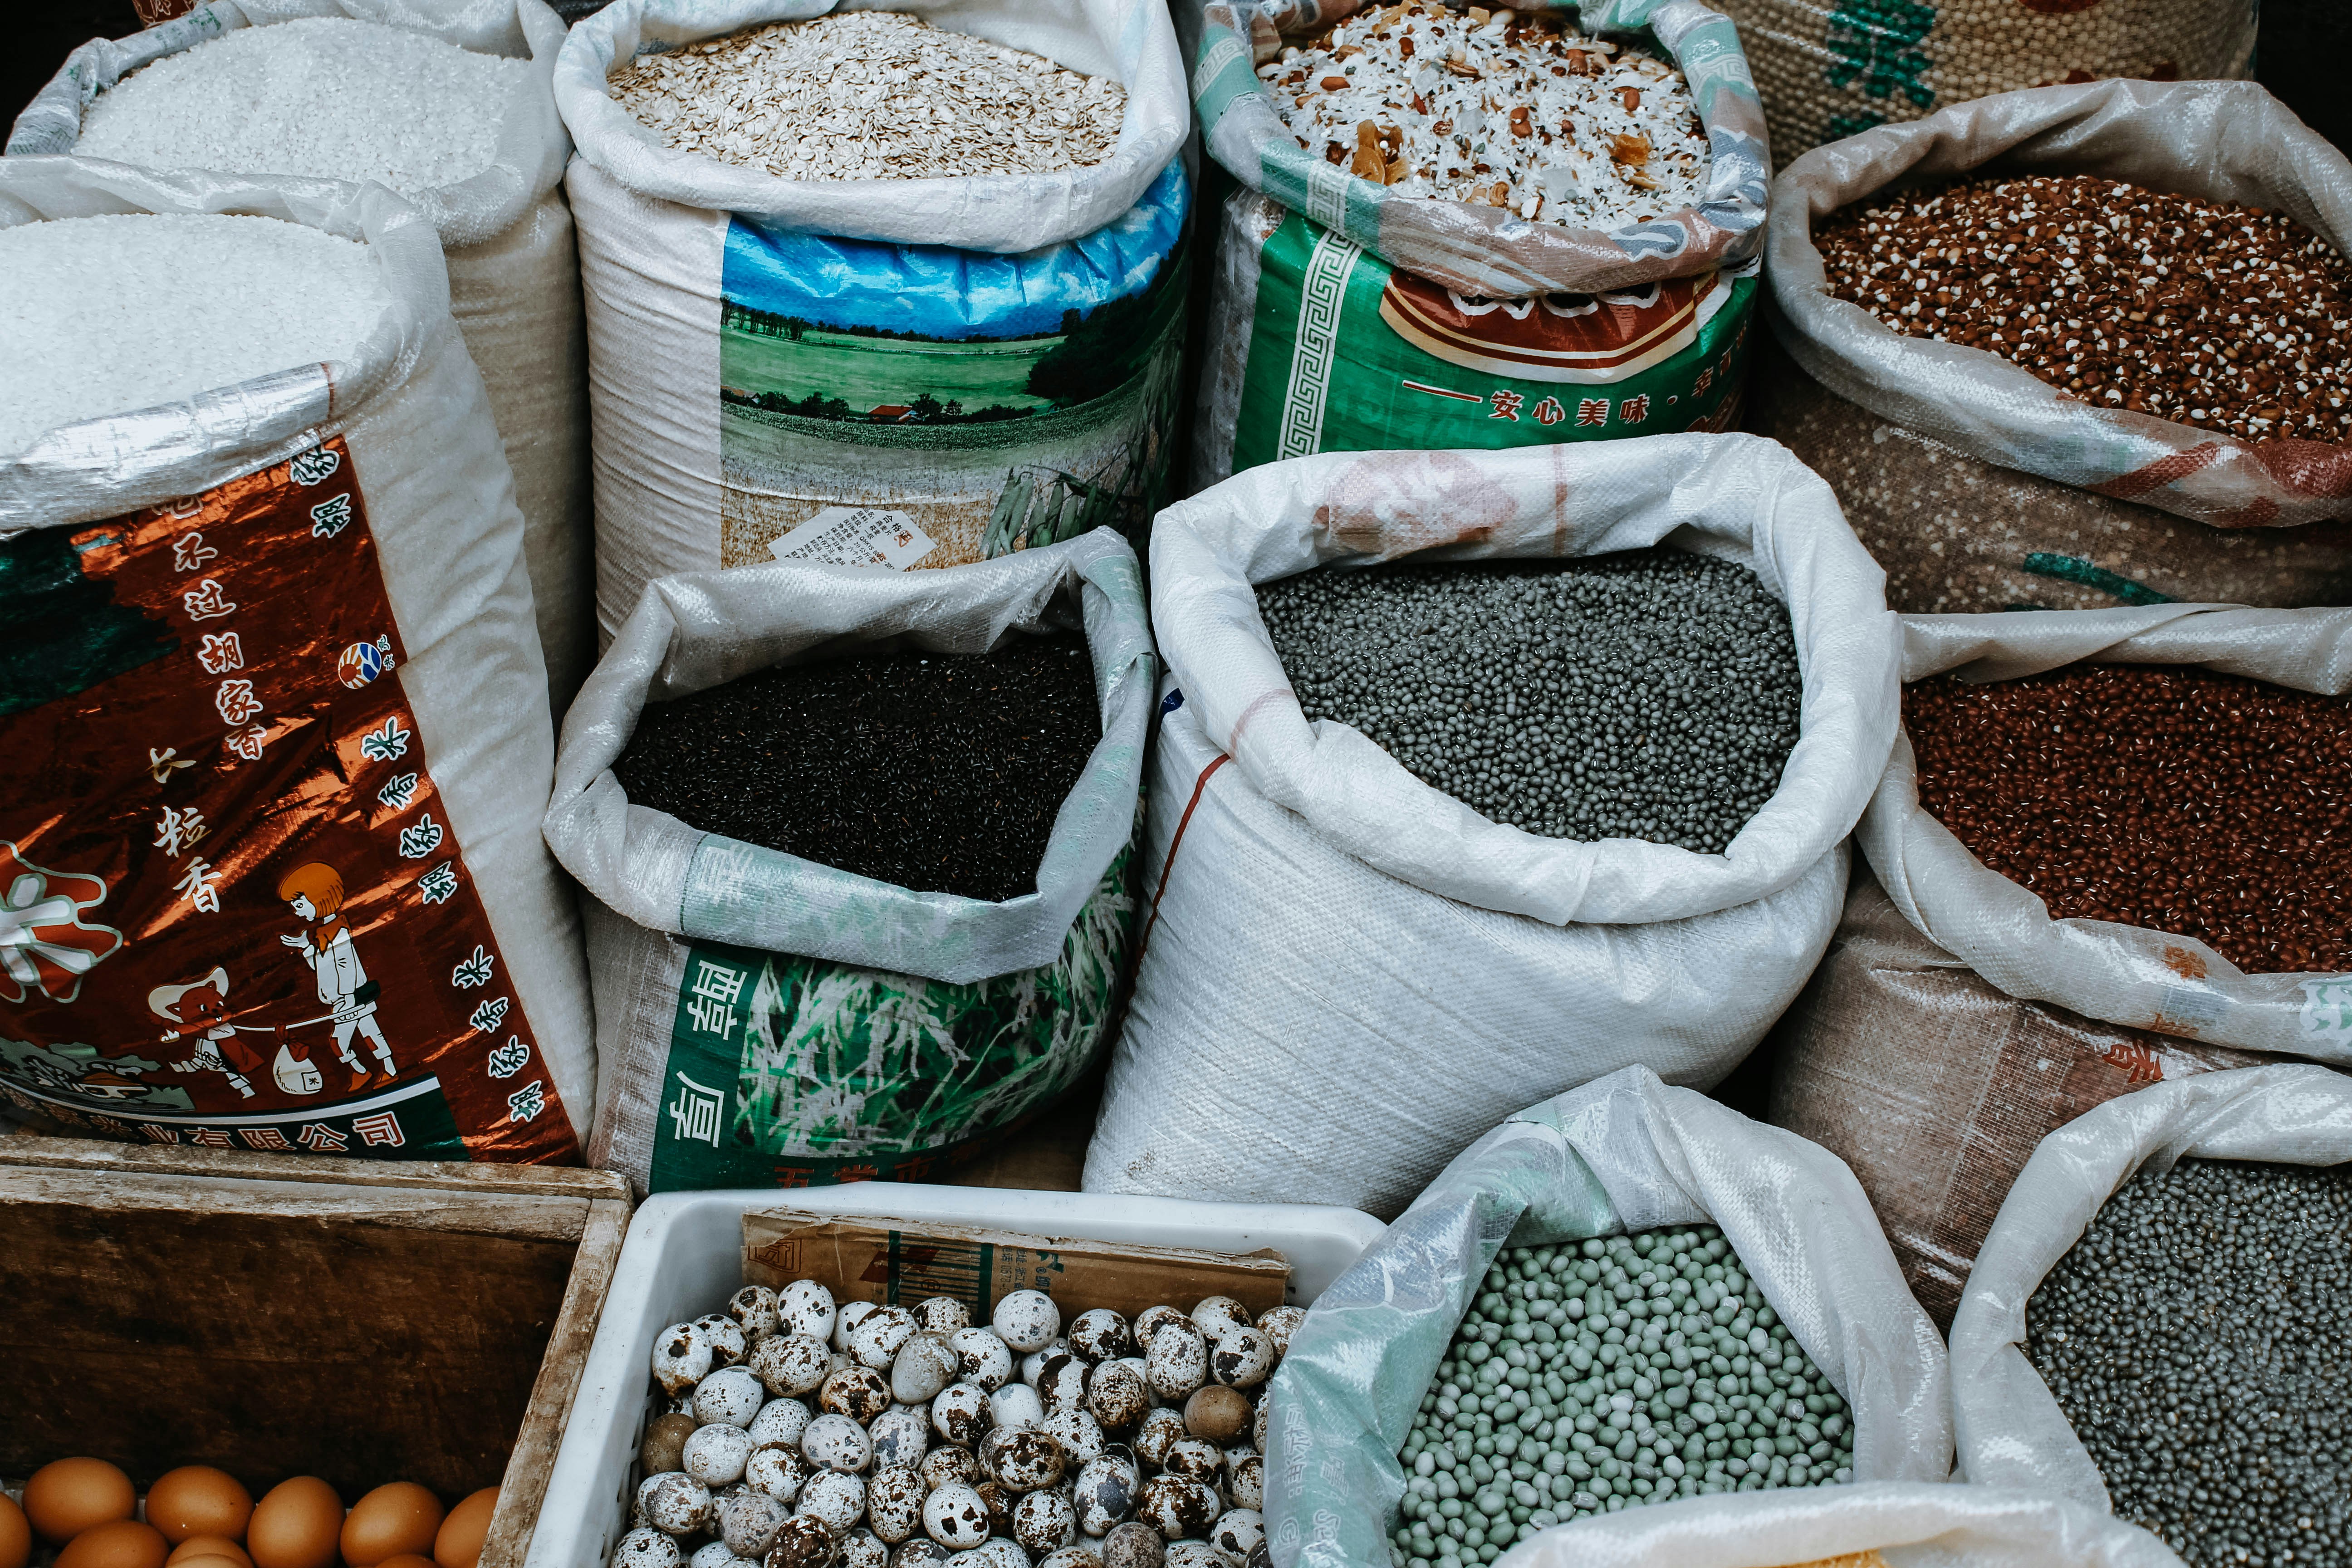
Global Consumption Patterns
World mixed nitrogen, phosphorus and potassium fertilizers market 2026 analysis provides detailed examination of market structure, from production and consumption hubs to international trade flows and price mechanisms. Report establishes baseline using latest available data, identifying United States as unequivocal leader in both production and consumption, position underscored by substantial 28 million tonnes consumption.
Global nitrogenous fertilizers market report 2026 analysis shows global consumption heavily concentrated, China 42M, India 37M, US 34M accounting for combined 33% world demand. That concentration means policy changes in China export policy or India subsidy policy have outsized impact on global trade.
Fertilizer market update covering 2025 trade data extending to April 2026 shows production exceeding 190 million tonnes annually, with global fertilizer consumption growth slowing after record 207 million tonnes in 2024, reflecting affordability challenges.
Pakistan urea sales data shows local consumption patterns affected by subsidy and pricing. Regional demand growth likely to run in mid-single digits annually through 2035 in many developing markets, implying volume expansion of 40-55% over forecast period, driven by population growth, urbanization, and food processing expansion.
Food and beverage segment expected to have highest CAGR during forecast period for specialty chemicals, but for fertilizers, staple crops wheat, corn, rice drive nitrogen demand, while fruits and vegetables drive potash and specialty NPK demand.
Trade Analysis – Flows, Disruptions, And Pricing
Global fertilizer trade recorded 725 shipments between June 2026 and May 2026, 2% year-over-year increase, involving 96 verified exporters and 174 buyers. US completed 19,976 shipments, China 19,325 and Spain 17,153. International trade has approximately 1.8 million shipments per year for agricultural fertilizers.
China prilled urea indicative 345-350 dollars PMT FOB netback, Brazil MAP up to 850 dollars PMT CFR, showing regional spread driven by raw material costs and freight. Urea traded at 502.50 dollars per tonne May 22, down 7.37% from previous day and more than 27% lower over past month according to Trading Economics data, illustrating volatility.
Weekly update global fertiliser markets w/e 23.10.2026 notes India prepares to return to urea market as global fertiliser supply pressures intensify. High raw material costs placing pressure on producer margins, with some manufacturers reducing output rather than accepting lower finished-product prices.
Global fertilizer prices projected to rise more than 30% in 2026 compared to 2025 levels, according to World Bank and Oxford Economics. Fertilizer price index increased by more than 12% in first quarter 2026 compared with previous quarter. Urea prices surged 53.7% in March to 725.6 dollars per metric ton, highest level in four years. World Bank Commodity Markets Outlook projects fertilizer prices will rise by average of 31% across full year, reaching worst affordability levels since 2022. DAP prices forecast to climb 6%, and MOP prices to increase 12%.
Urea prices jumped 55% since conflict began in late February according to European Commission. In Argentina benchmark urea surged to around 1,000 dollars per tonne from 500 dollars before crisis. Food and Agriculture Organization warned global fertilizer prices could average 15% to 20% higher in first half of 2026 if crisis continues.
Global fertilizer market faces long recovery, according to CoBank Knowledge Exchange report, fertilizer markets expected to remain under pressure through 2028 as global supply disruptions and production challenges continue affecting nutrient availability. Ongoing uncertainty in international markets, along with tight supplies of key raw materials, expected to support higher prices for several more years. Conflict in Middle East, tight supply, damaged production capacity could keep prices above pre-war levels through 2027-2028.
Raw Material Costs And Impact On Related Industries
As natural gas and crude oil are core raw materials for fertilizer production, their skyrocketing prices have directly driven up cost of agricultural inputs. Sulfur prices surged more than 130% since early 2026, directly affecting phosphate production because sulfuric acid required to produce DAP and MAP from phosphate rock. Sulfur is byproduct of oil and gas refining, when oil supply falls by 5.2%, 5.5 million barrels per day in 2026 as projected, sulfur availability also falls.
For food-grade minerals, fertilizer trends affect related markets. Sulfuric acid price drives zinc sulfate production costs. Zinc sulfate tracks zinc LME plus sulfuric acid. When sulfur surges 130%, zinc sulfate food grade monohydrate costs rise even if zinc metal stable. Phosphate rock processing competes with food-grade dicalcium phosphate production. Higher DAP prices incentivize phosphate rock producers to prioritize fertilizer grade over food grade, tightening food-grade phosphate supply.
Ammonia and urea price increases raise costs for chelated minerals like zinc bisglycinate that use ammonia in synthesis.
NDSU expects average urea prices to reach around 496 dollars per MT in 2027, while StoneX believes volatility may increase without necessarily keeping prices at exceptionally high levels for extended period.
Outlook And Strategic Implications
Global fertilizer market weekly update CW44 October 19-26 2026 notes China recorded strong export growth across three major nitrogen products September 2026, while India's urea imports reached 5.59 million MT increase 40.5% year-on-year. That indicates China export policy easing but India import dependency growing.
Market covering 2025 trade data extending to April 2026 and price data through May 2026 shows production exceeds 190 million tonnes annually, consumption growth slowing after record 207 million tonnes in 2024.
For buyers, practical approach includes monitoring natural gas, crude oil, and sulfur as leading indicators, tracking Strait of Hormuz shipping as critical chokepoint where one-third of nitrogen trade passes, and building tiered budgets with base, pressure, and disruption cases. Companies reassessing supply chains prioritizing resilience alongside cost efficiency will accelerate regionalization trends, encourage investment in integrated production hubs, and increase strategic importance of countries with secure energy and feedstock access.
Ultimately, global fertilizer industry report shows market reaching 220 to 239 billion in 2026, production 235 MMT, consumption 190 MMT, growth 2.1% to 3.65% CAGR through 2035, with trade 1.8 million shipments per year but heavily concentrated, with US, China, Spain leading, and China 42M, India 37M, US 34M accounting for 33% demand. Trade analysis reveals 78.7% export growth from China September 2026, 40.5% import growth in India, and 130% sulfur surge, all shaping pricing and availability through 2027-2028.
Sources:
Fertilizer Market Companies Size & Trends 2026-2035 – Precedence Research – global market size 220.31B 2026 to 284.58B 2035 CAGR 2.89% – trade 725 shipments – US 19976 China 19325 Spain 17153 – https://precedenceresearch.com
Fertilizer Market Size Forecasts Report 2026-2035 – GM Insights – market 148B 2025 to 173B 2026 2.1% CAGR to 183B 2035 – manufacturer-level production trade consumption – https://gminsights.com
Global Fertilizer Market Weekly Update CW44 October 19-26 2026 – China export growth 2.45M MT up 78.7% – India urea imports 5.59M MT up 40.5% – sulfur imports 140900 MT down 82.2% – https://golden-raven.com
Butter Milk Powder
Found this useful?