Naphtha: Petrochemical Applications and Global Market Trends
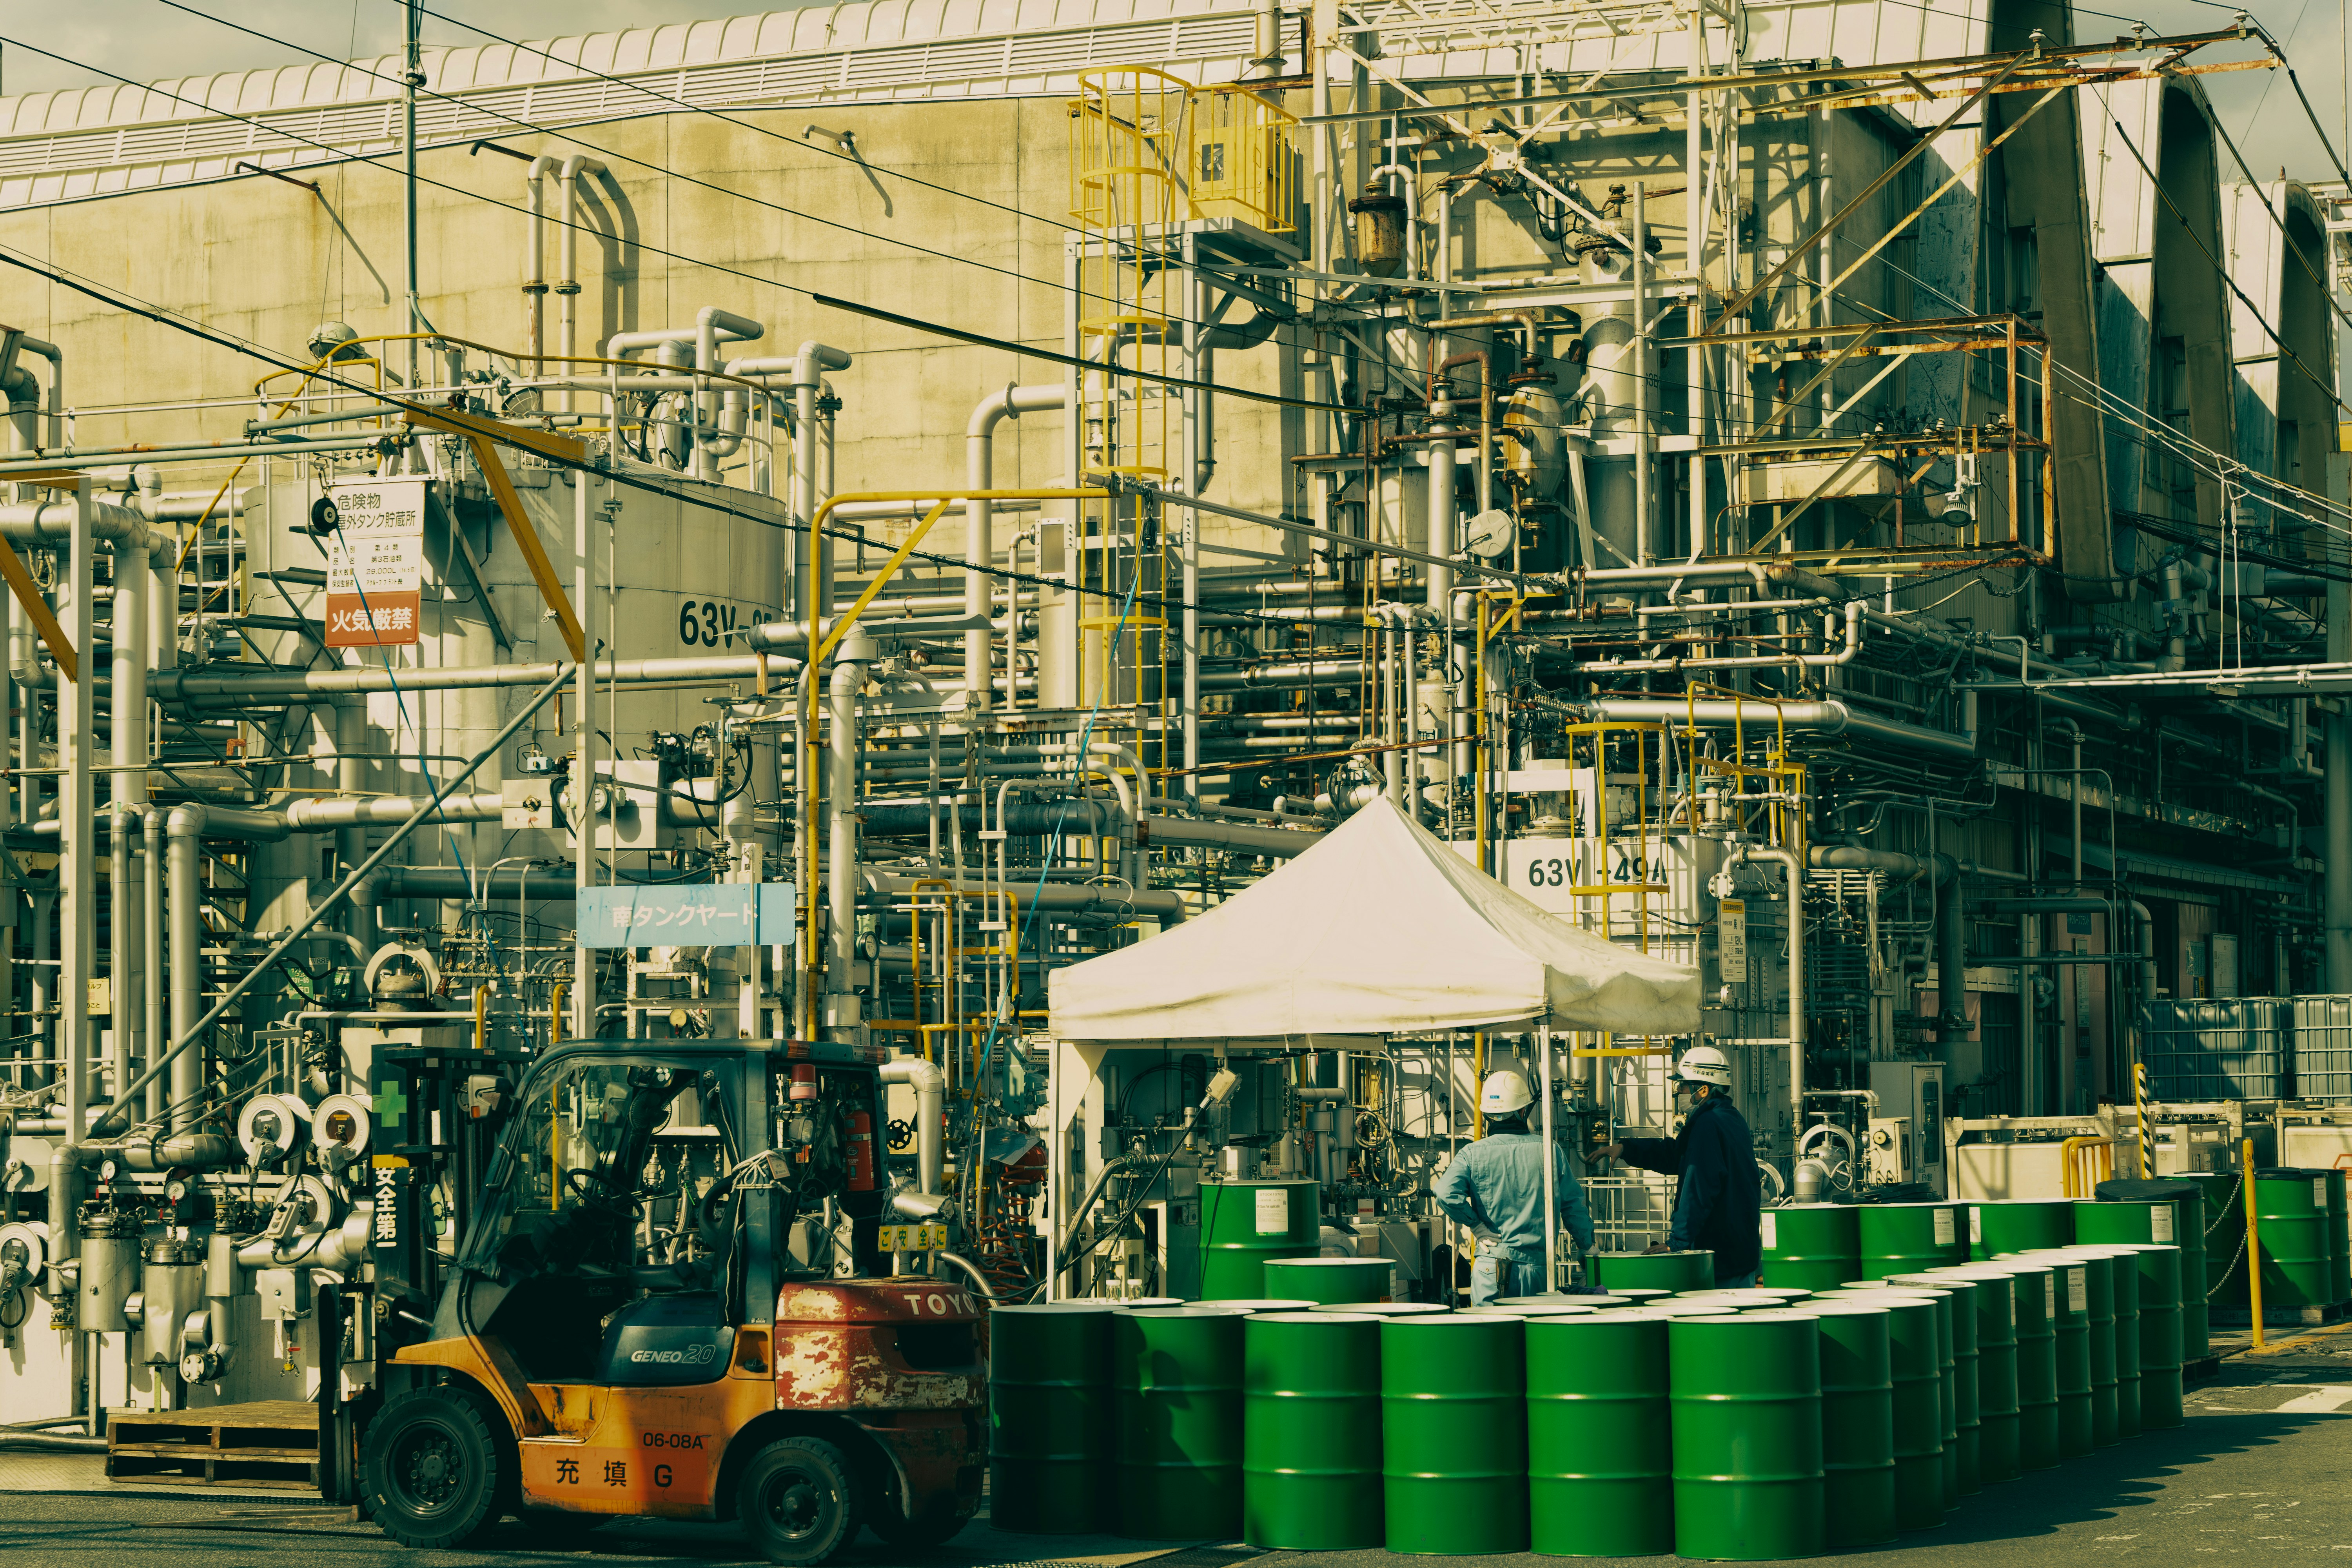
Naphtha is one of the most important feedstocks in the global petrochemical industry. Refineries produce this petroleum-derived liquid during crude oil processing, and chemical manufacturers use it to produce essential building blocks for plastics, synthetic fibres, packaging materials and industrial chemicals.
Demand for naphtha closely follows activity in the petrochemical and refining sectors. Changes in crude oil prices, refinery output, transportation costs and regional manufacturing capacity can influence its availability and purchasing costs.
For chemical traders, importers, exporters and procurement managers, understanding naphtha applications and global market trends helps improve sourcing decisions. Buyers must consider product specifications, regional supply conditions and feedstock alternatives when evaluating purchasing opportunities.
What Is Naphtha and How Is It Produced?
Naphtha is a liquid hydrocarbon mixture obtained mainly through petroleum refining and, in some cases, natural gas condensate processing. It contains hydrocarbons with different molecular structures and boiling points, making it suitable for several industrial applications.
Refineries produce naphtha through processes such as atmospheric distillation, catalytic reforming and other refining operations. Producers separate different hydrocarbon fractions according to their boiling ranges before directing them toward gasoline blending or petrochemical processing.
Light Naphtha and Heavy Naphtha
Naphtha generally falls into two broad categories based on its composition and boiling range.
Light naphtha: Contains relatively lighter hydrocarbons and commonly serves as a feedstock for steam crackers and gasoline blending operations.
Heavy naphtha: Contains heavier hydrocarbon components and commonly enters catalytic reforming units to produce high-octane gasoline components and aromatic hydrocarbons.
The distinction matters because petrochemical plants require specific feedstock characteristics. Buyers should review boiling range, density, paraffin content, naphthene content and other relevant specifications before purchasing.
Important Quality Parameters
Naphtha quality influences processing efficiency and the output of downstream chemical products. Procurement teams should evaluate the following characteristics:
Distillation range: Indicates the temperatures at which different portions of the product evaporate.
Sulfur content: Important for processing requirements and equipment protection.
Density: Helps identify product characteristics and supports commercial measurement.
Paraffin content: Influences the suitability of naphtha for particular cracking processes.
Aromatic content: Affects its suitability for different refining and petrochemical applications.
Buyers should request technical specifications and a Certificate of Analysis (COA) before confirming shipments.
Major Petrochemical Applications of Naphtha
The petrochemical industry represents a major source of naphtha consumption. Steam cracking and catalytic reforming convert its hydrocarbon components into valuable intermediates used across manufacturing industries.
Steam Cracking for Olefin Production
Steam cracking is one of the most important applications of naphtha. In this process, manufacturers heat naphtha with steam at high temperatures to break larger hydrocarbon molecules into smaller compounds.
The process produces several important petrochemical products:
Ethylene: Used in polyethylene manufacturing for packaging films, containers, pipes and industrial applications.
Propylene: A key raw material for polypropylene, which serves packaging, automotive, household and textile industries.
Butadiene: Used in synthetic rubber production for tyres and other rubber-based products.
Pyrolysis gasoline: A valuable by-product that can undergo further processing to recover aromatic compounds.
The proportions of these products depend on feedstock composition and operating conditions. Naphtha crackers provide a flexible source of multiple petrochemical building blocks for downstream manufacturers.
Aromatics and Chemical Intermediates
Heavy naphtha commonly enters catalytic reforming units, where chemical reactions improve its octane characteristics and generate aromatic hydrocarbons.
Important aromatic products include benzene, toluene and xylene, collectively known as BTX.
These chemicals support several industrial value chains:
Benzene contributes to styrene, phenol and other chemical intermediates.
Toluene serves as a solvent and feedstock for several chemical manufacturing processes.
Xylene supports the production of purified terephthalic acid and other aromatic derivatives used in polyester manufacturing.
These applications connect naphtha demand with industries such as textiles, automotive manufacturing, construction, packaging and consumer goods.
Gasoline Blending and Refinery Applications
Naphtha also contributes to gasoline production. Refineries blend suitable naphtha streams with other components to achieve required fuel properties and commercial specifications.
Catalytic reforming can improve the octane quality of selected naphtha fractions. This makes naphtha commercially important to both fuel producers and petrochemical manufacturers.
Competition between gasoline blending and petrochemical feedstock demand can influence refinery allocation decisions, particularly when market conditions change.
Global Naphtha Market Trends and Regional Demand
Global naphtha demand depends heavily on petrochemical production, refinery operations and regional feedstock availability. Asia remains a particularly important market because of its large chemical manufacturing base and demand for plastics, synthetic fibres and industrial intermediates.
Asia-Pacific Petrochemical Market
China, South Korea, Japan and India are important participants in the Asian naphtha market. Their petrochemical industries consume naphtha to manufacture ethylene, propylene and aromatic compounds.
China's expanding petrochemical capacity creates demand for feedstocks, although new production capacity and competition from alternative feedstocks can put pressure on operating margins.
According to S&P Global's 2026 market outlook, Asian naphtha demand faces challenges from petrochemical restructuring, uncertainty surrounding Russian supplies and competition from natural gas liquids.
S&P Global
European Market Developments
European naphtha markets respond to refinery operations, gasoline blending demand and petrochemical manufacturing conditions.
Refinery maintenance, changing crude oil availability and competition between propane and naphtha can influence purchasing decisions. When propane becomes more expensive relative to naphtha, some flexible steam crackers may increase naphtha consumption.
However, weak petrochemical margins can limit the willingness of manufacturers to increase production even when feedstock economics improve.
ICIS+1
Global Demand Outlook for 2026 and 2027
The International Energy Agency's November 2026 Oil Market Report highlights the importance of petrochemical feedstocks in the expected recovery of global oil demand.
The IEA expects global oil demand to increase by 2 million barrels per day in 2027, with LPG, ethane and naphtha accounting for around 80% of that increase as supply chains normalize.
IEA
This outlook indicates that petrochemical feedstock availability will remain an important factor in the energy and chemical markets. However, actual naphtha demand will depend on regional production activity, feedstock competition and refinery supply.
Factors Affecting Naphtha Prices and Supply
Naphtha prices respond to several interconnected market conditions. Chemical buyers should understand these factors when negotiating contracts and planning purchases.
Crude Oil Price Movements
Crude oil represents a major input for conventional refinery-derived naphtha. Changes in international crude prices can influence refinery production costs and naphtha market values.
However, naphtha prices do not always move in exactly the same direction or proportion as crude oil. Petrochemical demand, gasoline blending requirements and regional supply conditions also influence its commercial value.
Petrochemical Production Capacity
Changes in steam cracker operating rates directly affect naphtha consumption. When manufacturers increase production, their feedstock requirements may rise. Conversely, maintenance shutdowns or reduced operating rates can weaken demand.
New petrochemical facilities can also increase regional feedstock requirements, although additional production capacity may create competition in downstream product markets.
Transportation and Geopolitical Disruptions
Naphtha moves through international shipping networks, pipelines and specialized storage facilities. Disruptions at major export terminals, shipping routes or refining locations can affect cargo availability and delivery schedules.
The IEA's 2026 market reporting highlights how disruptions to Middle Eastern refined product and feedstock exports have affected Asian petrochemical operations.
IEA+1
Alternative Feedstock Competition
Naphtha competes with other feedstocks, particularly ethane, propane and butane, in petrochemical manufacturing.
Manufacturers with flexible processing facilities can adjust their feedstock choices according to relative prices and production economics. This flexibility can influence naphtha demand even when overall petrochemical consumption remains stable.
Procurement Considerations for Global Naphtha Buyers
Naphtha procurement requires careful attention to product quality, commercial terms, logistics and supplier reliability. Buyers should evaluate more than the quoted price when arranging domestic or international purchases.
Important considerations include:
Product specifications: Confirm the required naphtha grade, distillation range, density and sulfur content.
Supplier reliability: Review the supplier's delivery history, product consistency and ability to fulfil contracted quantities.
Quality documentation: Request COAs and relevant safety documentation before accepting shipments.
Transportation arrangements: Evaluate shipping costs, storage requirements, insurance and delivery schedules.
Contract terms: Review pricing formulas, payment conditions, quantity tolerances and shipment responsibilities.
Market monitoring: Follow crude oil movements, refinery operations and petrochemical demand to identify suitable purchasing opportunities.
Importers should also consider storage compatibility and safe handling procedures because naphtha is a highly flammable petroleum product. Appropriate storage facilities, ventilation and fire protection measures are essential.
Future Opportunities in the Naphtha Market
The future of naphtha will remain closely connected to the development of the global petrochemical industry. Growing demand for plastics, synthetic materials and chemical intermediates will continue to influence feedstock requirements.
However, the market also faces structural changes. New ethane-based production facilities, alternative feedstocks and competition among petrochemical manufacturers may affect the long-term position of naphtha.
Refinery integration with petrochemical production could provide additional opportunities to improve feedstock utilization and manufacturing efficiency. At the same time, producers must manage changing environmental requirements and operational costs.
For chemical traders and procurement managers, monitoring regional supply developments and downstream demand will remain important when evaluating sourcing opportunities. Buyers who understand naphtha specifications, price movements and supplier capabilities can make more informed purchasing decisions.
Xylene
Found this useful?