
Net-Zero Chemical Industry Roadmaps: Revising Climate Targets After the Hormuz Disruption
The 2026 Hormuz crisis created material deviations from the climate transition assumptions embedded in most chemical industry net-zero roadmaps developed before February 28. The 135-day disruption forced a fundamental recalibration of decarbonization timelines across the global sector.
Climate and decarbonization professionals conducting mid-year reviews must now explicitly acknowledge these shifts. Vague statements claiming progress was merely disrupted will fail CSRD climate target disclosure standards. Companies must quantify the specific deviation from each roadmap assumption in their 2026 progress reports.
Quantifying the Five Critical Roadmap Deviations
Pre-crisis sustainability models relied heavily on a stable geopolitical environment. The disruption introduced five specific deviations that invalidate previous baseline assumptions.
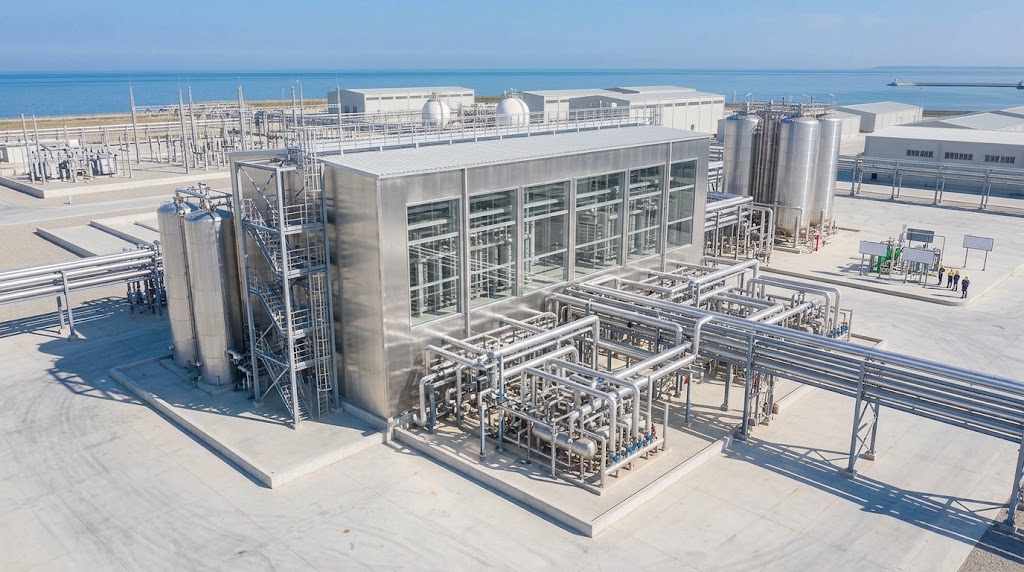
Gulf green ammonia and green hydrogen project timelines experienced delays of 12 to 18 months. Capital expenditure for carbon capture investments faced immediate deferral across major producers. Dow officially confirmed the delay of its Path2Zero initiative as a direct result of these shifting priorities.
European natural gas prices temporarily doubled during the peak disruption period. The Dutch TTF benchmark surged to over €60 per MWh. Simultaneously coal-to-chemicals routes expanded rapidly in China to meet global demand.
This expansion increased the Scope 3 embedded carbon of crisis-period Chinese origin chemicals. Companies must now account for this sudden spike in their annual emissions inventories.
The Reality of Gulf Green Hydrogen Delays
Pre-crisis models assumed rapid scaling of Gulf green ammonia and hydrogen production. The logistical paralysis pushed these critical project timelines back by 12 to 18 months.
Supply chain bottlenecks delayed the delivery of specialized electrolyzer components. Port congestion also stranded essential engineering talent required for facility commissioning.
This delay directly impacts the availability of low-carbon feedstocks for European chemical crackers. Procurement teams must adjust their 2028 sourcing forecasts to reflect this new operational reality.
The absence of this anticipated green volume forces buyers to extend contracts with traditional fossil fuel suppliers. This extension directly contradicts the aggressive phase-out schedules outlined in original net-zero roadmaps.
The delay in Gulf projects also impacts the global pricing dynamics of green ammonia. Scarcity of certified green volumes will maintain a persistent price premium over grey alternatives.
Buyers must prepare for this extended premium period in their long-term budgeting. Relying on imminent price parity is no longer a viable financial strategy.
Deferred Carbon Capture Investments
Capital expenditure priorities shifted dramatically during the 135-day crisis. Companies redirected funds from long-term decarbonization projects to immediate supply chain stabilization.
Dow officially confirmed the delay of its Path2Zero carbon capture initiative. This deferral highlights a broader industry trend of prioritizing operational survival over future emissions reductions.
Sustainability teams must update their capital allocation models to reflect these postponed milestones. Investors will scrutinize these delays during upcoming quarterly earnings calls and sustainability reviews.
The chemical industry cannot achieve its 2030 emissions targets without functional carbon capture infrastructure. Every month of delay compounds the difficulty of meeting future regulatory mandates.
Executive leadership must formally document the financial rationale behind these deferrals. Transparent communication with stakeholders prevents speculation about the long-term viability of corporate climate commitments.
European Natural Gas Price Volatility
European natural gas prices temporarily doubled during the peak of the disruption. The Dutch TTF benchmark surged to over €60 per MWh.
This spike made energy-intensive chemical production economically unviable for many European facilities. Operators faced impossible choices between running at a severe loss or idling production entirely.
This volatility severely disrupted the assumed steady decline in fossil fuel dependency outlined in pre-2026 roadmaps. Facilities were forced to rely on backup fossil fuels to maintain minimum safe operating rates.
The resulting emissions spikes from backup generators and inefficient partial-load operations further derailed annual reduction targets. Climate teams must now isolate these crisis-period emissions from standard operational metrics.
Regulatory bodies recognize this volatility but still require detailed explanations for the resulting carbon footprint increases. Companies must prove they actively mitigated these emissions where operationally feasible.
The Scope 3 Impact of Chinese Coal-to-Chemicals Expansion
The crisis triggered a massive shift in global chemical trade flows. European buyers increasingly sourced alternative chemicals from China to fill regional supply gaps.
Chinese producers expanded coal-to-chemicals routes to meet this sudden surge in international demand. This rapid scaling relied heavily on domestic coal reserves rather than renewable energy sources.
This shift drastically increased the Scope 3 embedded carbon of crisis-period Chinese origin chemicals. Companies relying on these imports will see a temporary but significant spike in their reported carbon footprints.
Procurement departments must update their supplier emission factors to reflect this coal-intensive reality. Failing to do so will result in severe underreporting of total value chain emissions.
The mathematical reality of coal-to-chemicals production is stark. Coal-based processes emit significantly more greenhouse gases per tonne of output than natural gas-based alternatives.
European buyers importing these materials absorb this carbon liability under current Scope 3 accounting rules. This dynamic creates a temporary but severe regression in corporate sustainability metrics.
Meeting CSRD Climate Target Disclosure Standards
Regulatory bodies demand rigorous transparency regarding these operational deviations. Stating simply that progress was disrupted by the Hormuz crisis is entirely insufficient for compliance.
Auditors require quantified data showing the exact variance between planned and actual emissions trajectories. Companies must document the specific financial and operational reasons for each delayed milestone.
This level of detail protects organizations from greenwashing accusations and regulatory penalties. Transparent reporting builds essential trust with stakeholders reviewing the 2026 sustainability disclosures.
External assurance providers will specifically test the mathematical accuracy of these revised roadmaps. Any unexplained gaps between pre-crisis targets and current realities will trigger audit qualifications.
The European Financial Reporting Advisory Group provides strict guidelines for handling material deviations. Companies must reference these specific guidelines in their management commentary sections.
Auditors will cross-reference the revised roadmaps with actual capital expenditure reports. Any discrepancy between stated delays and actual financial outflows will raise immediate red flags.
Revising the 2027 to 2030 Decarbonization Trajectory
The chemical industry must fundamentally rewrite its long-term decarbonization trajectory. The 135-day disruption proved that linear progress toward net-zero is a flawed assumption.
Companies must build resilience into their climate roadmaps to absorb future macroeconomic shocks. This requires maintaining parallel supply chains for both low-carbon and conventional feedstocks.
Financial models must account for extended periods of elevated fossil fuel dependency. Sustainability targets must include explicit contingency buffers for geopolitical supply chain failures.
Executive leadership must approve these revised roadmaps before the end of the third quarter. Delaying this approval will jeopardize the entire 2026 CSRD reporting cycle.
What Buyers Should Do Now
Climate professionals must immediately initiate a comprehensive mid-year net-zero roadmap review. Teams should gather precise data on delayed projects and revised emission factors.
Procurement and sustainability departments must collaborate to update supplier carbon accounting models. This proactive revision ensures credible and compliant CSRD reporting for the 2026 fiscal year.
Organizations should also renegotiate long-term supply agreements to include explicit carbon accounting clauses. These clauses will protect buyers from unexpected Scope 3 spikes during future geopolitical events.
Ready to source Ammonia Anhydrous from verified global suppliers? Explore competitive offers on our platform today.
Sources
https://www.dow.com/en-us/news/2026/path2zero-carbon-capture-delay-announcement
https://www.icis.com/explore/resources/news/2026/dutch-ttf-natural-gas-price-surge-crisis
https://www.csrd-guide.eu/regulatory-updates/2026/material-deviations-climate-target-disclosure
https://www.argusmedia.com/en/news-and-insights/latest-market-news/2026/china-coal-to-chemicals-expansion-scope3-impact
Ammonia Anhydrous
Found this useful?


