
The Circular Economy Supply Chain Paradox: Why Recycled Content Declined During the Hormuz Crisis
Counterintuitively, verified recycled content in European chemical products declined 4.7 percentage points during the April to June 2026 period compared to the first quarter baseline. The 135-day Hormuz disruption theoretically should have favored non-virgin alternatives. Instead, the crisis triggered a severe circular economy reversal under stress. Current recycled content systems are highly optimized for stable supply chains. They collapse rapidly when global logistics fracture. Procurement managers must recognize this paradox to protect their 2028 and 2030 sustainability commitments. Relying on standard circular procurement models during a crisis will lead to immediate compliance backsliding. Companies must proactively redesign their sourcing frameworks to withstand future macroeconomic shocks. The industry needs a fundamental shift in how it measures and manages circularity during periods of extreme volatility.
The Mechanics of the Circular Economy Reversal Under Stress
The decline in verified recycled content stems from three distinct operational failures during the disruption. Mechanically recycled plastic pellet supply chains faced the exact same shipping disruptions as virgin resin. Most of this material moves through intra-Asia trade lanes that experienced severe port congestion and vessel shortages.
Furthermore, recycled content certification and chain-of-custody documentation became entirely impractical during emergency procurement. Force majeure clauses suspended normal supplier qualification processes across the entire chemical industry. Buyers could not wait for audited paperwork when production lines faced imminent shutdowns and revenue loss.
Finally, price incentives heavily favored molecules over provenance. Customers readily accepted non-certified material at crisis pricing rather than waiting for certified recycled alternatives. This immediate survival instinct completely overrode long-term sustainability goals. The market prioritized physical availability over environmental credentials.
Intra-Asia Shipping Disruptions and Recycled Pellet Availability
The assumption that recycled feedstocks offer a localized buffer against global shocks proved entirely false. Mechanically recycled plastic pellets rely heavily on complex international trade routes. The Hormuz crisis bottlenecked these specific corridors just as severely as it did virgin naphtha shipments.
European buyers found their traditional Asian suppliers unable to deliver on time. Port delays and vessel shortages created a universal scarcity of polymer materials. The origin of the plastic mattered far less than its physical availability at the receiving terminal.
This harsh reality shatters the myth of regional feedstock independence. Companies must map their recycled supply chains with the same rigorous detail they apply to virgin materials. A recycled pellet remains a physical commodity subject to unpredictable global freight dynamics. Buyers must account for these logistical vulnerabilities in their strategic planning.
The Collapse of Chain-of-Custody Documentation
Emergency procurement protocols inherently conflict with rigorous sustainability auditing. The 135-day disruption forced chemical companies to prioritize immediate volume over documentation integrity. Force majeure declarations suspended standard supplier qualification workflows across the entire industry.
Procurement teams accepted whatever material arrived at the dock to keep crackers running. Verifying the exact recycled percentage of these emergency shipments became a secondary concern. The administrative burden of chain-of-custody tracking simply could not keep pace with the rapid crisis response.
This documentation gap directly caused the 4.7 percentage point drop in verified content. Buyers physically received recycled material but lacked the auditable proof to claim it in their official ESG reports. This sharp distinction between physical reality and verified reporting is critical for compliance teams to understand.
Molecules Over Provenance in Crisis Pricing
Market dynamics during the disruption heavily penalized buyers who insisted on certified materials. The premium for verified recycled content vanished when operational survival was at stake. Customers accepted non-certified material at crisis pricing to maintain basic operational continuity.
Suppliers holding certified inventory faced the exact same logistical bottlenecks as everyone else. The time required to source and transport verified recycled alternatives exceeded the tolerance of most manufacturing schedules. Procurement managers made rational economic decisions to secure any available polymer.
This behavior highlights a fundamental flaw in current sustainability frameworks. Circular economy commitments often lack the financial and operational resilience to withstand severe market stress. Companies must build explicit flexibility into their contracts to account for these inevitable disruptions.
The Financial Impact of Circular Backsliding
Failing to meet recycled content targets carries direct financial consequences for chemical companies. Many corporate bonds and sustainability-linked loans feature interest rate adjustments tied to ESG performance. Missing these targets due to supply chain disruptions can trigger immediate financial penalties.
Investors are increasingly scrutinizing the gap between stated sustainability goals and actual operational delivery. A sudden drop in verified recycled content signals poor risk management to the market. This perception can negatively impact company valuations and access to green capital.
Procurement teams must quantify the financial risk of circular backsliding in their operational models. Understanding this exposure justifies the upfront cost of building resilient supply chains. Proactive investment in supply chain redundancy is far cheaper than paying penalty interest rates or losing investor confidence.
Regulatory Frameworks and Crisis Response Adaptation
Regulatory bodies must also adapt to the realities of severe supply chain disruptions. Current ESG reporting standards often lack clear guidance on handling force majeure events. This ambiguity leaves chemical companies exposed to unfair compliance penalties during genuine crises.
Industry associations should advocate for temporary reporting safe harbors during major logistical disruptions. These provisions would allow companies to report physical recycled content separately from verified content. Such transparency would provide a much more accurate picture of operational reality.
Regulators must recognize that strict adherence to chain-of-custody rules during a crisis is often impossible. Flexibility in reporting standards will encourage honest disclosure rather than creative accounting. This collaborative approach will ultimately strengthen the credibility of the circular economy.
Building Resilient Supplier Partnerships
Long-term resilience requires deeper collaboration with recycling suppliers. Chemical buyers must move beyond transactional relationships to form strategic partnerships. These alliances ensure priority access to recycled materials when market volatility strikes.
Joint investments in regional sorting and processing facilities can secure dedicated feedstock streams. This vertical integration mitigates the risk of cross-sector competition for waste plastics. Buyers gain reliable supply while suppliers gain guaranteed offtake agreements.
Transparent communication channels are essential during emergency situations. Suppliers must alert buyers immediately about potential certification delays. This early warning system allows procurement teams to activate contingency plans before production lines stall.
Stress-Testing Circular Procurement Strategies for 2028 and 2030
Companies holding ambitious 2028 and 2030 recycled content commitments must take immediate corrective action. Relying on historical data from stable periods will result in repeated compliance failures. Procurement leaders need to stress-test their circular strategies against realistic 60 to 90 day supply disruption scenarios.
Develop secondary sourcing agreements for recycled materials within the same geographic region. This strategy significantly reduces exposure to international shipping bottlenecks during global crises.
Negotiate force majeure clauses that explicitly address sustainability certification delays. These specific provisions protect buyers from compliance penalties when documentation lags behind physical delivery.
Maintain strategic safety stock of verified recycled pellets to buffer against short-term logistical shocks. This dedicated inventory acts as a critical shock absorber for vulnerable production lines.
What Buyers Should Do Now
The chemical industry must confront the inherent fragility of its current circular economy models. The Q2 2026 backsliding serves as a clear warning for future supply chain shocks. Procurement and sustainability teams must collaborate to build truly resilient recycled content strategies.
Acknowledging this vulnerability is the absolute first step toward meaningful improvement. Companies must invest heavily in regional recycling infrastructure and robust documentation systems right now. Waiting for the next crisis will only guarantee another failure to meet vital sustainability targets.
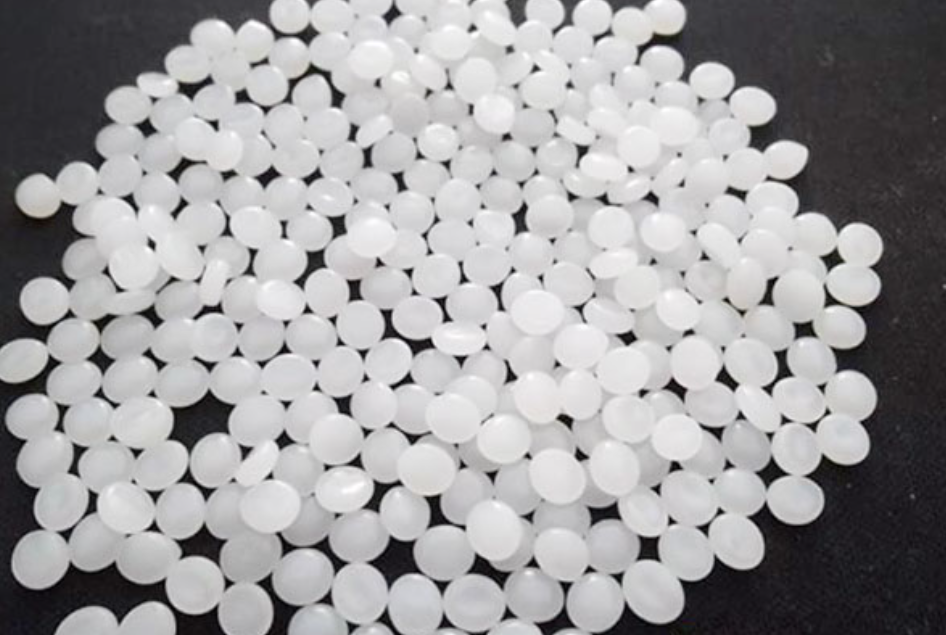
Ready to source High Density Polyethylene (HDPE) from verified global suppliers? Explore competitive offers on our platform today.
Sources
https://www.plasticstoday.com/sustainability/2026/recycled-content-decline-hormuz-crisis
https://www.europeanchemicalindustry.eu/reports/2026/circular-economy-supply-chain-stress-test
https://www.supplychaindive.com/news/2026/chain-of-custody-documentation-emergency-procurement
High Density Polyethylene (HDPE)
Found this useful?


